
Buenaventura (BVN) Stock Still Looks Undervalued After Production Guidance Cut
Compañía de Minas BuenaventuraA has delivered a powerful multi year run, yet a recent pullback and fresh production headlines now put a sharper spotlight on whether its current share price is properly supported by its earnings. With that mix of long term gains and short term disappointment in the air, the valuation question around Buenaventura has become much more specific than just asking if the chart looks strong.
- Over the past 5 years the stock has gained 276.2%, which raises the issue of how much of that advance can be tied to the underlying earning power of the business rather than sentiment alone.
- The recent shortfall in gold output at the San Gabriel mine and the revised 2026 production outlook may affect how investors think about the timing and durability of future profits that ultimately support Buenaventura's earnings based valuation.
- The analysts covering Compañía de Minas BuenaventuraA have run their own numbers. See what analysts think Compañía de Minas BuenaventuraA's shares could be worth.
The issue now is whether Buenaventura's current price, after such a strong long term return and recent operational setbacks, is appropriately aligned with what its earnings suggest it should be worth.
If you are reassessing Compañía de Minas BuenaventuraA after this production update, it can help to compare it with other producers by starting your research with 35 elite gold producer stocks.
Does Compañía de Minas BuenaventuraA Look Undervalued on Earnings?
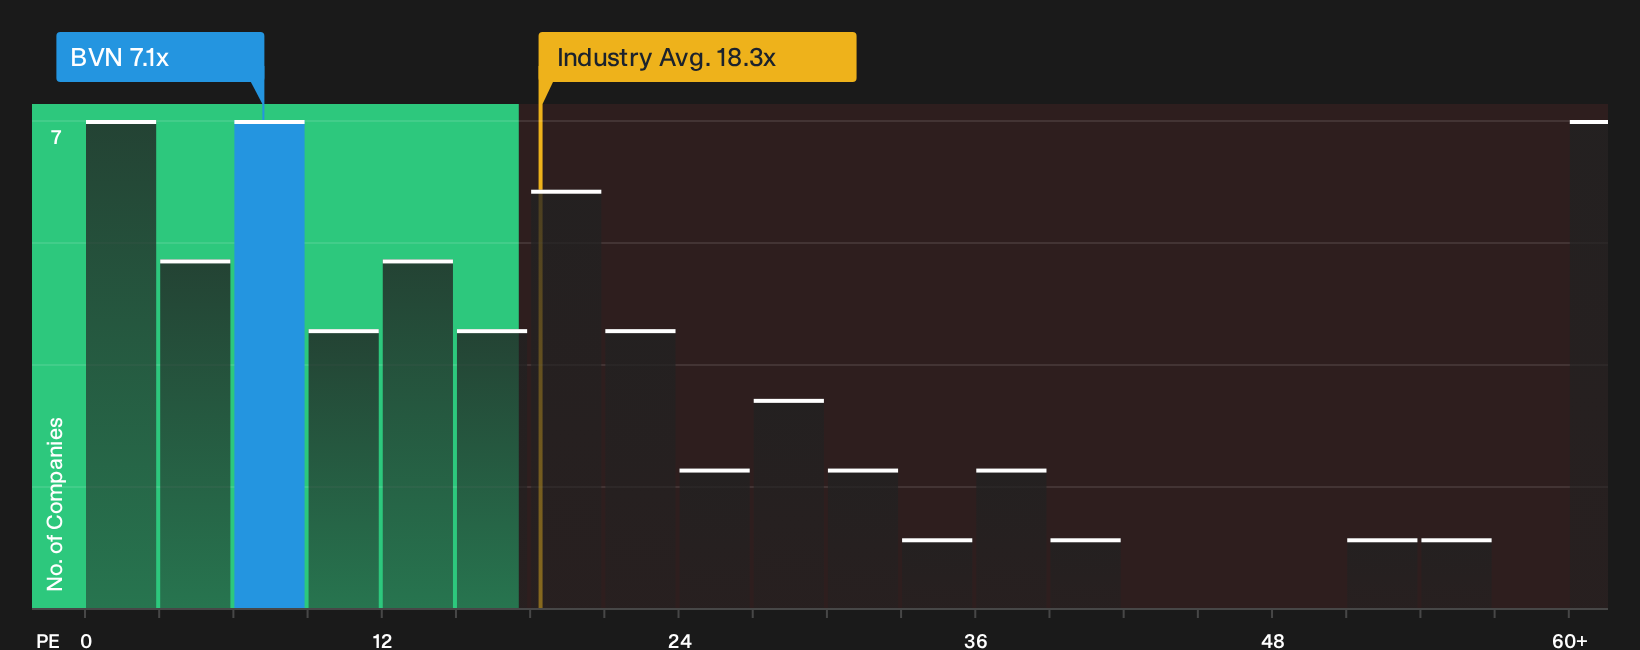
The P/E ratio fits Compañía de Minas BuenaventuraA because earnings remain a key anchor for how the market weighs a cyclical miner. On this measure the stock trades at about 7.2x earnings, which is well below the Metals and Mining sector average of roughly 18.3x and also well under a wider peer group closer to 36.5x. That gap signals investors are paying a lower price for each dollar of current profit than they typically do for comparable producers.
The Fair Ratio model, which looks at factors such as growth, margins, size and risk profile, points to a higher P/E than where Buenaventura changes hands today, so the current multiple screens as undervalued on this framework. Because the San Gabriel guidance cut has already reset expectations, the market is effectively discounting those issues while still leaving the shares priced below what this earnings based yardstick suggests. Explore the numbers behind Compañía de Minas BuenaventuraA's P/E valuation.
The Compañía de Minas BuenaventuraA Narrative: What Would Justify Today's Price?
Compañía de Minas BuenaventuraA's current valuation puzzle sets up the role of Simply Wall St Narratives, which spell out the specific growth, margin and earnings paths that would need to play out for the stock to be worth materially more or materially less than today's price on the Community page. Rather than a single headline multiple or model readout, each scenario lays out its own fair value assumptions so you can compare those inputs with future financial results as they are reported.
Community views on Compañía de Minas BuenaventuraA split between those who see cost pressure and heavy capex as a setup for opportunity and those who see it as a ceiling on returns.
Bull case: 19% undervalued
"The combination of a small net cash position, sizeable dividend inflows from Cerro Verde that reached US$274 million by July 2026, and a move to distribute at least 40% of prior year net income as dividends gives Compañía de Minas BuenaventuraA room to fund roughly US$500 million of 2026 capex while still supporting earnings resilience..."
Discover why this Narrative puts Compañía de Minas BuenaventuraA at 19% undervalued.
Bear case: 10% overvalued
"San Gabriel is only 96% complete and still depends on remaining permits and a successful commissioning process, so any delay in energization, C3 and C4 testing or final approvals could push back production and weigh on revenue and near term cash flow..."
Explore why this Narrative puts Compañía de Minas BuenaventuraA at 10% overvalued.
One more Buenaventura check that belongs beside the valuation work
Compañía de Minas BuenaventuraA’s price tag is only part of the story, because the executives steering the business and the way they are rewarded can heavily influence how future decisions line up with shareholders. See who runs Compañía de Minas BuenaventuraA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com