
CenterPoint Energy (CNP) Lifts Dividend, Is It A Bargain Or Fully Priced?
Dividend move puts CenterPoint Energy in focus
CenterPoint Energy (CNP) has drawn fresh attention after lifting its dividend by 9.1% compared with last year, extending a five year pattern of average annual dividend increases of 8.33%.
The utility also reports an expected 8.52% earnings expansion for fiscal 2026. This combination places income potential and anticipated profit growth at the center of the stock’s current appeal.
Recent trading shows CenterPoint Energy giving up 2.44% on a one day share price move to US$39.56, although the stock is still up 3.51% on a 30 day share price basis and has delivered a 59.35% total shareholder return over three years. This suggests that long term holders have been rewarded even as near term momentum has cooled slightly.
Scan other income plays moving on fresh dividend news, such as CenterPoint Energy, by reviewing our curated list of 8 dividend fortresses in the Utilities space and beyond.
CenterPoint Energy now offers a richer dividend and an earnings outlook that points higher, yet the share price has cooled in the short term. Is this a fair entry today, or a situation that rewards patience for a cheaper shot?
Most Popular Narrative: 11% Undervalued
CenterPoint Energy last closed at $39.56, while the most widely followed narrative framework pegs fair value at about $44.41 using a 7.24% discount rate. That gap frames the current debate around whether the recent pullback is offering income investors a margin of safety.
CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035, which ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion and therefore to future revenue and earnings.
See why 5 investors see CenterPoint Energy as 11% undervalued.
Result: Fair Value of $44.41 (UNDERVALUED)
Still, the bullish CenterPoint Energy story leans heavily on premium valuation and ambitious capex, so any reset in earnings expectations or funding costs could quickly challenge it.
Find out about the key risks to this CenterPoint Energy narrative.
Another View: CenterPoint Energy Through The P/E Lens
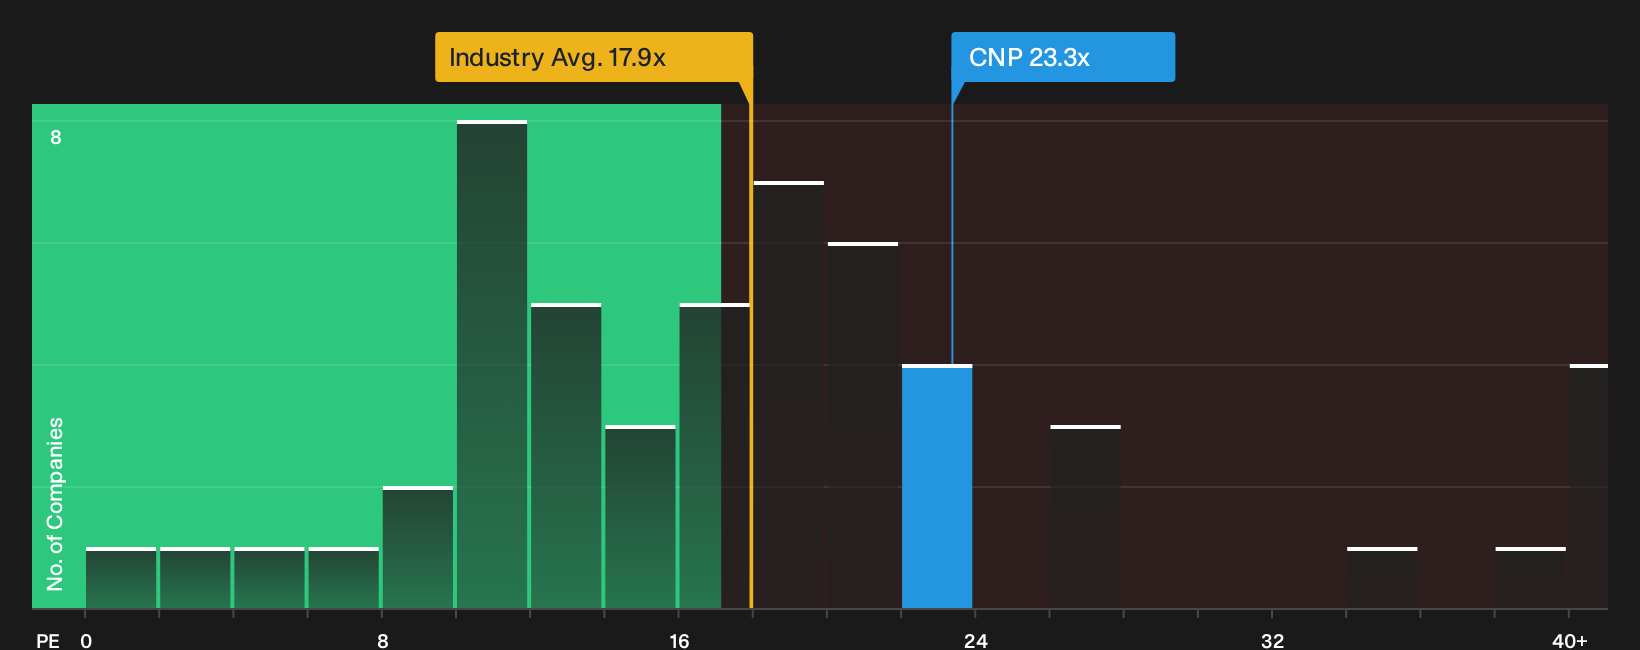
Look at CenterPoint Energy through the simple P/E lens and the story flips. The stock trades on 23.3x earnings, above both the peer average of 20x and the global integrated utilities group at 17.9x. The fair ratio sits at 20.9x, which hints that investors are already paying up and leaves the question of how much margin for error is really left.
For a closer look at how this earnings based yardstick lines up against the current price, and what it could mean for valuation risk if sentiment cools, check out See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CenterPoint Energy can make the picture feel fuzzy, so move fast, review the full data set, and weigh both sides for yourself with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond CenterPoint Energy?
Do not stop with CenterPoint Energy alone. Use the screener to surface fresh opportunities, compare income potential, and pressure test your watchlist against hard fundamentals.
- Target resilient income by reviewing a curated set of 8 dividend fortresses that aim to balance yield with staying power.
- Hunt for mispriced quality and see which companies show up in the 35 high quality undervalued stocks before the crowd catches on.
- Focus on financial strength first and build a shortlist from the list of solid balance sheet and fundamentals (25 results) so weaker balance sheets do not quietly drag on your returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com