
Icahn Enterprises (IEP) Could Be 41% Below Fair Value On A Tougher Market Read
Icahn Enterprises (IEP) has drawn fresh attention after its units closed at US$6.47 on 16 October 2026, capping a period in which returns have moved differently across recent months and years.
Recent trading has been heavy on downside pressure, with Icahn Enterprises posting a 1-day share price return of down 2.71% and a 30-day share price return of down 7.17%. However, the 1-year total shareholder return of 0.74% contrasts sharply with the 5-year total shareholder return of down 69.01%. This points to fading longer term momentum, despite short term income and distribution effects supporting headline returns.
Compare Icahn Enterprises' recent swings with a hand-picked set of income and value ideas using the 8 dividend fortresses as a starting point.
Bulls view Icahn Enterprises as a discounted collection of hard assets and cash flows, while bears highlight losses and long-term value erosion. The key question is which side the current valuation markers appear to support.
Preferred Multiple of 0.4x: Is it justified?
On simple revenue terms, Icahn Enterprises is being valued at a P/S of 0.4x, which sits well below both peers and the broader Global Industrials group.
The P/S multiple compares the value the market assigns to a business with the sales it generates. For a diversified partnership like Icahn Enterprises, which spans energy, automotive, real estate, food packaging, home fashion, pharma and investment activities, this metric can be useful when profits are volatile or losses are reported, as is the case here with the group posting a net loss of $515.0m on revenue of $10.389b.
At 0.4x sales, Icahn Enterprises is being priced at roughly half the Global Industrials industry average of 0.8x. The discount is even starker against its own peer set, where the average P/S comes in at 2.3x. That gap suggests the market is assigning a heavy penalty to the partnership structure, the loss-making profile and the higher risk funding base, even though revenue is anchored mainly in large, tangible operations such as refining and automotive services.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 0.4x (UNDERVALUED)
Still, Icahn Enterprises carries clear risks, including ongoing net losses and a heavy reliance on cyclical energy and automotive divisions that could strain the low P/S case.
Find out about the key risks to this Icahn Enterprises narrative.
Another View: Icahn Enterprises Through A Cash Flow Lens
The P/S gap looks large, yet our DCF model also points to a discount. Icahn Enterprises units last closed at $6.47, while the SWS DCF model estimates a future cash flow value of $9.12. That implies the market is pricing in heavy risk. Is it overdoing the pessimism or seeing something the ratios miss?
Look into how the SWS DCF model arrives at its fair value.
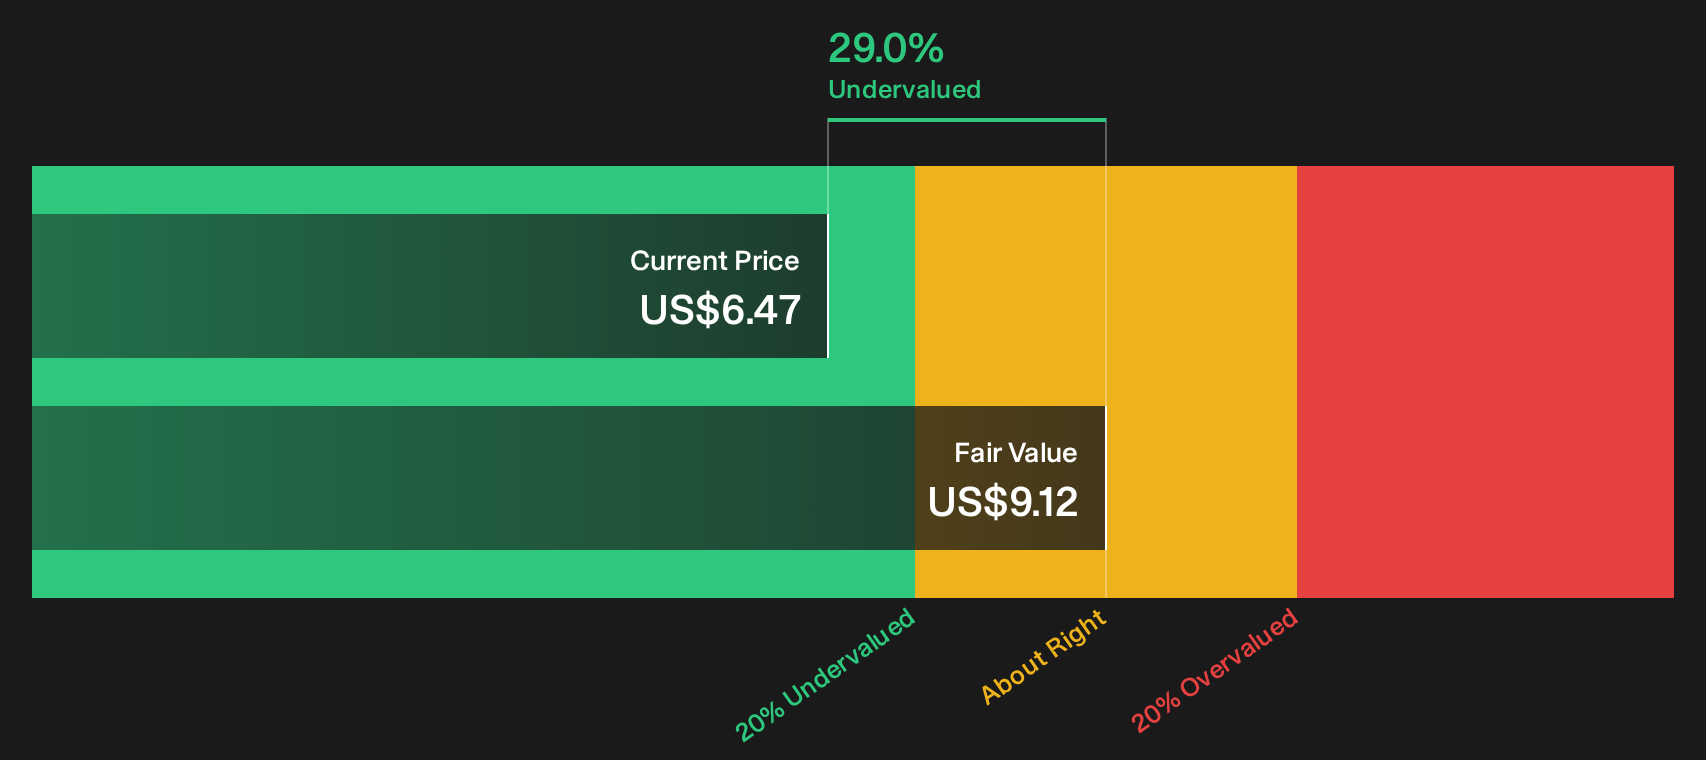
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Icahn Enterprises for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Icahn Enterprises can pull you in either direction, so move quickly past the headline numbers and test the data yourself. To weigh both the concerns and potential upsides side by side, start with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Icahn Enterprises?
If Icahn Enterprises has you thinking harder about risk and reward, do not stop at one ticker. Cast the net wider and let data do the heavy lifting.
- Target steadier potential outcomes by focusing on resilient balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing mismatches that might suit your return goals using the 35 high quality undervalued stocks.
- Spot quieter opportunities with cleaner fundamentals before the crowd pays attention through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com