
Is Hinge Health (HNGE) Trading At A Premium After A 128% Rally?
Hinge Health has delivered a powerful run in 2026, and the share price strength puts a spotlight on what investors are really paying for in terms of earnings. With that backdrop, the key issue is whether the current valuation rests on an earnings profile that can support today’s price.
- The stock is up 128.2% year to date. This raises the question of how much earnings power the market is already factoring in.
- The business model relies on scaling its digital musculoskeletal platform. As a result, the path from revenue growth to consistent earnings and cash generation may be a crucial driver of what investors are willing to pay.
- There is a second opinion on Hinge Health worth weighing. See what analysts think Hinge Health's shares could be worth.
The issue now is whether Hinge Health’s current share price is justified by its earnings when measured against the Fair Ratio benchmark.
If you want a second reference point while you assess whether Hinge Health’s earnings support this year’s price move, compare it with companies from 33 healthcare AI stocks
Does Hinge Health Look Pricey on Earnings?
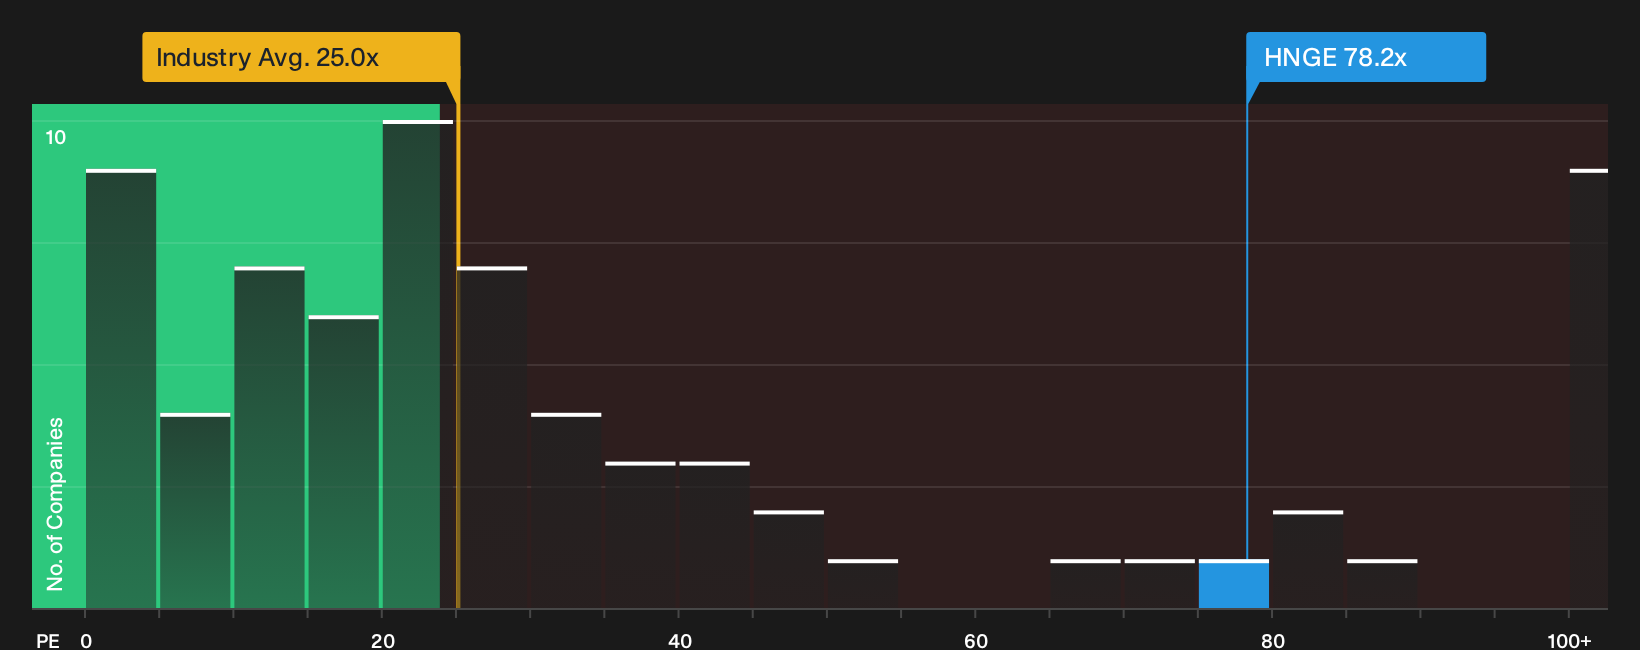
P/E works well for Hinge Health because earnings are already positive, so the ratio ties directly to what shareholders receive today. On this measure, the stock trades at about 78.2x earnings, which is far above the Healthcare industry average of roughly 25.0x and clearly ahead of the peer group on around 28.1x. That is a big gap for a single metric to carry.
The Fair Ratio benchmark, which reflects what a tailored earnings multiple might look like after accounting for Hinge Health’s business quality, risk profile and scale, sits meaningfully below the current P/E. The market is therefore asking you to pay a premium multiple that already prices in a strong earnings profile. The key question is whether Hinge Health can deliver an earnings path that lives up to what this valuation implies for future cash generation and resilience. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hinge Health pick up where this valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or materially less than today's price, as discussed on the Community page. Each Narrative ties Hinge Health's potential catalysts and key risks to a specific estimated worth, so you can track over time which storyline appears to match what actually happens.
Community views on Hinge Health are split between those who see exceptional execution that is not yet fully recognised and those who think expectations already stretch the story.
Bull case: 28% undervalued
"Hinge Health’s ability to scale without proportional cost increases is evident in its margin profile, with gross margins widened to 87% and operating margins at 29%..."
Discover why this Narrative puts Hinge Health at 28% undervalued.
Bear case: 16% overvalued
"Although the move to engagement based pricing is aligned with client interests, the model ties revenue more tightly to actual member usage..."
Explore why this Narrative puts Hinge Health at 16% overvalued.
Hinge Health's valuation still leaves one big question hanging
Price multiples tell you what investors are paying today, but analyst projections for Hinge Health a few years out offer a separate reference point that can either challenge or echo that picture. Explore where analysts expect Hinge Health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com