
Kyowa Kirin (TSE:4151) Posts New XLH Data, Is The Discount Too Wide?
Kyowa Kirin (TSE:4151) has drawn fresh attention after publishing three year real world findings from its XLH Disease Monitoring Program, highlighting outcomes for adults with X linked hypophosphatemia treated with CRYSVITA and conventional Pi/D therapy.
Short term momentum around Kyowa Kirin has picked up, with a 1 day share price return of 1.98% and a 7 day move of 5.16%. However, the 90 day share price return is down 9.63% and the year to date share price return is down 5.57%. The 1 year total shareholder return of 6.79% and 3 year total shareholder return of 8.75% contrast with a 5 year total shareholder return that is down 29.24%. This points to improving recent sentiment but a still mixed longer term record as the market weighs new XLH data against the broader rare disease pipeline.
Scan Kyowa Kirin’s peers in rare disease and specialty treatments by reviewing our hand picked list of solid balance sheet and fundamentals (22 results) that investors are watching around catalysts such as these XLH data updates.
Kyowa Kirin trades at a sizeable intrinsic discount, even as the share price has just moved higher on XLH data. Is the market being prudently cautious, or is it mispricing that gap in expectations?
Preferred Price-to-Earnings of 15.3x: Is it justified?
On the numbers provided, Kyowa Kirin trades on a P/E of 15.3x, which puts the current ¥2,374 share price in a zone where value and quality are pulling in different directions.
The P/E ratio compares the market price per share with earnings per share, so a higher multiple usually reflects stronger profit expectations or a perception of resilience. For a specialist pharmaceuticals group with a rare disease focus, investors often watch this measure closely because earnings can be shaped by trial progress, regulatory events and patent cycles.
Kyowa Kirin is described as good value against a peer P/E average of 16.4x and against an estimated fair P/E of 21x, yet expensive versus the broader JP Pharmaceuticals industry at 14.3x. That mix suggests the market is pricing the business at a premium to the sector while still leaving a gap to the level the fair ratio work points toward.
Explore the SWS fair ratio for Kyowa Kirin.
Result: Price-to-Earnings of 15.3x (ABOUT RIGHT)
Still, the XLH story can be knocked off course if late stage trials in other pipeline assets disappoint, or if pricing pressure builds across Kyowa Kirin’s rare disease portfolio.
Find out about the key risks to this Kyowa Kirin narrative.
Another view on Kyowa Kirin’s value
While the 15.3x P/E suggests Kyowa Kirin is roughly in line with what the market is willing to pay today, the SWS DCF model points in a different direction. At ¥2,374 against an estimated future cash flow value of ¥3,679.22, the stock screens as materially undervalued on that framework.
DCF work leans on long term cash generation and discount rates, so it often reacts slowly when sentiment or trial headlines move quickly. That gap between price and DCF outcome can signal either a margin of safety or a warning that assumptions are too generous. Which side of that trade do you think the XLH data will ultimately support?
Look into how the SWS DCF model arrives at its fair value.
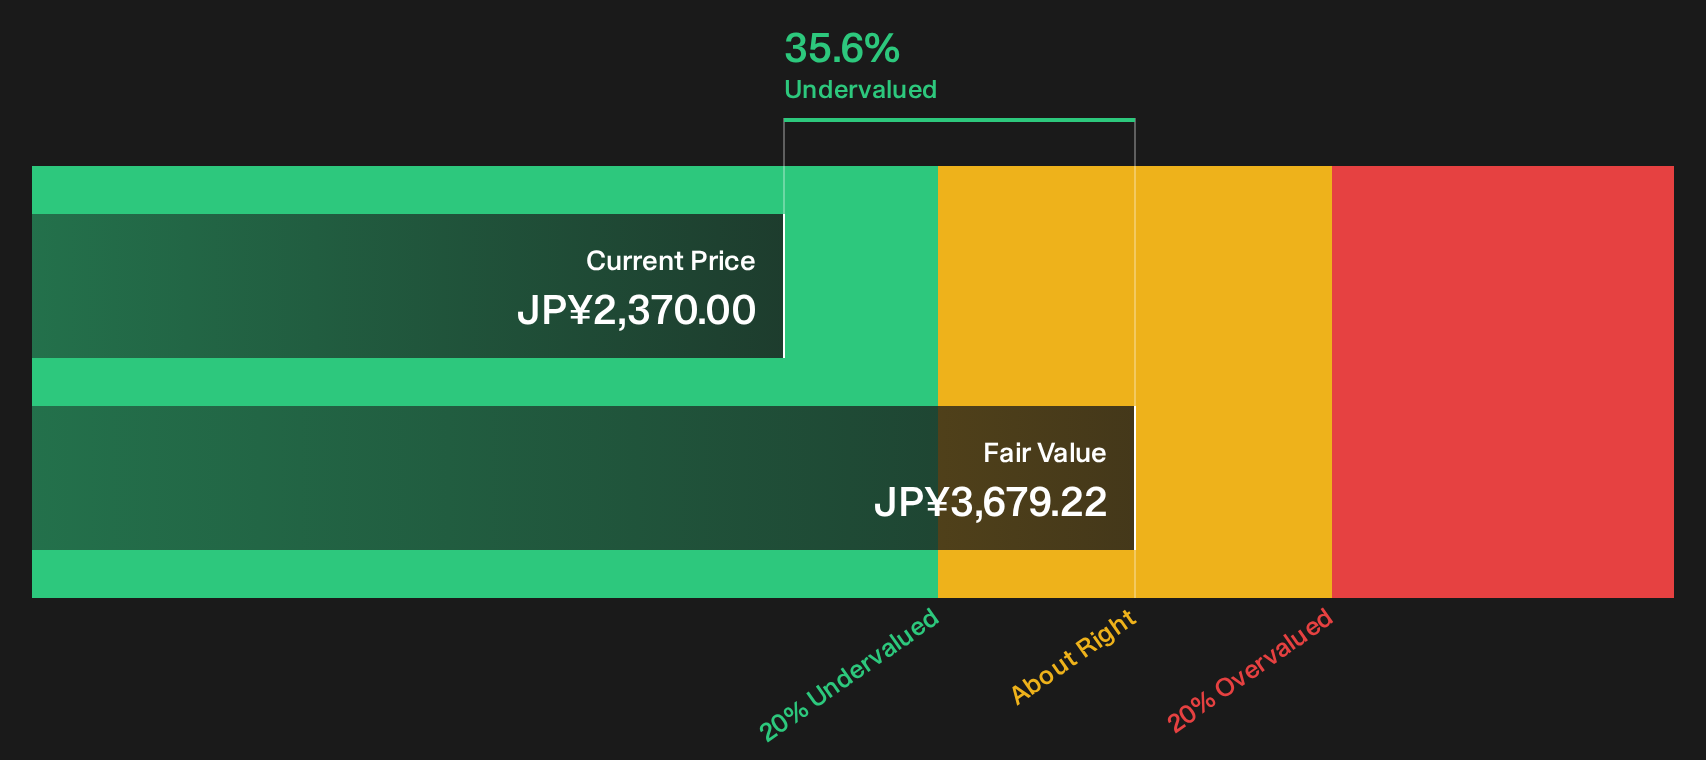
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyowa Kirin for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If sentiment around Kyowa Kirin feels conflicted, that is the point, and it is exactly why you should move quickly and test the numbers yourself. To see what optimism in the data actually looks like in practice, start with the 4 key rewards.
Looking for more Kyowa Kirin investment ideas?
Do not stop at Kyowa Kirin. Broaden your watchlist with fresh ideas so you are not relying on a single story to carry your portfolio.
- Target opportunities with stronger downside protection by reviewing a hand picked set of 21 resilient stocks with low risk scores that can help balance bolder positions.
- Look for quality at a discount by scanning the 73 high quality undiscovered gems that screen well on fundamentals yet still fly under most investors’ radar.
- Assess potential income ideas by reviewing the 29 dividend fortresses that combine higher yields with balance sheet support for those payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com