
Is Ryohin Keikaku (TSE:7453) Fairly Valued As Dividend Growth And FY27 Guidance Lift Expectations?
Ryohin Keikaku (TSE:7453) has put dividends at the center of its latest update, lifting the FY26/8 year-end payout forecast while outlining new guidance and fresh earnings estimates for FY27/8.
Ryohin Keikaku’s share price has moved sharply this year, with a 30-day share price return of 20.23% and a year to date gain of 66.42% at a latest share price of ¥4,743.0. The 5-year total shareholder return of 361.59% points to momentum that has built over a longer stretch as investors react to the latest dividend update, FY27/8 guidance and recent board decisions.
Compare the dividend move by Ryohin Keikaku with other income ideas by scanning our hand-picked 29 dividend fortresses that prioritize payouts backed by solid financial profiles.
Ryohin Keikaku now trades only about 6% below the average analyst target after a sharp rerating on its dividend update. Is that modest discount a margin of safety, or a sign that caution is finally catching up?
Preferred Multiple of 33x P/E: Is it justified?
On simple valuation math, Ryohin Keikaku is being priced at a premium. The stock trades on a P/E of 33x, which sits well above several reference points investors often look at for comfort.
The P/E ratio compares the current share price with earnings per share. For a retailer like Ryohin Keikaku, it effectively indicates how much the market is willing to pay today for each unit of profit, based on expectations around future earnings resilience, brand strength, and the consistency of cash generation.
Against that backdrop, the market is assigning Ryohin Keikaku a far richer tag than its peers. The 33x P/E is higher than the peer average of 19.2x and also above the JP Multiline Retail industry average of 15.7x. It is even above the estimated fair P/E of 21.7x, which suggests investors are paying a price that is meaningfully ahead of the level the fair ratio model points to as a possible anchor over time.
Explore the SWS fair ratio for Ryohin Keikaku.
Result: Price-to-Earnings of 33x (OVERVALUED)
Still, any stumble in earnings delivery or a shift in sentiment toward high P/E retailers could quickly challenge the premium currently attached to Ryohin Keikaku.
Find out about the key risks to this Ryohin Keikaku narrative.
Another View: What The SWS DCF Model Says About Ryohin Keikaku
A different lens tells a tougher story. The SWS DCF model puts Ryohin Keikaku’s future cash flow value at ¥2,750.86 per share, well below the recent ¥4,743. That points to an overvalued stock under this framework and raises a simple question: Are you paying tomorrow’s cash flows at today’s price?
Look into how the SWS DCF model arrives at its fair value.
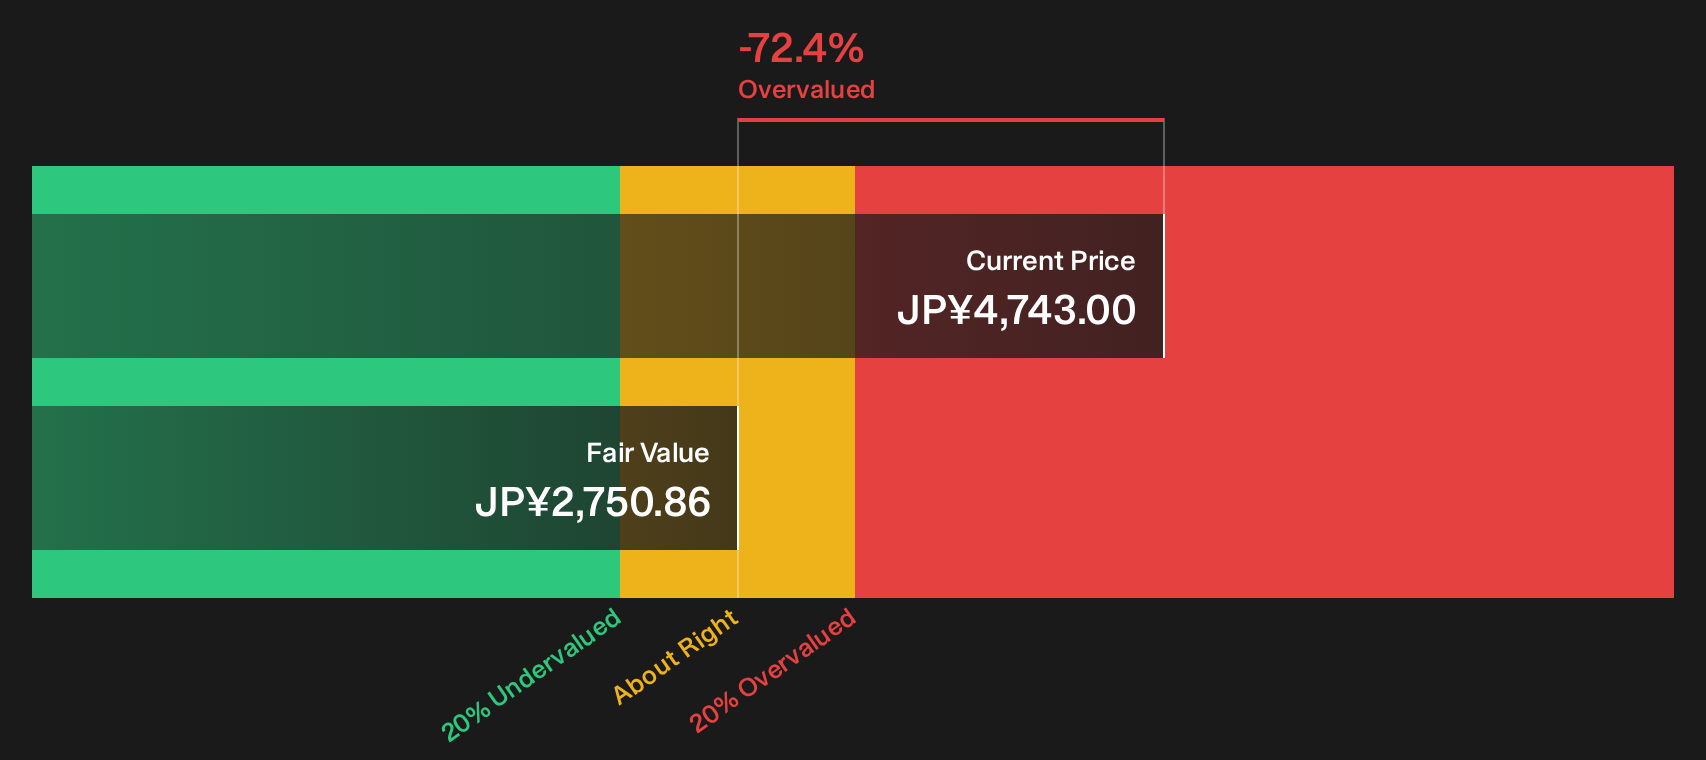
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ryohin Keikaku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seen enough of the mixed signals around Ryohin Keikaku’s valuation and dividend story for now? Act quickly by reviewing the full picture on its 2 key rewards
Looking for more investment ideas beyond Ryohin Keikaku?
Do not stop at Ryohin Keikaku. Broaden your watchlist now by testing different angles on quality, value and income so you are not reliant on a single story.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (22 results) that aim to pair financial strength with room for future growth.
- Hunt for price dislocations using the 13 high quality undervalued stocks and see which businesses currently trade below the value suggested by their fundamentals.
- Build a cash flow focused watchlist through the 29 dividend fortresses and spot payout ideas that may complement Ryohin Keikaku in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com