
Why Palomar Holdings (PLMR) Is Getting Fresh Attention Now
Palomar Holdings (PLMR) is back in focus as fresh analyst commentary highlights its pattern of beating earnings expectations and notes ongoing year over year profit gains ahead of the upcoming quarterly report.
At a share price of $137.83, Palomar Holdings has given investors a 5.66% 90 day share price return and a 19.91% total shareholder return over the past year, while the 176.29% three year total shareholder return points to strong longer term momentum building behind the story.
Scan for other insurers showing similar earnings momentum and resilience using our curated list of 32 resilient stocks with low risk scores as Palomar Holdings heads into its next results test.
After a sharp three year run and a fresh push toward analyst targets, Palomar Holdings now forces a trade off: pay up for the recent strength or wait and risk missing further rerating as the valuation case plays out next.
Most Popular Narrative: 15.5% Undervalued
Against a last close of $137.83, the most followed narrative pegs Palomar Holdings at a fair value of $163.17. This frames today’s premium rating as a bet on how the business mix shift and capital returns play out over time.
Capital management that now combines a larger share repurchase authorization and a new regular dividend with continued organic growth and acquisitions signals that Palomar Holdings is confident in its earnings power. This can support earnings per share growth and help close any gap between share price and underlying business value.
See why 27 investors see Palomar Holdings as 16% undervalued.
Result: Fair Value of $163.17 (UNDERVALUED)
Still, the Palomar Holdings story can break if higher loss ratios from crop and casualty lines bite harder than expected or if earthquake pricing pressure persists.
Find out about the key risks to this Palomar Holdings narrative.
Another View: Palomar Holdings Through The P/E Lens
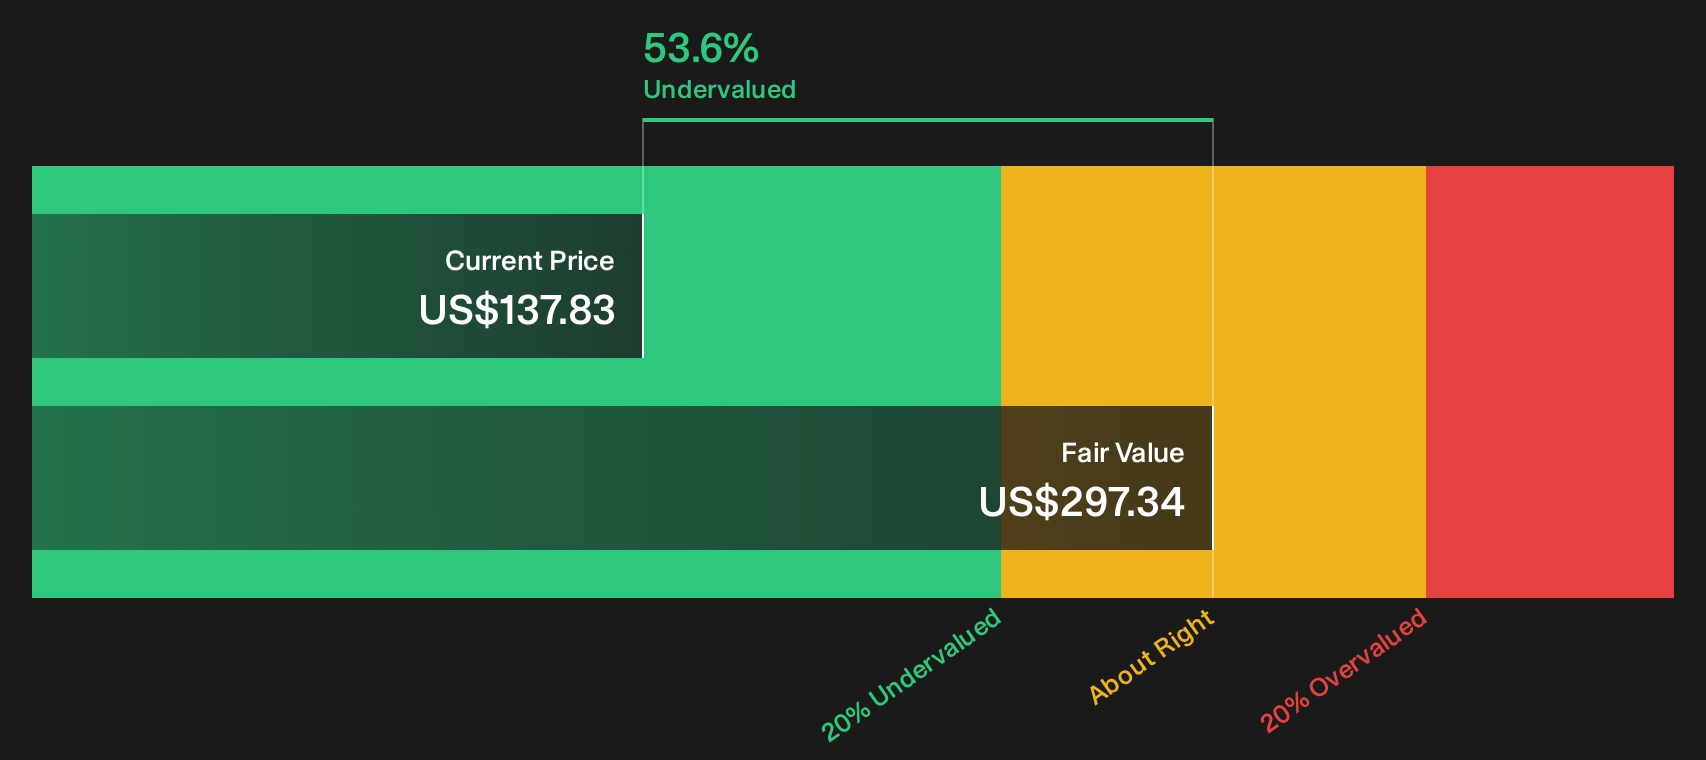
The SWS DCF model points to Palomar Holdings trading 53.6% below an estimated future cash flow value of $297.34, which supports the undervalued narrative. Yet on a simple P/E basis the stock trades on 17.9x versus a fair ratio of 12.8x and a US Insurance industry average of 11x. That mix of discount on one model and premium on another leaves a basic question for investors: which signal feels more reliable for how you value Palomar Holdings?
Our DCF work sets out the moving parts behind that cash flow view in detail, so you can judge the gap for yourself, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Plenty in this Palomar Holdings story points in different directions, so act while the data and sentiment are fresh and build your own view using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Palomar Holdings?
You have seen how one insurance story plays out. Now broaden your opportunity set and pressure test your thinking with a few focused stock idea lists.
- Target potential mispricings by scanning a curated pool of companies that screen as quality yet potentially overlooked through the 35 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses filtered for robust finances using the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by tracking financially sound prospects that are not yet widely followed through our 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com