
Should Raised Revenue Outlook Require Action From eBay (EBAY) Investors?
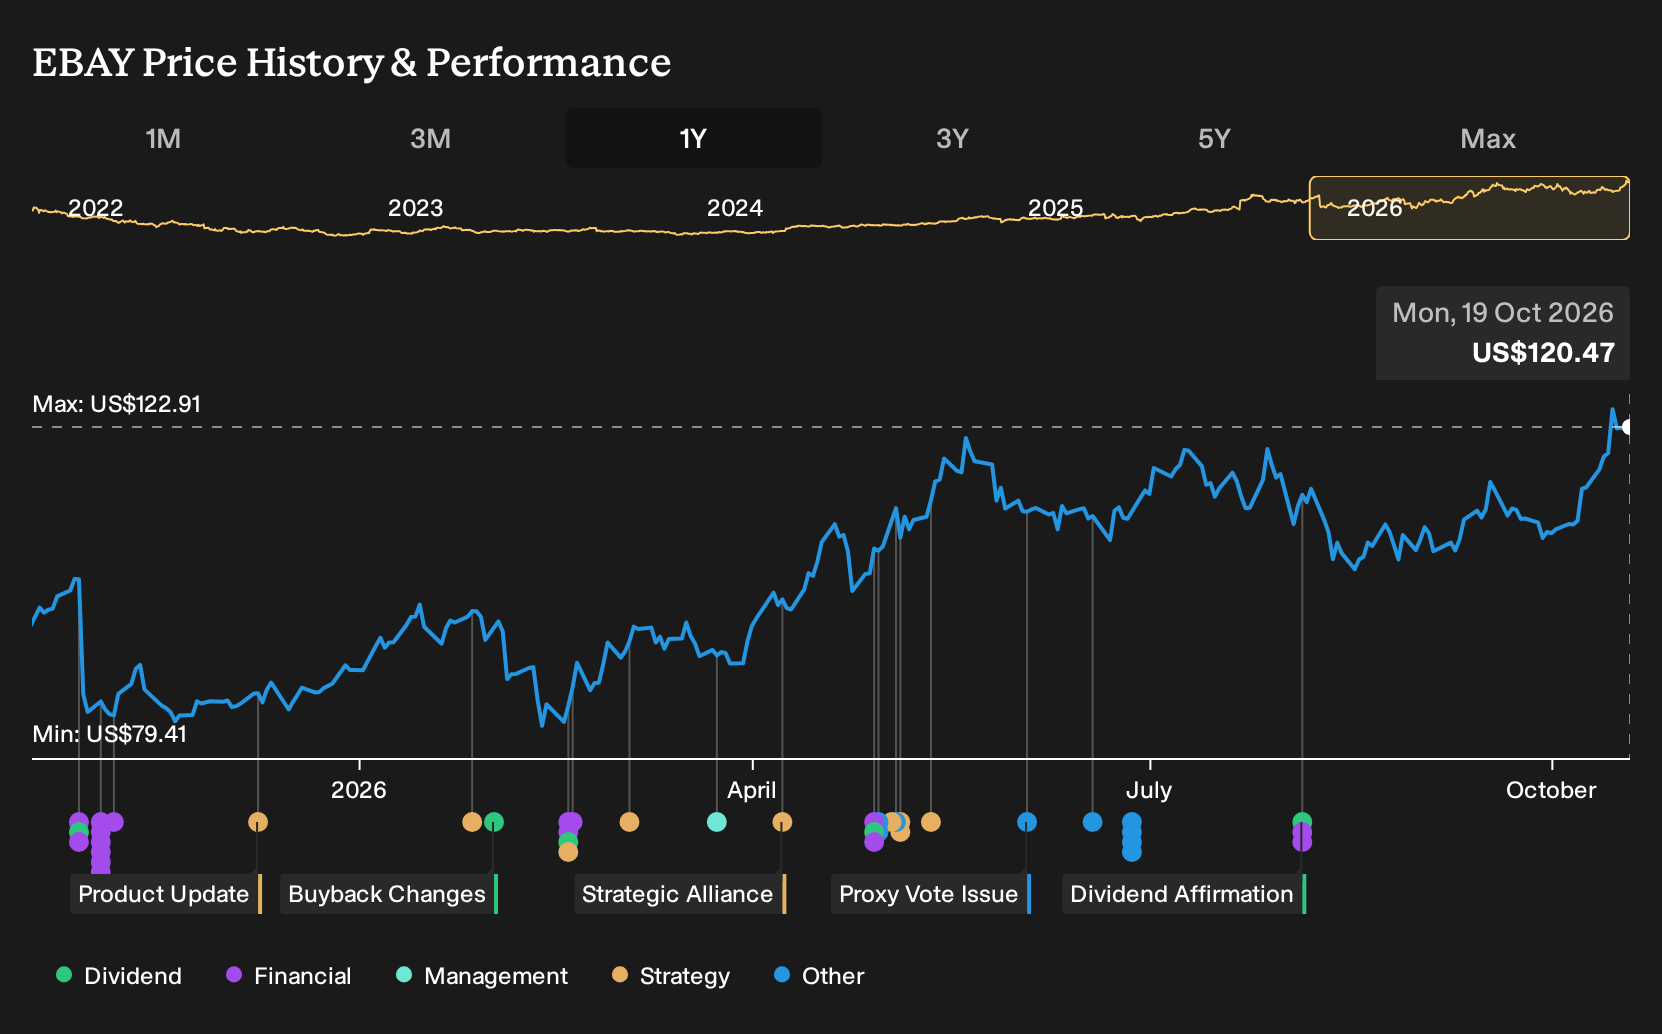
- eBay recently issued a positive update to its Q3 2026 outlook, guiding to stronger than previously expected revenue supported by demand in categories such as collectibles, motors, fashion, luxury goods, refurbished products, and consumer to consumer sales.
- The guidance raise highlights how eBay’s focus categories and recommerce mix are shaping the company’s current revenue profile rather than just its user growth story.
- We will now explore how eBay’s raised revenue outlook could reshape the existing investment narrative around focus categories and recommerce.
Scan beyond eBay and see how other resale and marketplace stocks are repositioning for recommerce momentum with our hand picked 20 high quality undiscovered gems.
eBay Investment Narrative Recap
To own eBay stock, you need to believe the marketplace can keep deepening its recommerce and focus category mix while holding together buyer trust, seller economics, and shipping protections. The raised Q3 2026 revenue outlook flags that the current operating engine is tied more to what people are buying than how many users there are. The near term swing factor is whether these higher value categories and enthusiast buyers keep transacting at similar intensity.
The biggest operational risk still sits in the cost of trust programs and the drag from Depop while it scales. Extra scrutiny on AI shopping agents and content moderation after issues on resale platforms could add compliance workload without a clear revenue offset. That appears more like incremental friction rather than a thesis-changing event, unless it meaningfully shifts transaction losses or regulatory exposure.
The most relevant development tied to this outlook is management’s work on AI and automation across listing tools and search while restricting unapproved third party AI shopping agents. Approved tools such as Magical Listings and card scanning are intended to make it easier for sellers to create more and better listings, which already coincides with higher listings per lister in some markets.
On the flip side, tighter controls on outside AI agents and closer monitoring for suspicious or stolen goods, as seen after the France riots, can raise operating complexity. For investors watching catalysts, the key question is whether eBay can keep improving convenience and discovery with its own AI stack while keeping fraud losses, shipping protection costs, and compliance obligations from eroding the margin profile that underpins the current outlook.
eBay's current analyst narrative points to US$14.8b in revenue and US$2.7b in earnings by 2029, based on forecasts for 7.1% yearly revenue growth and an earnings increase of about US$0.5b from US$2.2b today.
Uncover why eBay's fair value indicates a 4% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate angle puts eBay’s AI controls at the center of the story. The most optimistic analysts were already penciling in about US$15.7b of revenue and US$3.2b of earnings by 2029, and saw tighter rules on third party AI agents as a way to protect high margin recommerce. Those views were formed before this latest guidance, so you may want to compare them with your own expectations and consider how fresh results or policy changes could shift that bullish script.
Explore 4 other eBay fair value estimates, including one that suggests as much as 34% potential return from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your eBay research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for eBay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate eBay's overall financial health at a glance.
Looking for more investment ideas beyond eBay?
Once you have a handle on eBay, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want to focus on companies where valuation and quality metrics line up, take a look at our 35 high quality undervalued stocks that meet a higher bar on fundamentals.
- For investors who care more about balance sheet strength than big headlines, filter for businesses in our list of solid balance sheet and fundamentals (25 results) that may better match your comfort with risk.
- If income is a priority and you are hunting for yield, you can zero in on potential payers by scanning our 8 dividend fortresses that clear a 5% yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com