
Angelalign Technology (SEHK:6699) Following Patent Rulings Still Looks Cheap On Fair Value
Angelalign Technology (SEHK:6699) is back in focus after a court in Paris held that aligner systems using its Torque Ridges feature infringe Align Technology’s patent, triggering injunctions, product recalls, and damages across several European markets.
At around HK$81.1, Angelalign Technology’s 1 day share price return of 1.82% came after the court ruling. However, the 30 day share price return is down 6.30%, while a 33.17% year to date share price gain and 46.56% 1 year total shareholder return suggest earlier momentum that now faces a clear legal overhang.
Scan how Angelalign Technology fits into the wider dental and medical equipment space by comparing it against our curated list of solid balance sheet and fundamentals (202 results) for potential alternatives facing different risk profiles.
Angelalign Technology now trades well below both analyst targets and intrinsic value estimates after the legal shock. Does that gap flag opportunity, or is it simply the market pricing in unresolved patent risk?
Preferred P/E Multiple Of 43x: Is It Justified For Angelalign Technology?
At HK$81.1, Angelalign Technology trades on a P/E of 43x, which puts the shares on a much richer earnings multiple than both the Hong Kong Medical Equipment industry and its closest peers.
The P/E ratio compares the current share price with earnings per share. For a dental equipment group that is already generating net income of HK$41.0m on revenue of HK$439.6m, this benchmark indicates how much of a premium the market is willing to pay for each dollar of profit today.
That 43x P/E looks demanding when compared with the Hong Kong Medical Equipment industry average of 18.4x and a peer group average of 19.8x. It also sits above the estimated fair P/E of 18.7x, which is the level our fair ratio work suggests the valuation could gravitate toward if sentiment cools.
Explore the SWS fair ratio for Angelalign Technology.
Result: Price-to-earnings of 43x (OVERVALUED)
Still, the Paris patent ruling and ongoing exposure to international legal claims leave Angelalign Technology’s premium P/E vulnerable if outcomes move against current expectations.
Find out about the key risks to this Angelalign Technology narrative.
Another View On Angelalign Technology’s Valuation
The P/E screen presents Angelalign Technology as expensive, while the SWS DCF model suggests a different picture. On that cash flow view, the shares at HK$81.1 trade about 39.8% below an estimated value of HK$134.78. Is the market discounting legal risk too heavily, or is the model too optimistic?
Look into how the SWS DCF model arrives at its fair value.
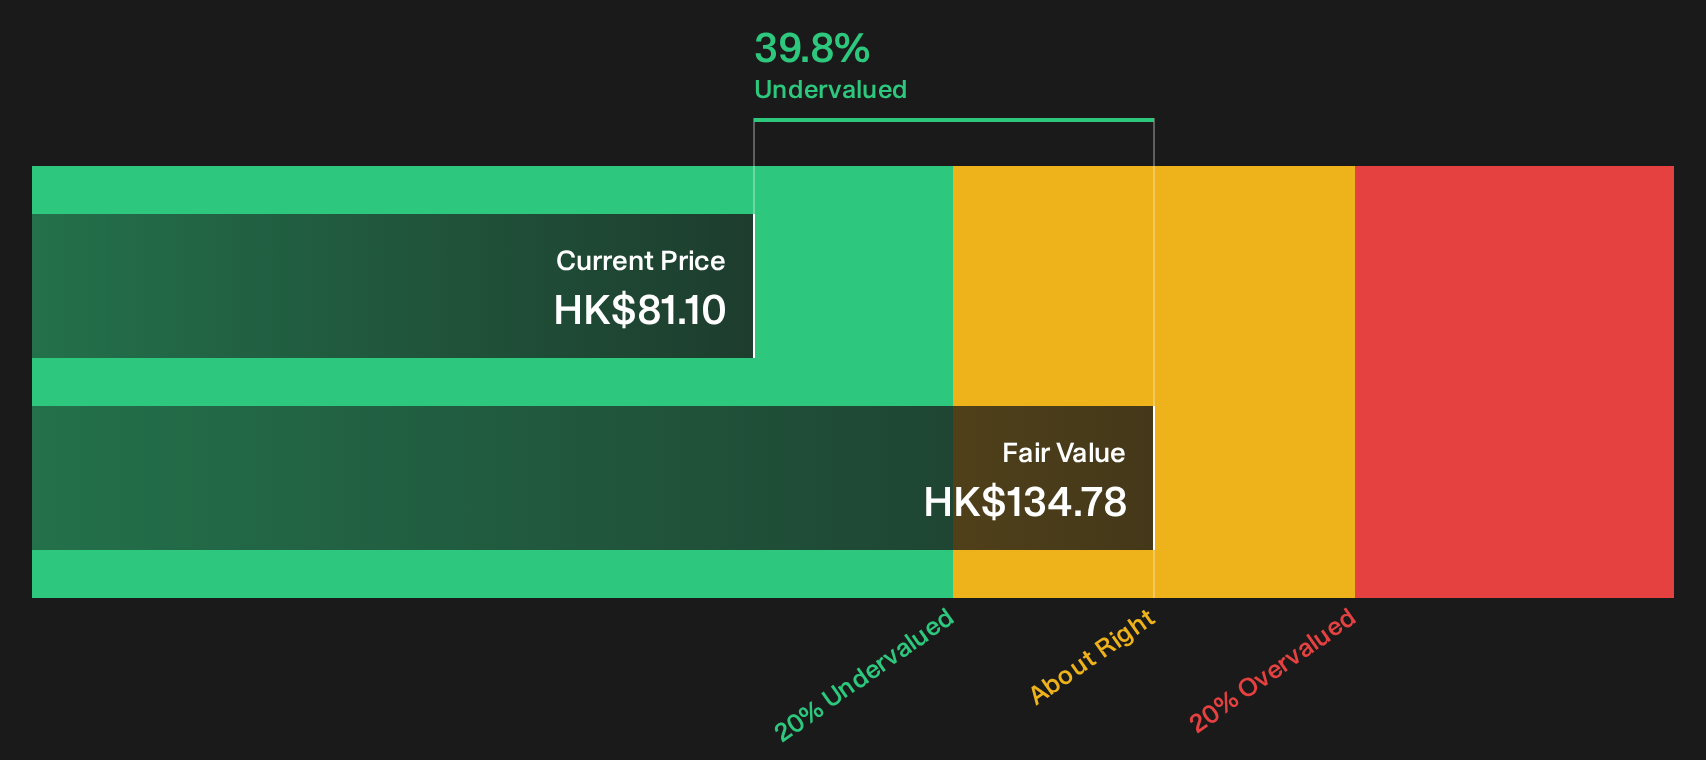
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Angelalign Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Angelalign Technology’s valuation and legal risk make this a stock you need to scrutinize directly and decide where you stand, starting with its 4 key rewards and 2 important warning signs.
Looking For More Angelalign Technology Investment Ideas?
If Angelalign Technology has your attention, do not stop here. Cast a wider net and use structured stock lists to stress test your next move.
- Target value opportunities by scanning companies flagged in our 192 high quality undervalued stocks. These pair compressed valuations with stronger fundamentals than the market currently prices in.
- Prioritise resilience and sleep better at night by filtering for businesses in the 229 resilient stocks with low risk scores. These carry more measured risk profiles.
- Hunt early for tomorrow's potential leaders by reviewing the 615 high quality undiscovered gems before attention and pricing catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com