
Shochiku (TSE:9601) Just Gave Investors Something To Think About
Shochiku (TSE:9601) has just reported fresh numbers, with half-year sales of ¥48,921 million, net income of ¥736 million, and basic earnings per share of ¥53.6.
The half-year figures landed alongside a sharp rebound in Shochiku’s share price, with a 7-day share price return of 8.27% and a 30-day gain of 8.07% from a latest close of ¥11,780. That short-term momentum contrasts with a year-to-date share price decline of 1.50% and a 1-year total shareholder return that is down 10.04%, even though the 3-year total shareholder return sits at 29.66%. This suggests sentiment has recently improved after a weaker stretch.
Compare Shochiku’s post-earnings swing with a handpicked 73 high quality undiscovered gems that could be reacting to similar catalysts across the market.
Shochiku’s recent bounce has reset expectations in a hurry. After that move and the mixed return profile, does the current price still offer more upside potential than downside risk for new buyers?
Preferred P/E of 87.4x: Is it justified?
Shochiku now trades at a P/E of 87.4x based on the latest figures, while the last close sits at ¥11,780, which points to a rich valuation compared with both its own earnings profile and peers.
The P/E multiple compares the current share price with per share earnings. For a media and entertainment group like Shochiku, it reflects what investors are willing to pay today for each ¥1 of current profit.
That willingness is high. The stock is described as expensive versus the JP Entertainment industry average P/E of 17x and also versus the peer average of 20.4x. Against an estimated fair P/E of 26.2x, the current level looks even more stretched and implies the market is attaching a much steeper price to forecast earnings than the fair ratio suggests.
Based on that comparison, the current P/E multiple is described as materially higher than both the sector and the fair ratio level that the market could move towards over time.
Explore the SWS fair ratio for Shochiku.
Result: Price-to-earnings of 87.4x (OVERVALUED)
Still, the Shochiku story could be knocked off course if its earnings growth slows or if domestic theatre and video spending softens from current levels.
Find out about the key risks to this Shochiku narrative.
Another view on Shochiku’s valuation
A different lens, the SWS DCF model, points in the opposite direction. On this approach, Shochiku at ¥11,780 is trading well above an estimated future cash flow value of ¥4,127.97, which screens as overvalued on cash flows rather than earnings. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
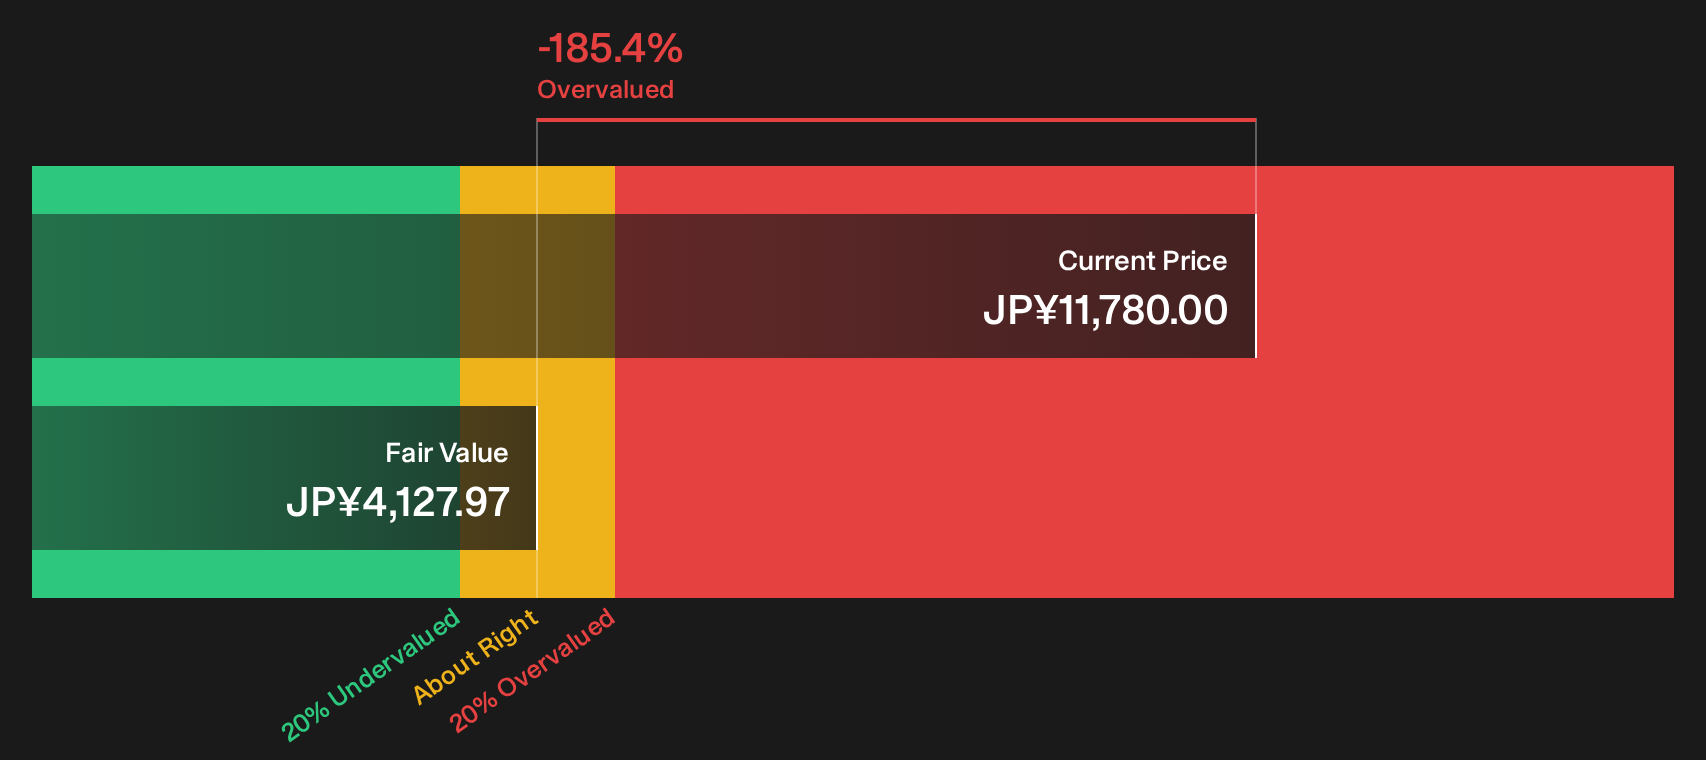
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shochiku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Shochiku’s mixed signals on valuation, risks, and rewards make this a judgment call. Move quickly from headline impressions to your own assessment, starting with the 1 key reward and 3 important warning signs in the 1 key reward and 3 important warning signs.
Hunting for more ideas beyond Shochiku?
If Shochiku has sharpened your focus on valuation and risk, do not stop here. Broader idea generation can help you build a stronger overall portfolio mix.
- Target potential mispricing by reviewing a 13 high quality undervalued stocks that filters for companies combining quality fundamentals with pricing that screens as attractive.
- Strengthen income potential by scanning a 29 dividend fortresses aimed at businesses offering higher yields with a focus on stability.
- Dial down portfolio stress by checking a 21 resilient stocks with low risk scores focused on companies that score well on risk controls and resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com