
Green Plains (GPRE) Stock Could Be A Bargain On Its 62% Slump
Green Plains has had a mixed share price record over the past few years, so the key issue now is whether the current valuation is still grounded in what the company earns. Recent policy support for low carbon fuels and new business initiatives have put fresh attention on the stock, which puts its earnings power under the microscope.
- Over the past 5 years the share price has fallen 61.5%, which puts a lot of weight on the question of whether today's earnings justify even the current lower level.
- Recent earnings commentary highlighted meaningful EBITDA contribution from low carbon ethanol and related credits, which can influence how durable investors think Green Plains' margins and cash generation may be.
- The analysts covering Green Plains have run their own numbers. See what analysts think Green Plains's shares could be worth.
The stock's next move may depend on whether Green Plains' current price is in line with what its earnings suggest investors are paying for.
If you want to test the same earnings question that Green Plains faces against a wider field of potential ideas, take a look at 35 high quality undervalued stocks.
Is Green Plains a Bargain on Earnings?
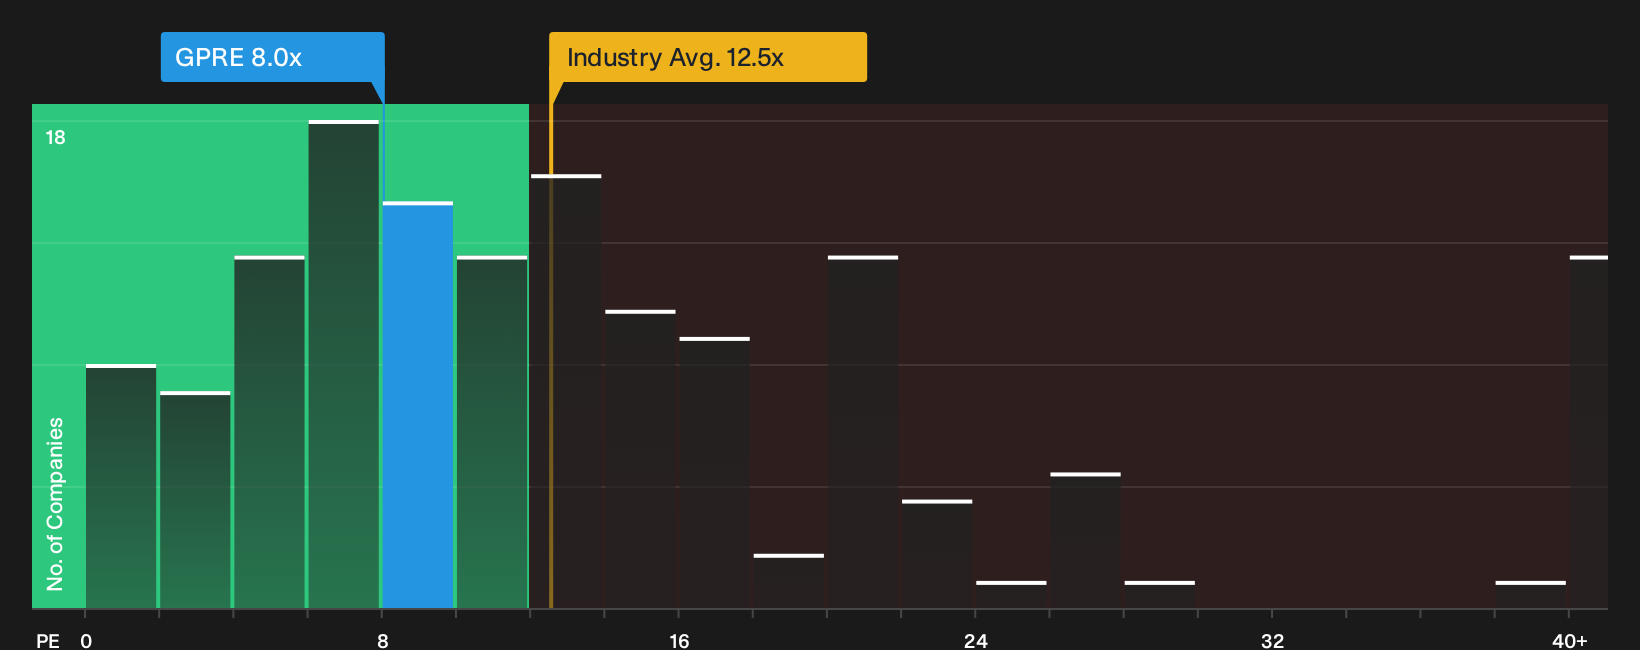
P/E fits Green Plains because investors are focused on how consistently its earnings can convert into cash flows. On this measure, Green Plains trades at roughly 8.0x earnings, compared with an Oil and Gas sector average near 12.5x and a peer group closer to 11.1x. That places the stock at a visible discount to both the wider industry and more direct comparables.
Based on the fair multiple that reflects Green Plains' own growth profile, profitability and risk, the current 8.0x P/E sits below where the model would place it. This indicates that the shares screen as undervalued on this metric. Because the recent EPA move has supported sentiment toward ethanol producers, yet the P/E still sits below these benchmarks, the market appears to be pricing in more caution than the earnings multiple alone might suggest. Explore the numbers behind Green Plains's P/E valuation.
The Green Plains Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/E puzzle leaves off for Green Plains. They spell out which expectations on future growth, margins and earnings would need to hold for the shares to look meaningfully higher or lower than today. Rather than stopping at a single multiple or model output, each one lays out the assumptions that sit behind its view of fair value, so you can compare those inputs with actual results as they come through. These sit on Simply Wall St's Community page for readers who want that extra layer of context.
One of the top community narratives on Green Plains: 20% undervalued
Extension and enhancement of government incentives, specifically the confirmation and expansion of the 45Z clean fuel production tax credit through 2029, position Green Plains to significantly increase recurring revenues and EBITDA from low-carbon ethanol production…
Discover why this Narrative puts Green Plains at 20% undervalued.
One more Green Plains clue before you decide what to do next
There is a whole other angle on Green Plains that sits outside its current P/E, which is where professional analysts think the business might be a few years from now, and how that compares with today's share price. Explore where analysts expect Green Plains to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com