
Snap (SNAP) Stock Could Be Undervalued Despite Specs Stake Sale Push
Snap Inc. has had a rough ride over the past few years, and with fresh attention on its augmented reality push, the real question now is whether the current share price lines up with what its sales can reasonably support.
- Snap shares are down 88.5% over 5 years, which puts a lot of weight on whether the underlying revenue base can carry the valuation that remains.
- The recent call from Blue Duck Capital Partners to raise about US$1b by selling a minority stake in the Specs AR unit may shift how investors think about funding needs and future revenue from that side of the business.
- The analysts covering Snap have run their own numbers. See what analysts think Snap's shares could be worth.
For investors, the debate is whether Snap's current share price is justified by the sales it is already generating and what those sales suggest about future potential.
If you are weighing Snap against other ways to play this theme, a focused stock screen can be a useful second lens, starting with 39 AI small caps.
Is Snap Still Cheap on Sales?
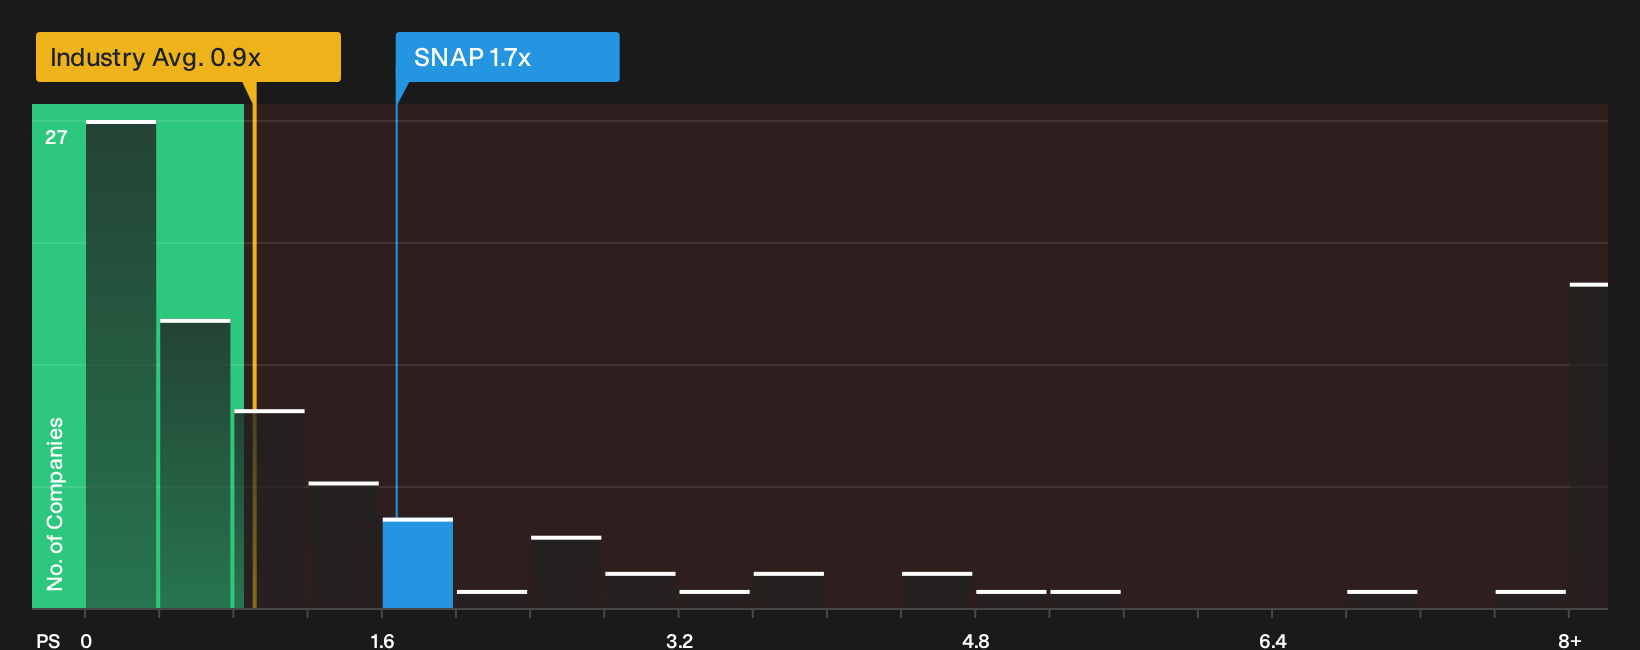
P/S fits Snap because revenue is still the cleanest yardstick for a business that has focused more on building its user and ad base than on consistent profits. On that metric, the stock trades on a P/S of 1.7x, which is below both the broader Interactive Media and Services industry on 0.9x and the closer peer group on 2.2x.
That gap sits below what a tailored fair multiple model suggests for Snap, which points to the shares screening as undervalued on sales relative to the company’s own profile. Because the recent AR push and the proposed Specs stake sale have lifted interest in the story, the current discount on P/S means sentiment has firmed while the price still tags the business below what comparable firms command on this measure. Explore the numbers behind Snap's P/S valuation.
The Snap Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Snap pick up where this valuation puzzle leaves off. They set out what kind of future path on growth, margins and earnings would need to play out for the shares to look materially higher or lower than today’s price, based on scenarios you can find on the Community page. Each idea links its figure to a clear view on how Snap's expansion, profitability and risk profile might evolve, which you can revisit as fresh information lands.
Community views on Snap split between investors who see the AR and subscription push as underappreciated and others who think advertising and engagement risks still loom large.
Bull case: 14% undervalued
"Monetization progress in subscription products such as Snapchat+ and Lens+, alongside growing engagement with Spotlight and creator-driven content, is diversifying Snap's revenue base..."
Discover why this Narrative puts Snap at 14% undervalued.
Bear case: 25% overvalued
"Snap faces the risk of long-term user stagnation or decline as younger generations shift their attention to emerging niche or decentralized platforms..."
Explore why this Narrative puts Snap at 25% overvalued.
One more thing about Snap that deserves a closer look
Price and sales only tell part of the story for Snap, since internal checks have also highlighted specific concerns that some investors may want to weigh before getting comfortable with the risk profile. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com