
Enbridge (TSX:ENB) Stock Could Be Priced Richly As Pipeline Volumes Draw Focus
Enbridge has delivered a powerful run over the past few years, and the question now is whether the current share price still lines up with what its earnings can support. With the stock recently closing at C$66.59, investors are asking if they are paying a fair price for the cash flows this pipeline and gas utility group produces.
- Over the past 3 years the stock has returned about 82.5%, which puts a lot of weight on the idea that Enbridge's earnings story can justify that kind of climb.
- Recent coverage has focused on pipeline throughput, regulated cash flows, financing costs and dividend coverage. Each of these factors can influence how dependable the company's earnings base appears and how investors think about what multiple to apply to it.
- The analysts covering Enbridge have run their own numbers. See what analysts think Enbridge's shares could be worth.
The issue now is whether Enbridge's current price fairly reflects what its earnings suggest the stock should be worth.
If you are weighing whether Enbridge's earnings justify its current price, it can help to compare that question across 5 high quality undervalued stocks.
Has Enbridge Run Too Far on Earnings?
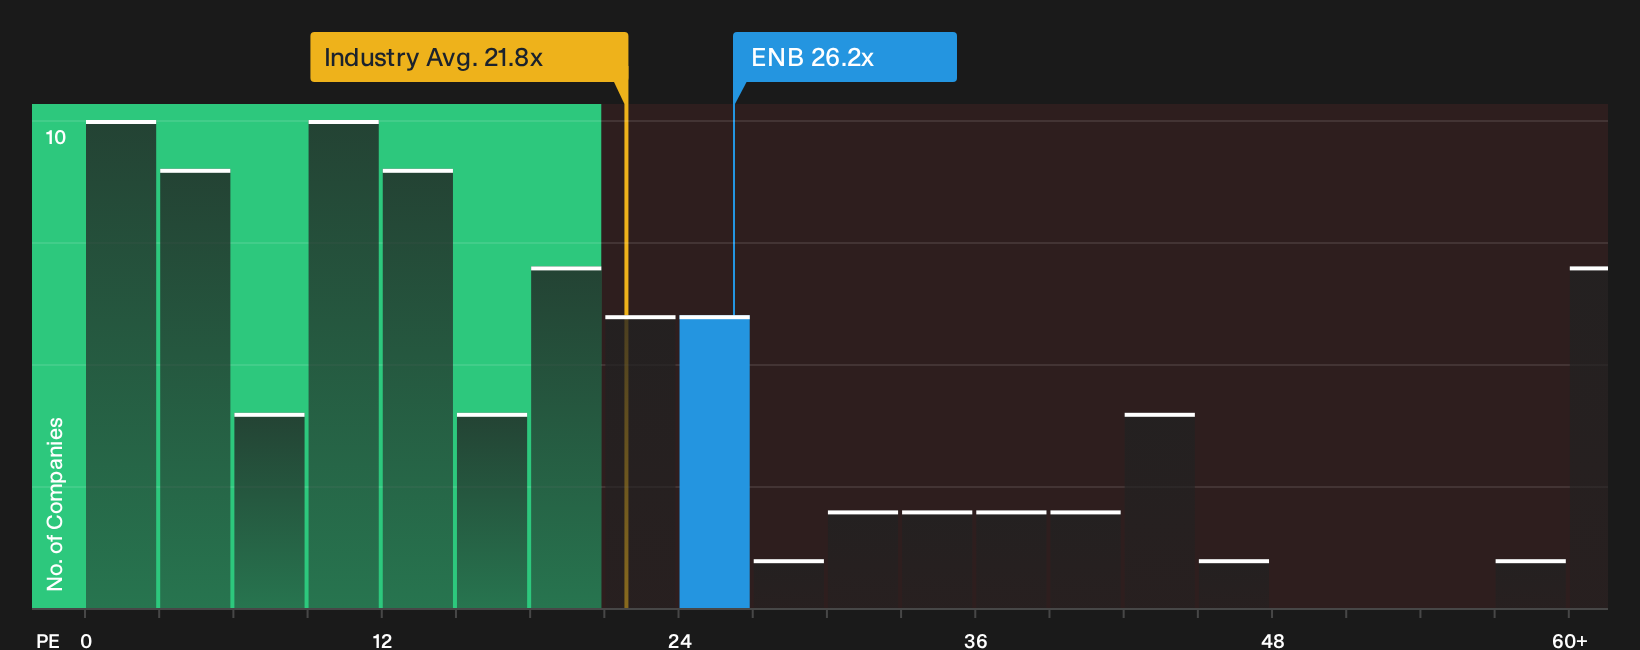
The P/E ratio works well for Enbridge because earnings drive much of the debate around how durable its pipeline and utility cash flows really are. On this lens, the stock trades on about 26.2x earnings, a touch below the peer group average of roughly 27.3x but above the broader Oil and Gas sector at about 21.8x.
Because the recent rally has drawn attention to factors like pipeline volumes and financing costs, that premium to the sector suggests investors are still willing to pay up for Enbridge's earnings profile. The current P/E sits above the level suggested by a tailored fair multiple that takes the business mix and risk profile into account, so on this framework the shares screen overvalued. Because recent coverage highlights upcoming indicators such as project commissioning and debt metrics, the present valuation already bakes in a lot of confidence that these will track expectations. Explore the numbers behind Enbridge's P/E valuation.
The Enbridge Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Enbridge leaves off by outlining what would need to occur in future growth, profitability and earnings for the stock to be worth materially more or less than it trades for today on the Community page. Rather than relying on a single multiple or model point estimate, each narrative details the assumptions that drive its view of Enbridge's worth so you can track those inputs as actual results are reported.
Community views on Enbridge pull in opposite directions, with one side leaning into the project backlog and the other focused on valuation discipline.
Bull case: 16% undervalued
"Enbridge is positioned to use its approximately $41b secured growth backlog and roughly $50b identified organic opportunity set through 2030 to add new regulated and contracted assets..."
Discover why this Narrative puts Enbridge at 16% undervalued.
Bear case: 42% overvalued
"The recommendation is to HOLD because it is a quality business with solid fundamentals, but the limited margin of safety suggests a better entry point would be below $40..."
Explore why this Narrative puts Enbridge at 42% overvalued.
The Enbridge share price is only one piece of your decision
Valuation tells you what the market is paying today. The next question is how professional analysts see Enbridge a few years down the road and how that stacks up against this price. Explore where analysts expect Enbridge to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com