
Sterling Infrastructure (STRL) Stock Looks Reasonable As Its 17x Five Year Run Continues
Sterling Infrastructure has delivered very strong long term gains, yet the share price has recently pulled back, which raises a simple question for you as an investor. Is the current valuation still supported by the company’s earnings power, or has the stock moved ahead of what its profit base can justify?
- Over the past 5 years, Sterling Infrastructure has returned about 17x, which puts a lot of weight on whether its earnings profile is strong enough to support that kind of rerating.
- The business model is tightly tied to construction and infrastructure projects, so future earnings can depend heavily on how consistently Sterling converts its order book and work pipeline into profit and cash flow.
- Your read on Sterling Infrastructure is one view; the desks covering it have another. See what analysts think Sterling Infrastructure's shares could be worth.
The stock’s next move may depend on whether Sterling Infrastructure’s current price looks well aligned with what its earnings justify today and what they may reasonably support over time.
If you want more ideas built around earnings strength rather than share price moves, a focused stock screen is a clean starting point, especially with tools like 32 resilient stocks with low risk scores.
Is Sterling Infrastructure a Bargain on Earnings?
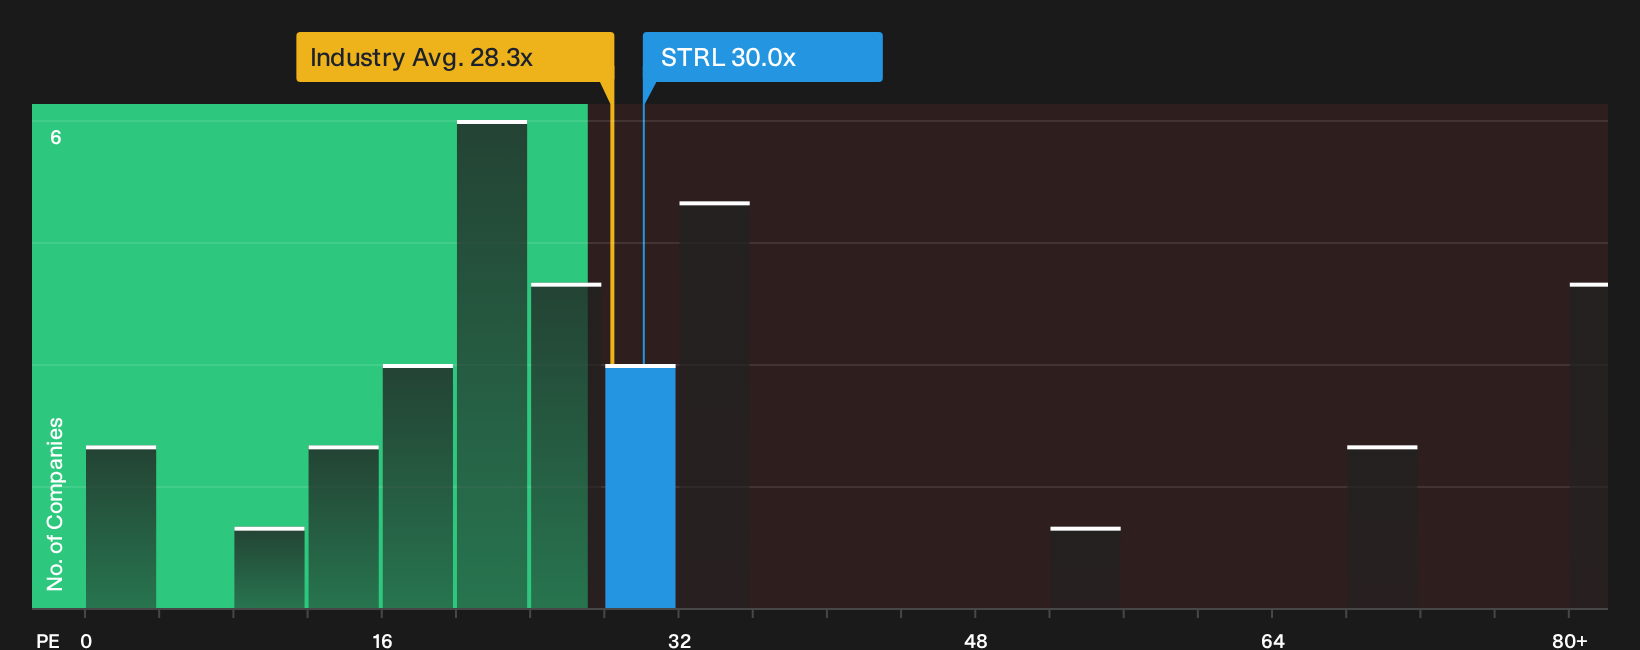
The P/E ratio suits Sterling Infrastructure because the market is clearly keying off earnings. The stock trades on about 30.0x earnings, compared with roughly 28.3x for the wider construction sector and about 27.2x across direct peers, so buyers are paying a visible premium for each dollar of profit today.
The fair P/E that would be expected once Sterling Infrastructure’s growth profile, profitability, size and risk are blended together comes out lower than where the shares change hands. On this framework the stock looks undervalued rather than stretched. That signal suggests the company’s earnings power and risk mix could justify a richer multiple than the broad benchmarks alone imply. It is therefore worth checking how that fair value line is built before leaning too hard on the headline P/E. Explore the numbers behind Sterling Infrastructure's P/E valuation.
The Sterling Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Sterling Infrastructure valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to occur for the stock to be worth significantly more or less than today’s price and sit on the Community page. Each scenario ties a fair value to a particular mix of potential catalysts and risks so you can track which storyline is actually unfolding over time.
One of the top community narratives on Sterling Infrastructure: 49% undervalued
"Sterling Infrastructure’s multi year pool of signed backlog and high probability future phase work now exceeds US$7b, heavily weighted to mission critical data center and semiconductor projects…"
Discover why this Narrative puts Sterling Infrastructure at 49% undervalued.
One more Sterling Infrastructure check before you log off
Price and current earnings only tell part of the story, because professional analysts also publish their own multi year roadmaps for where this business could be a few years from now, which gives you another reference point to compare against today. Explore where analysts expect Sterling Infrastructure to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com