
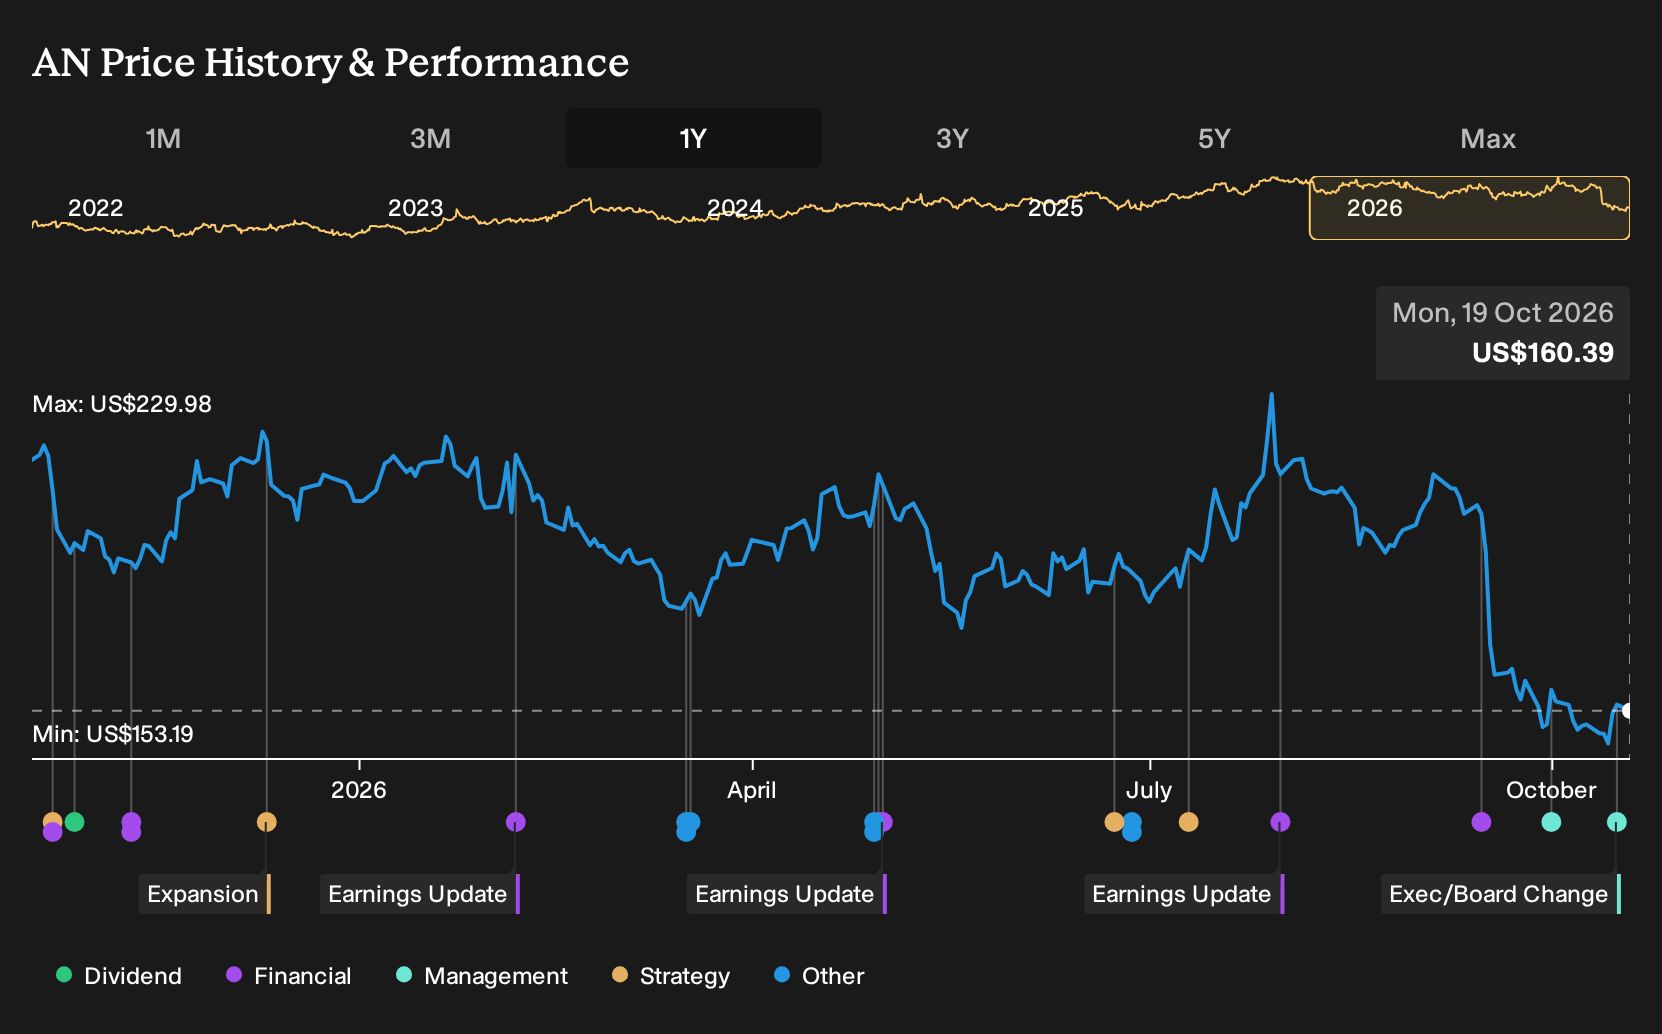
Did Board Appointment Just Shift AutoNation (AN) Investment Narrative?
- AutoNation appointed Mark Stewart, current CEO and President of Goodyear and former Stellantis North America COO, as an independent director effective October 13, 2026, expanding the board to ten members.
- Stewart’s mix of automotive manufacturing, large scale retail operations, and Amazon rooted logistics experience adds operational depth that directly connects to AutoNation’s focus on execution in higher margin aftersales and customer finance.
- We will look at how AutoNation's investment narrative is influenced by adding Mark Stewart's operational expertise to the board.
Scan how AutoNation’s board refresh compares with other operators facing similar execution questions by zeroing in on list of solid balance sheet and fundamentals (25 results) in the auto and retail universe.
AutoNation Investment Narrative Recap
For AutoNation, the simple view is that most of the value sits in dependable aftersales and customer finance rather than in volatile new car margins. The short term story centers on steady execution in service bays and continued traction in AutoNation Finance, with recent earnings growth outpacing the wider Specialty Retail industry. The appointment of Mark Stewart to the board does not, on its own, change these near term drivers.
The biggest operational risk is that parts and service growth slows or that regulatory pressure on dealer practices forces changes that dilute high margin products. Pressure on battery electric vehicle demand already affects premium luxury volume. Stewart’s background in large scale operations and customer fulfillment adds experience in these operational and compliance intensive areas, but the core exposures remain.
The recent appointment of Mark Stewart as an independent director appears most relevant for how AutoNation manages scale, automation and logistics in service and finance. His experience spans Goodyear, Stellantis North America, Amazon and multiple auto suppliers across the US, Europe and Asia. That breadth gives the board direct insight into managing large workforces, complex supply chains and customer fulfillment networks.
For shareholders, the link to potential catalysts is practical. Aftersales already contributes roughly 80% of profit, and AutoNation Finance reports about US$2.67 billion of loans with 18% penetration of financed sales. Oversight from someone accustomed to running a US$90 billion operation may help the board scrutinize credit processes, technology investment and cost control, all of which matter for protecting margins and managing the existing debt load.
AutoNation's current analyst script points to revenues of US$29.9 billion and earnings of US$807.3 million by 2029. That profile rests on revenue growing at 2.9% per year and requires an earnings increase of about US$32.6 million from US$774.7 million today.
Uncover why AutoNation's fair value indicates a 38% potential upside to its current price and a valuation gap that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into one idea. They expect AutoNation’s revenue to reach about US$31.6b and earnings of roughly US$881.5m by 2029, assuming 4.8% annual revenue growth and steady 2.8% margins. You may see Mark Stewart’s appointment and wonder if those upbeat forecasts now go even further or start to be questioned.
Explore another AutoNation fair value estimate, including one that suggests potential upside of up to 100% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd. Consider your own research and judgment.
- A great starting point for your AutoNation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking for more AutoNation style investment ideas?
If the AutoNation story has sharpened your sense of what matters in execution, balance sheets and cash generation, you can cast the net wider with the Simply Wall St Screener and compare it with other businesses that fit your approach.
- For investors who care most about valuation support and financial resilience, start with a curated set of companies that screen as both attractively priced and fundamentally strong via 35 high quality undervalued stocks.
- If predictable cash flows and balance sheet strength sit at the top of your checklist, you can line up AutoNation next to a diversified 32 resilient stocks with low risk scores to see how its risk profile compares.
- When you want fresher stories with solid numbers rather than crowded trades, broaden your watchlist with a focused pool of 20 high quality undiscovered gems that share similar quality traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com