
NVR (NVR) Draws Fresh Valuation Focus, Is The Stock Cheap Or Pricey?
Recent selling activity in the Invesco S&P 500 Equal Weight ETF, which trimmed its NVR (NVR) holdings by 60 shares worth about US$0.4 million, has drawn fresh attention to the homebuilder’s stock.
Against that ETF selling, NVR’s share price of US$5,828 sits after a choppy stretch, with the stock down about 5% on a 30-day share price basis and about 20% lower year to date, while the 5-year total shareholder return of roughly 19% points to more muted long-run momentum.
Scan how NVR compares with other housing and construction plays that have been filtered for quality and valuation across our 35 high quality undervalued stocks.
NVR has slipped on softer sentiment just as analyst targets and intrinsic value estimates sit above the current quote. Is this gap a pricing error, or a fair read on the risk?
Most Popular Narrative: 55% Overvalued
On Esteban’s framework, NVR’s fair value of $3,758 sits well below the last close at $5,828. This frames the current slide as a valuation compression rather than an outright collapse in the business story.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model: NVR pays non-refundable deposits of approximately 10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land, NVR redeploys into share buybacks. The risk that peers absorb in housing downturns, NVR walks away from by forfeiting deposits.
See why 6 investors see NVR as 55% overvalued.
Result: Fair Value of $3,758 (OVERVALUED)
Still, the NVR narrative could crack if housing demand softens more than expected, or if peers successfully copy the lot option model and pressure margins.
Find out about the key risks to this NVR narrative.
Another View: Our DCF Model Sees NVR Differently
Esteban’s narrative pins NVR at a fair value of $3,758, which frames the current share price as rich. Our DCF model pulls in the opposite direction. On that approach, NVR at $5,828 screens as undervalued against an estimated future cash flow value of $7,153.78.
Two tools, one ticker, and a wide gap between $3,758 and $7,153.78. Which lens do you trust more when cash flows indicate undervaluation, while a narrative framework suggests overvaluation?
Look into how the SWS DCF model arrives at its fair value.
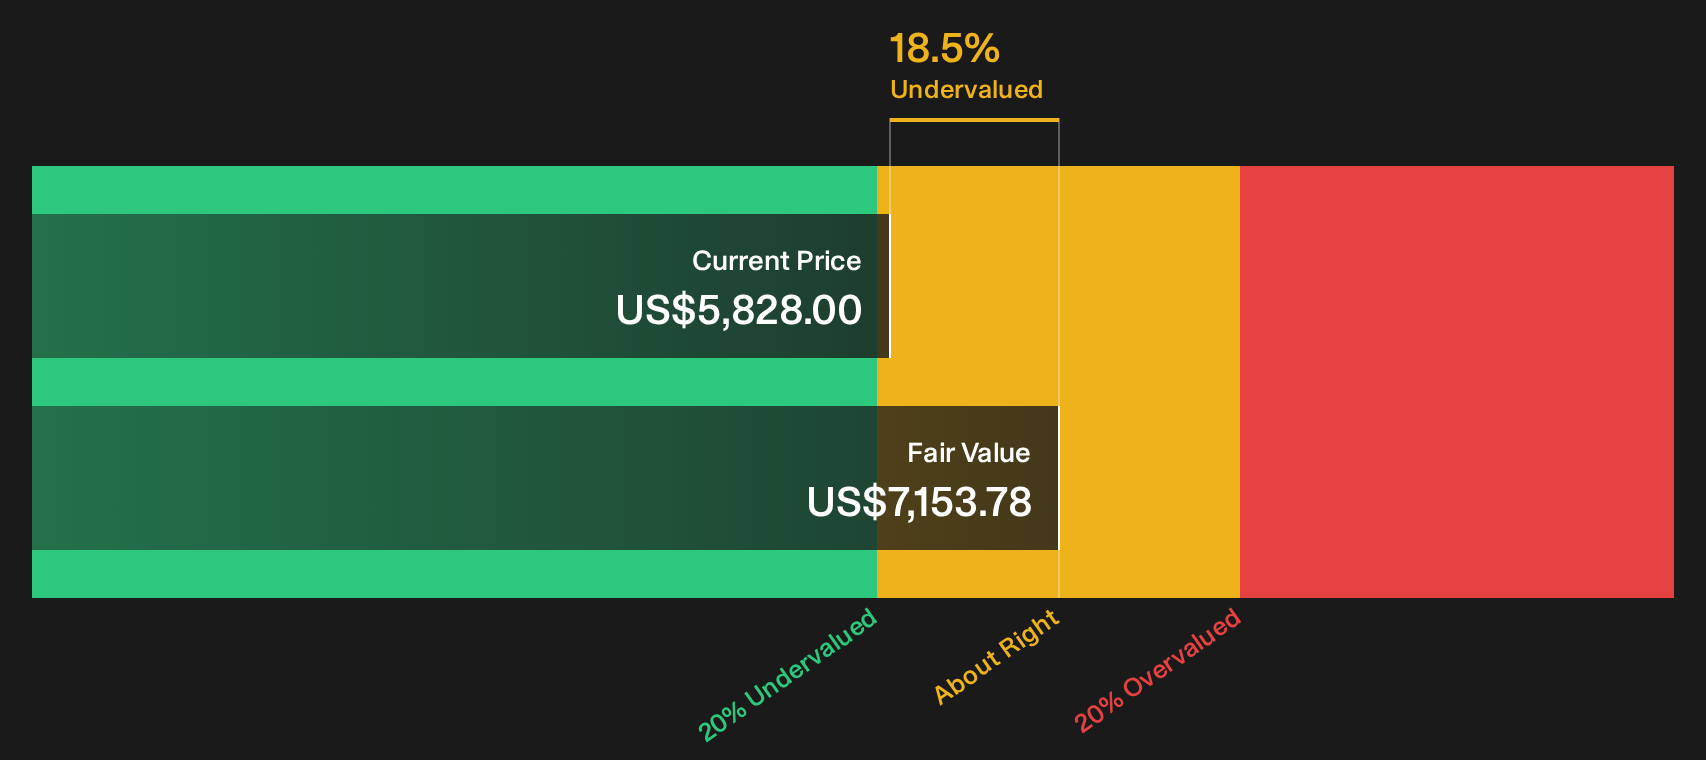
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Torn between NVR’s cash flow math and the bearish narrative on valuation compression? You probably should not wait on someone else’s verdict. Weigh the trade off between upside potential and downside risk by digging into the 1 key reward and 1 important warning sign.
Looking for more NVR investment ideas?
If NVR has your attention, do not stop with a single ticker. Broaden your watchlist using focused stock lists built to spotlight different types of opportunities.
- Target potential mispricings across the market by reviewing companies that currently screen as attractively valued through the 35 high quality undervalued stocks.
- Strengthen your search for reliability by scanning a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching their finances.
- Hunt for under-the-radar opportunities by checking a curated set of 20 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com