
Freshpet (FRPT) Could Be 22% Undervalued As Its Growth Narrative Holds
Freshpet (FRPT) has drawn investor attention after recent share price moves, with the stock last closing at US$66.12. The pet food producer now carries a market value of about US$3.2b.
Freshpet’s recent pullback of about 0.8% on the day comes after a much stronger run, with a 30-day share price return of 7.6% and a 90-day gain of 12.8%. This hints that momentum has been building even as longer term total shareholder returns over five years remain sharply negative.
Scan how Freshpet’s recent momentum compares to other companies by reviewing a handpicked group of 35 high quality undervalued stocks that currently pair quality fundamentals with discounted market expectations.
Freshpet’s share price has bounced over the past year, even though longer term holders still sit on deep losses. Is this latest shift tracking the business, or simply a reset in sentiment that the valuation will have to justify next?
Most Popular Narrative: 21.5% Undervalued
At a last close of $66.12, the most followed valuation story around Freshpet anchors on a fair value estimate of $84.25, which frames the recent share price strength as still leaving a sizeable gap to that narrative mark.
Brand loyalty and the emphasis on high value MVP households that previously showed MVPs at about 70% of sales now align with 2.5 million MVP households representing 71% of revenue and spending about 5x the average consumer, which can lift revenue and support margin stability as this group grows within the 36 million household opportunity.
See why 13 investors see Freshpet as 22% undervalued.
Result: Fair Value of $84.25 (UNDERVALUED)
Still, the Freshpet story breaks if household adoption stalls further, or if rising logistics expenses keep pressuring margins and limit the appeal of current assumptions.
Find out about the key risks to this Freshpet narrative.
Another View: Freshpet Through The P/E Lens
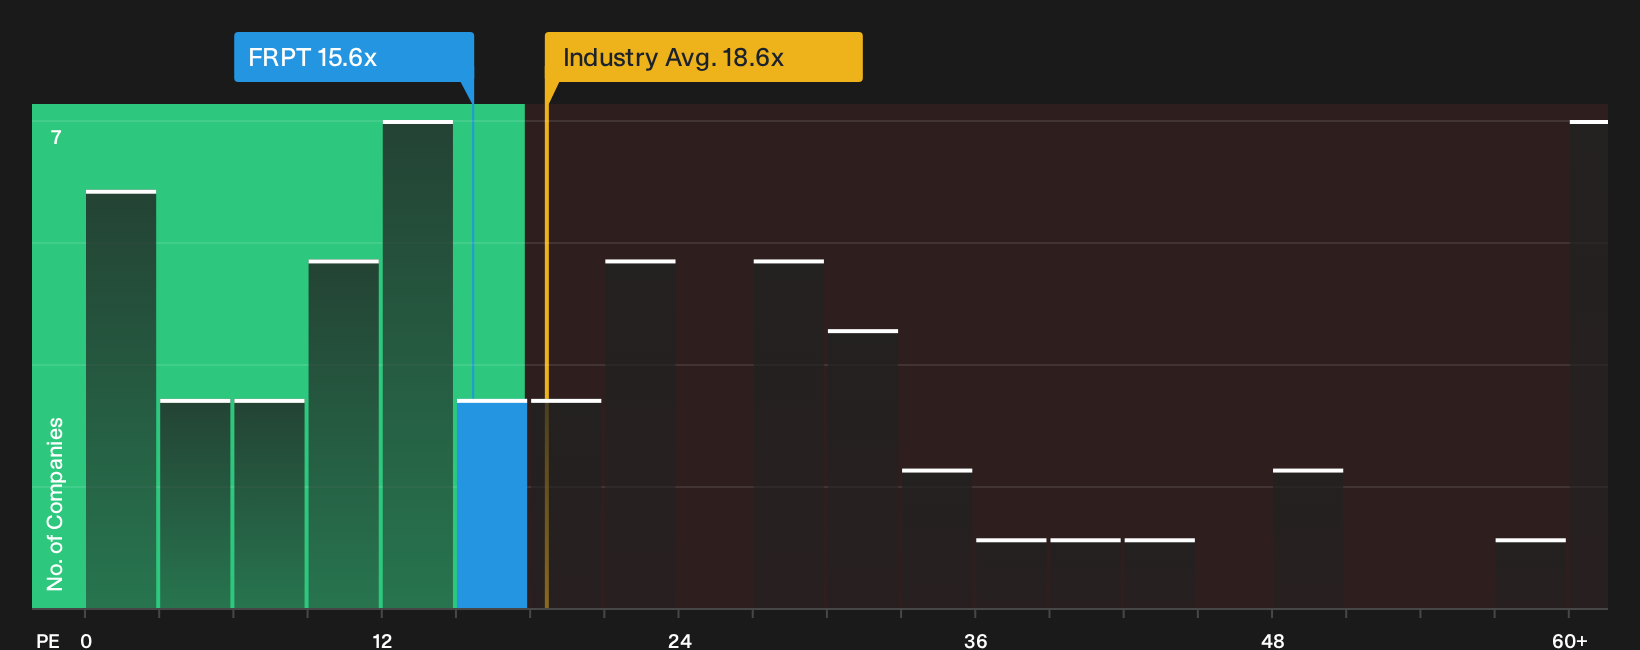
Freshpet looks very different when you move away from fair value estimates and focus on the simple P/E ratio. The shares trade on 15.6x earnings, which is below both the US Food industry at 18.7x and a peer average of 26.3x, yet still above a fair ratio of 12.1x that the market could move toward over time.
That mix of cheaper pricing than many rivals but a premium to the fair ratio means investors face a real choice. Is the current multiple a reasonable price for quality, or an indication of extra valuation risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or emerging opportunity? If you want to move past the headline valuations and sentiment snapshots and weigh both the downside and upside yourself, start by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Freshpet?
If you rely only on Freshpet, you risk missing other opportunities with different strengths, cash profiles and risk levels identified by the Simply Wall St Screener.
- Target potential upside in mispriced quality by scanning the 35 high quality undervalued stocks that pair strong fundamentals with compressed expectations.
- Strengthen your search for resilience by reviewing the 32 resilient stocks with low risk scores focused on companies with more measured risk profiles.
- Hunt for under-followed potential by checking the 20 high quality undiscovered gems that combine solid numbers with limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com