
Kinsale Capital Group (KNSL) Faces Softer Forecasts As Fair Value Looks Fully Priced
Recent analyst forecasts for Kinsale Capital Group (KNSL) focus on its upcoming quarterly report, with expectations for earnings per share of $4.95 and revenue of $478.84 million, both projected below the prior year.
The recent bounce matters. Kinsale Capital Group’s share price is up 7.7% over the past 90 days and 7.2% over the last week, yet the year-to-date share price return is still down 6.9% and the 1-year total shareholder return has fallen 17.2%. At the same time, the much stronger 122.3% total shareholder return over five years suggests that momentum has cooled from earlier years even as shorter-term sentiment has improved ahead of the results.
Spot opportunities beyond Kinsale Capital Group by scanning a curated 32 resilient stocks with low risk scores that may hold up better when earnings expectations reset.The recent rebound in Kinsale Capital Group sharpens the question. After a short burst of strength against weaker earnings expectations, does the current valuation still leave more upside for new buyers than downside if sentiment cools again?
Most Popular Narrative: 3% Overvalued
Kinsale Capital Group closed at $365.59 compared with a narrative fair value of $354.78, so the market is paying a small premium for its profile while analysts expect slower revenue and earnings over the next few years.
The numbers indicate that Kinsale’s current share price already reflects a full valuation for a high ROE insurer with strong capital returns, so investors are paying for perceived quality rather than a clear margin of safety.
See why 42 investors see Kinsale Capital Group as 3% overvalued.
Result: Fair Value of $354.78 (OVERVALUED)
Still, the narrative around Kinsale Capital Group can crack if softer E&S pricing pressures earnings for longer than expected or if insider selling signals deeper management caution.
Find out about the key risks to this Kinsale Capital Group narrative.
Another View: Cash Flow Suggests A Different Fair Value For Kinsale Capital Group
The analyst narrative frames Kinsale Capital Group as roughly fully priced around a fair value of $354.78 based on earnings and multiples. A different lens tells another story. The Simply Wall St DCF model estimates KNSL’s future cash flows at $569.18 per share, which implies the stock is trading at a 35.8% discount to that figure and signals a very different balance between perceived risk and potential reward. Which version of fair value do you lean toward when the next earnings print lands?
To understand how this cash flow view is built and what would need to change for either valuation to converge, Look into how the SWS DCF model arrives at its fair value.
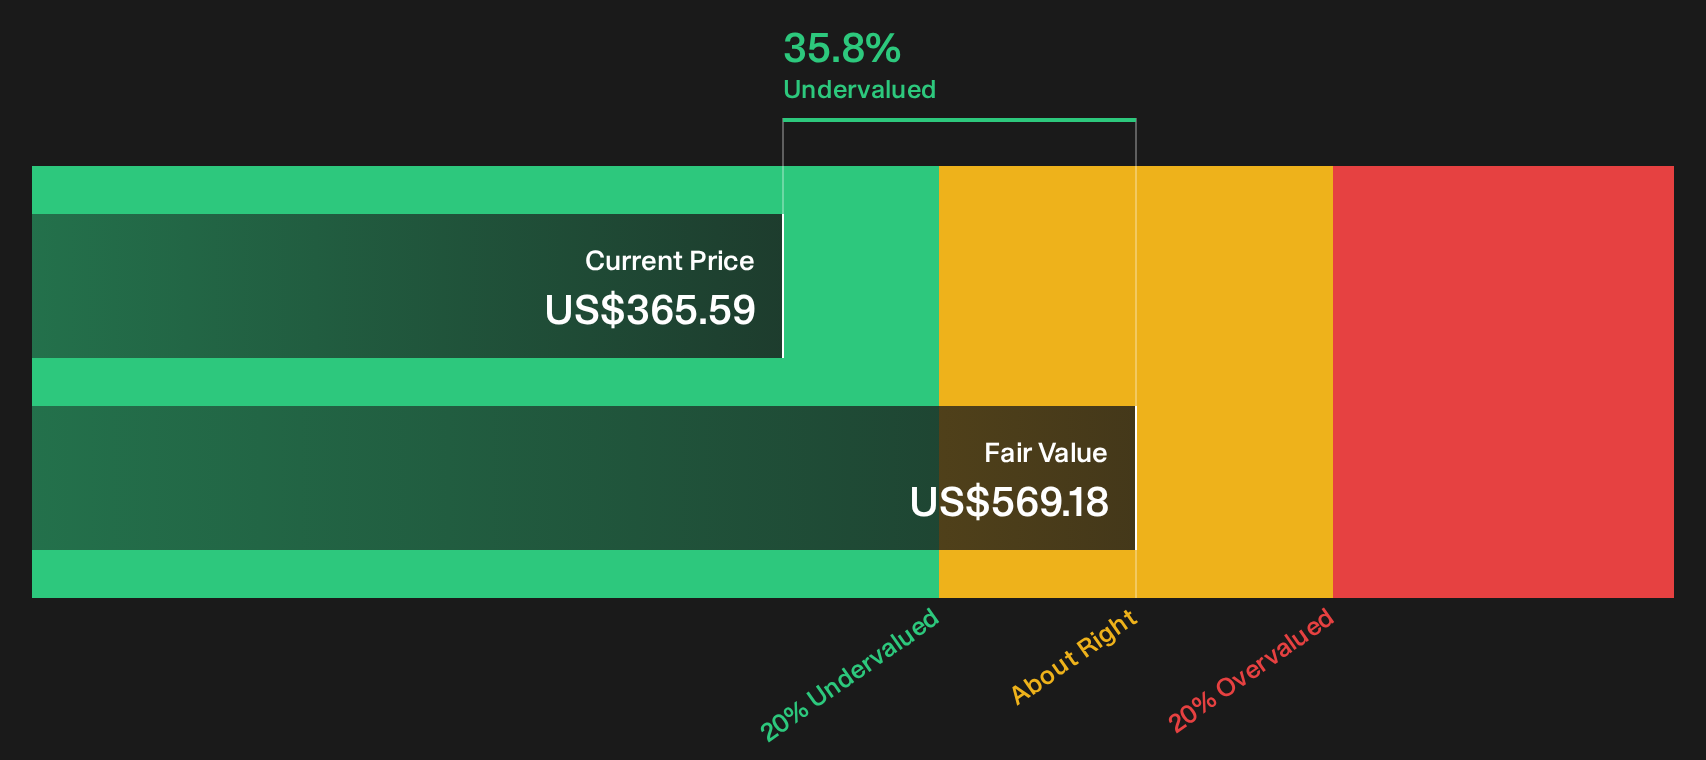
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kinsale Capital Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kinsale Capital Group can cut both ways, so move quickly, review the underlying data for yourself, then weigh the 2 key rewards and 1 important warning sign
Looking for more Kinsale Capital Group style investment ideas?
Before closing the tab, give yourself a broader watchlist. Fresh ideas often come from places you are not currently looking.
- Target steadier rides by scanning a 32 resilient stocks with low risk scores that filters for businesses with stronger downside resilience.
- Hunt for potential mispricings with a 35 high quality undervalued stocks that highlights companies combining solid fundamentals with discounted share prices.
- Build a cash flow stream using a 8 dividend fortresses that focuses on higher yielding payers with the potential to support ongoing distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com