
Is Hyatt Hotels (H) A Bargain On Its St. Louis Hyatt Centric Opening?
Hyatt Hotels (H) just added a new flag to its portfolio with the opening of Hyatt Centric Downtown St. Louis, a Missouri debut that links fresh branding to a renovated historic property.
For context, Hyatt Hotels shares closed at US$171.95, with short term momentum reflected in a 1 week share price return of 6.68% and 1 month gain of 10.91%, while a 90 day decline of 9.27% contrasts with a 1 year total shareholder return of 16.67% and a 5 year total shareholder return of 110.08%. This suggests that recent headlines like the St. Louis opening are landing on top of a much longer run of value creation for long term holders.
Scan for other hospitality stocks pursuing similar expansion plays by reviewing the hand picked 20 high quality undiscovered gems that may be flying under most investors radar.
Hyatt Hotels now has a fresh headline and a sharply higher short term return. The real test is whether this move reflects sturdier business progress or just changing mood around the stock, which is where valuation comes in.
Most Popular Narrative: 13% Undervalued
Hyatt Hotels is trading at a last close of $171.95 against a narrative fair value of $196.83, which frames the St. Louis opening within a broader fee based growth story that investors are still debating.
The record development pipeline of about 154,000 rooms, with roughly two thirds in international and full service hotels and weighted toward higher fee luxury, lifestyle, inclusive and Essentials brands, points to future rooms and fee growth as properties open and begin contributing to revenue.
See why 6 investors see Hyatt Hotels as 13% undervalued.
Result: Fair Value of $196.83 (UNDERVALUED)
Still, the Hyatt Hotels story can be knocked off course if pressure in Middle East and Mexican resorts lingers, or if planned hotel asset sales face further setbacks.
Find out about the key risks to this Hyatt Hotels narrative.
Another View: Hyatt Hotels Through A Sales Multiple Lens
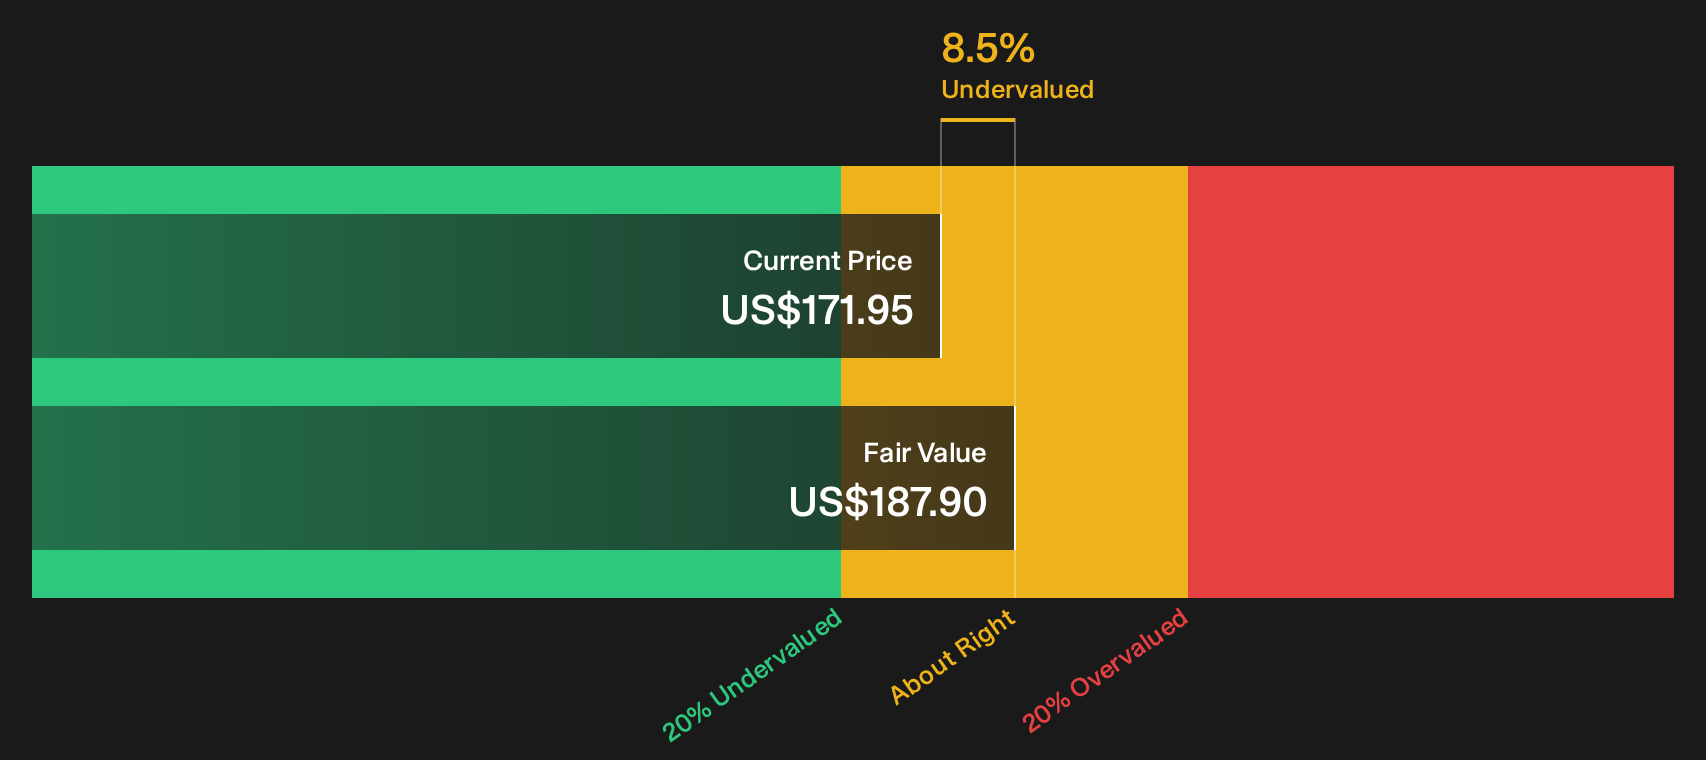
The SWS DCF model points to Hyatt Hotels trading about 8.5% below an estimated future cash flow value of $187.90, which tilts the story toward undervaluation. Yet the P/S ratio of 4.8x looks expensive versus the US Hospitality average of 1.6x and a fair ratio of 3.3x. That gap raises a simple question for investors: is the market rewarding quality or overpaying for growth hopes?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed feelings about Hyatt Hotels after all that. If the blend of risk and upside has you curious, review the data yourself, then check out the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hyatt Hotels?
If Hyatt Hotels has your attention, do not stop there. Use the Simply Wall Street screener to spot other opportunities before they move without you.
- Target resilience by filtering for companies with stronger finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for value by scanning the 35 high quality undervalued stocks that combine quality fundamentals with appealing prices.
- Limit downside risk by focusing on the 32 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com