
Norfolk Southern (NSC) Following Rail Safety Project Is It Still Undervalued
Norfolk Southern’s rail safety project and earnings expectations
The REDESIGN rail crossing project in Birmingham and Trussville puts Norfolk Southern (NSC) in focus, as investors also consider analyst expectations for the railroad’s upcoming quarterly earnings and revenue performance.
Norfolk Southern’s recent REDESIGN announcement lands after a mixed stretch in the market, with the share price up 12.39% year to date and total shareholder return of 13.06% over the past year, while a 75.05% three year total shareholder return signals longer term momentum that investors are weighing against near term earnings expectations.
Scan beyond Norfolk Southern to see how other rail and industrial transport operators compare on earnings potential and balance sheet strength with the list of solid balance sheet and fundamentals (25 results)
After Norfolk Southern’s strong multiyear run and fresh gains this year, investors face a key question: does meaningful upside still lie ahead, or is most of the move already in the rearview mirror as valuation enters focus?
Most Popular Narrative: 9% Undervalued
Norfolk Southern’s most followed narrative places fair value at $356.11 per share, above the recent $323.48 close, framing the stock as modestly undervalued while investors reassess earnings power, merger risk and rail safety commitments.
The company's focus on increasing customer confidence through consistent service improvements is leading to meaningful market share gains, particularly in merchandise and intermodal segments, which could bolster future revenue growth. Expansion of domestic and premium intermodal business, supported by tighter truck markets, elevated fuel prices and restructured contracts, is expected to support continued truck to rail conversion and higher revenue per unit ex fuel.
See why 11 investors see Norfolk Southern as 9% undervalued.
Result: Fair Value of $356.11 (UNDERVALUED)
Still, the Norfolk Southern story can change quickly if fuel expenses continue to climb or if merger delays and legal claims begin to erode the current earnings narrative.
Find out about the key risks to this Norfolk Southern narrative.
Another View: Norfolk Southern’s valuation through earnings multiples
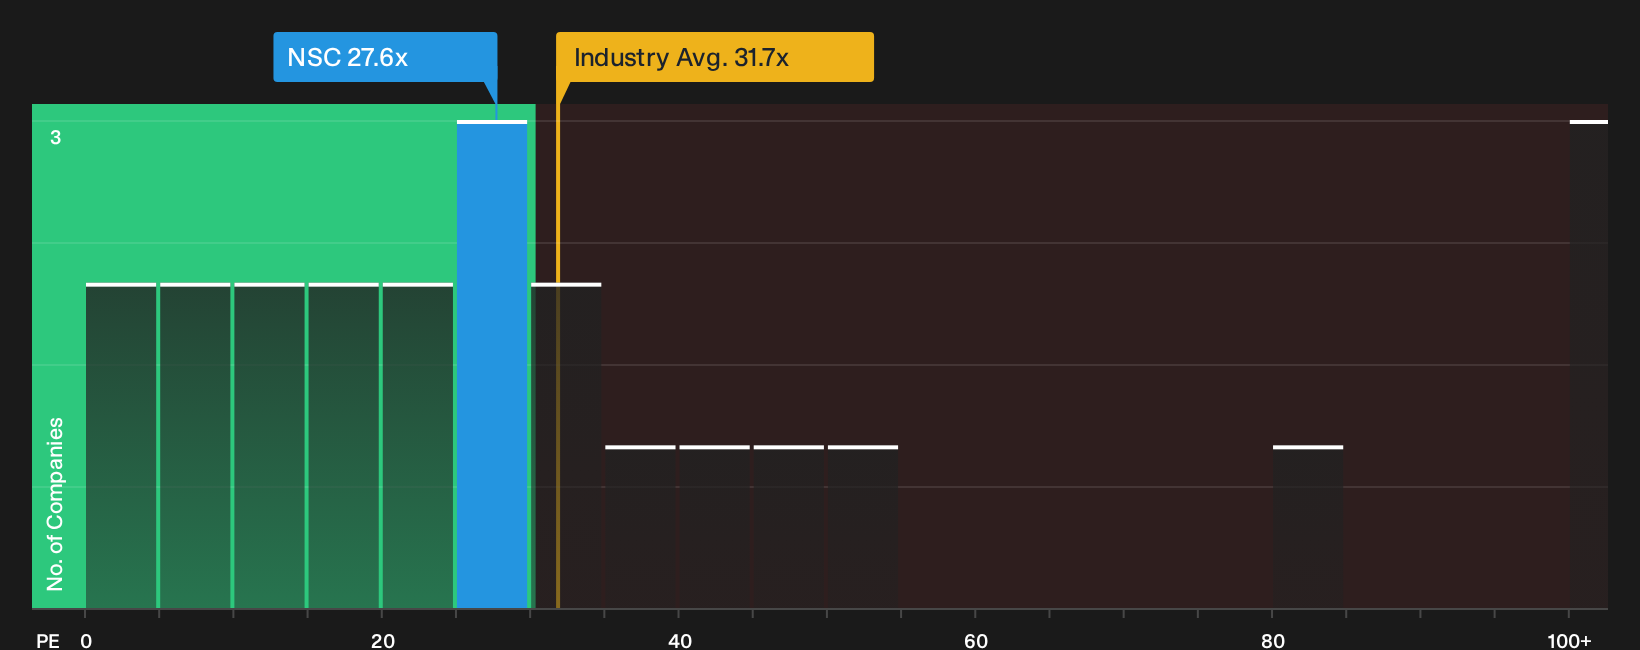
The fair value narrative presents Norfolk Southern as 9% undervalued, yet its current P/E of 27.6x suggests a more cautious perspective. That figure is above the fair ratio of 20.8x and ahead of peer averages at 25.5x, although it remains below the wider US Transportation industry at 32.1x. For investors, the gap between today’s P/E and the fair ratio highlights potential valuation risk if sentiment cools or earnings weaken in the near term, rather than obvious room for upside. Which version of the story appears more convincing when real money is on the line?
For readers who want to see how this earnings-based view compares with a more detailed framework, the valuation breakdown from the fair ratio work serves as a useful cross-check on expectations and sentiment around Norfolk Southern today, and how quickly that picture might change if assumptions are challenged by new data. See what the numbers say about this price — find out in our valuation breakdown.
For an at-a-glance comparison of Norfolk Southern’s current earnings multiple against the sector and wider US market, the following chart can help frame where the stock currently trades on this metric.
Next Steps
Mixed signals around Norfolk Southern often lead to mixed emotions for investors, so move quickly from headline impressions to your own verdict by weighing both sides through the 3 key rewards and 1 important warning sign
Looking for more Norfolk Southern investment ideas beyond this rail story?
If Norfolk Southern has sharpened your focus, do not stop here. Apply the same disciplined lens to other opportunities and let the data guide your next move.
- Target potential value opportunities early by scanning companies flagged as high quality and potentially mispriced with the 35 high quality undervalued stocks.
- Prioritize resilience by reviewing a curated set of businesses with sturdier finances using the 32 resilient stocks with low risk scores.
- Spot under-the-radar potential by assessing fundamentally strong companies that attract less attention through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com