
Matson (MATX) Following Makua Christening Is The Fleet Upgrade Story Still Undervalued
Matson (MATX) just hit a major fleet milestone by christening the LNG-ready containership Makua as the first of three new Aloha Class vessels tied to a roughly $1b modernization plan.
Recent trading reflects that story. Matson’s share price has climbed 87.36% year to date, and the 1-year total shareholder return of 147.64% points to strong momentum, even with a 1-day share price decline of 1.37% as investors digest the Makua milestone and the upcoming early November earnings release.
Scan for other shipping and logistics stocks pursuing large scale fleet upgrades or infrastructure refreshes by reviewing our curated list of list of solid balance sheet and fundamentals (25 results)
After a 147.64% 1-year total return and a fleet overhaul measured in billions, the obvious question around Matson now is simple: Is most of the upside already in the price or still ahead?
Most Popular Narrative: 16% Undervalued
Against Matson's last close of $231.78, the most followed narrative centers on a fair value of $276.75. That gap is framed around earnings power, capital returns and the LNG fueled fleet refresh now underway.
The current narrative that Matson is undervalued holds that the share price does not fully reflect the raised 2026 earnings outlook, the growth in Southeast Asia volumes, and the scale of ongoing dividends and buybacks.
See why 10 investors see Matson as 16% undervalued.
Result: Fair Value of $276.75 (UNDERVALUED)
Still, the Matson narrative could be tested if capital intensive LNG vessel spending squeezes free cash flow, or if China and Southeast Asia volumes soften more than analysts expect.
Find out about the key risks to this Matson narrative.
Another View: What Matson’s P/E Is Telling You
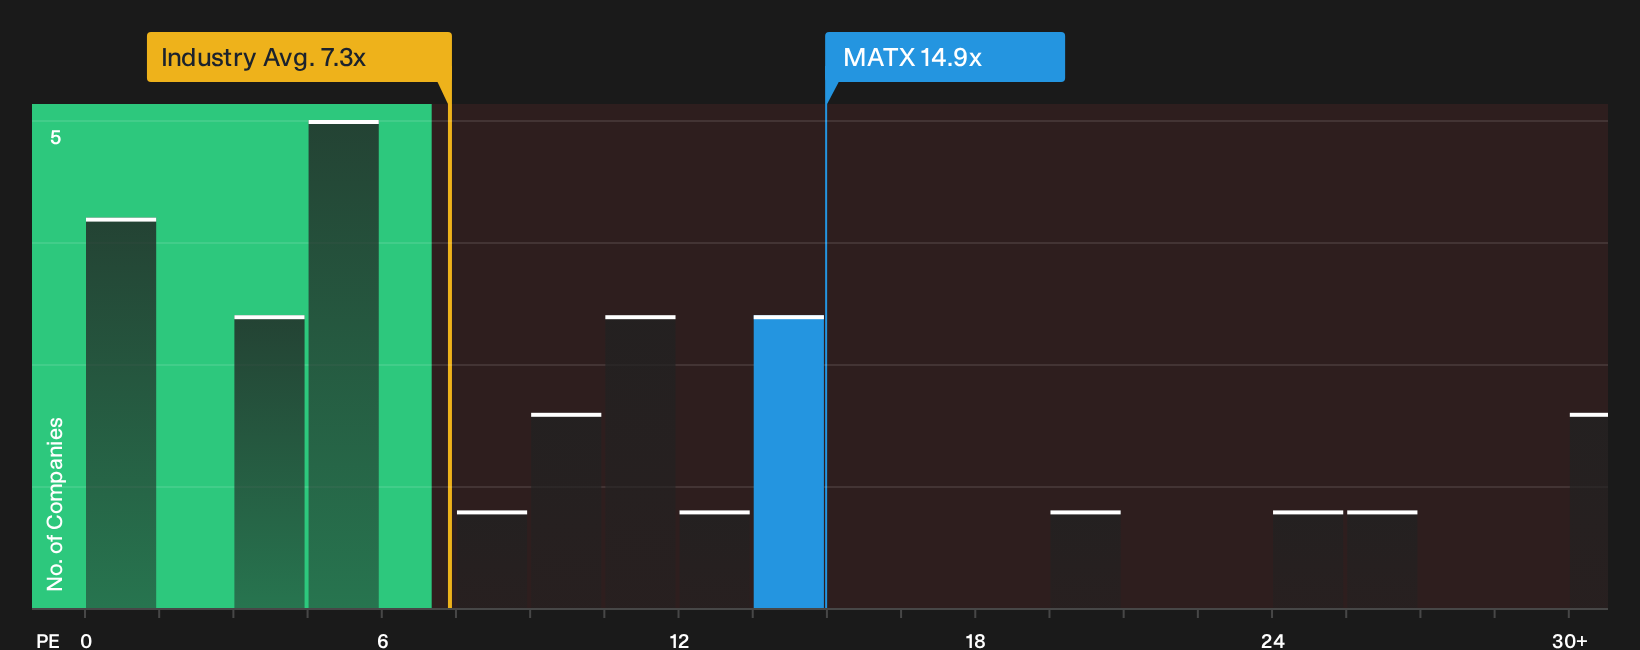
Analysts calling Matson undervalued on a fair value of $276.75 are looking through an earnings lens. The current P/E of 14.9x is almost double the US Shipping industry at 7.4x, is a touch cheaper than peers at 15.5x, and sits above a fair ratio of 13.2x. That mix hints at some valuation risk if expectations cool, even with the stock trading 13.1% below one fair value estimate. So which signal do you trust more: the discount to fair value or the premium to the fair ratio?
To pressure test that question against hard numbers, review how Matson screens when P/E is stacked against both industry and peers in our valuation breakdown, then compare it with other companies that share similar earnings profiles but trade closer to their fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
For a quick visual sense check of how richly Matson trades versus rivals on earnings, look at the latest side by side chart here:
Next Steps
Feeling torn between Matson’s recent surge and the valuation signals you are seeing in the charts and ratios? Move quickly, review the same core data, and pressure test both the upside case and the bear arguments by weighing the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Matson?
Do not stop at Matson. Use the Simply Wall Street Screener to explore additional ideas that fit your risk, return, and income preferences.
- Target resilient balance sheets by scanning companies that pass strict financial strength filters with our list of solid balance sheet and fundamentals (25 results).
- Look for value opportunities by focusing on quality businesses that the market currently prices below their fundamentals using the 35 high quality undervalued stocks.
- Strengthen your income stream by concentrating on companies with higher yields through the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com