
Elite Undervalued Stocks To Own In October 2026
Energy markets are still unsettled after the International Energy Agency warned they may not return to normal next year, and that keeps pressure on interest rates and funding costs. When money is less forgiving, companies that generate solid cash and trade at a discount start to matter more. This article highlights three stocks that screen as potentially mispriced on cash flows and explains why they may appeal to patient value hunters.
The three examples in this piece are just a sample set, and the full screen highlighted 99 more companies with similarly interesting cash flow stories that are not covered here. To identify and analyze those potential opportunities directly, head straight to the Undervalued Stocks Based On Cash Flows screener.
Mueller Water Products (MWA)
Overview: Mueller Water Products supplies valves, hydrants, pipe repair hardware and intelligent water management systems that support long term municipal cash flows.
Operations: Mueller Water Products generates about $824 million from Water Flow Solutions and $655 million from Water Management Solutions, largely across US$1.36b in United States revenue.
Market Cap: US$3.40b
Mueller Water Products fits this cash flow focused screen because its municipal water management work leans on long contracts, repeat projects, and essential maintenance rather than one off construction bursts.
"Management expects continuation of healthy municipal repair and replacement activity, which it views as growing low to mid single digits and offsetting weaker new residential construction. This could support more stable revenue for Mueller Water Products even as housing related demand softens."
The real swing factor is how one less visible constraint shapes the balance between rising profitability and the pace of future cash returns.
That hidden constraint is exactly what the full narrative for Mueller Water Products unpacks in detail, showing where cash returns could accelerate and where they risk stalling.

F.N.B (FNB)
Overview: F.N.B is a regional financial group that earns most of its money from everyday lending and banking services that feed directly into the cash flow story of this screener.
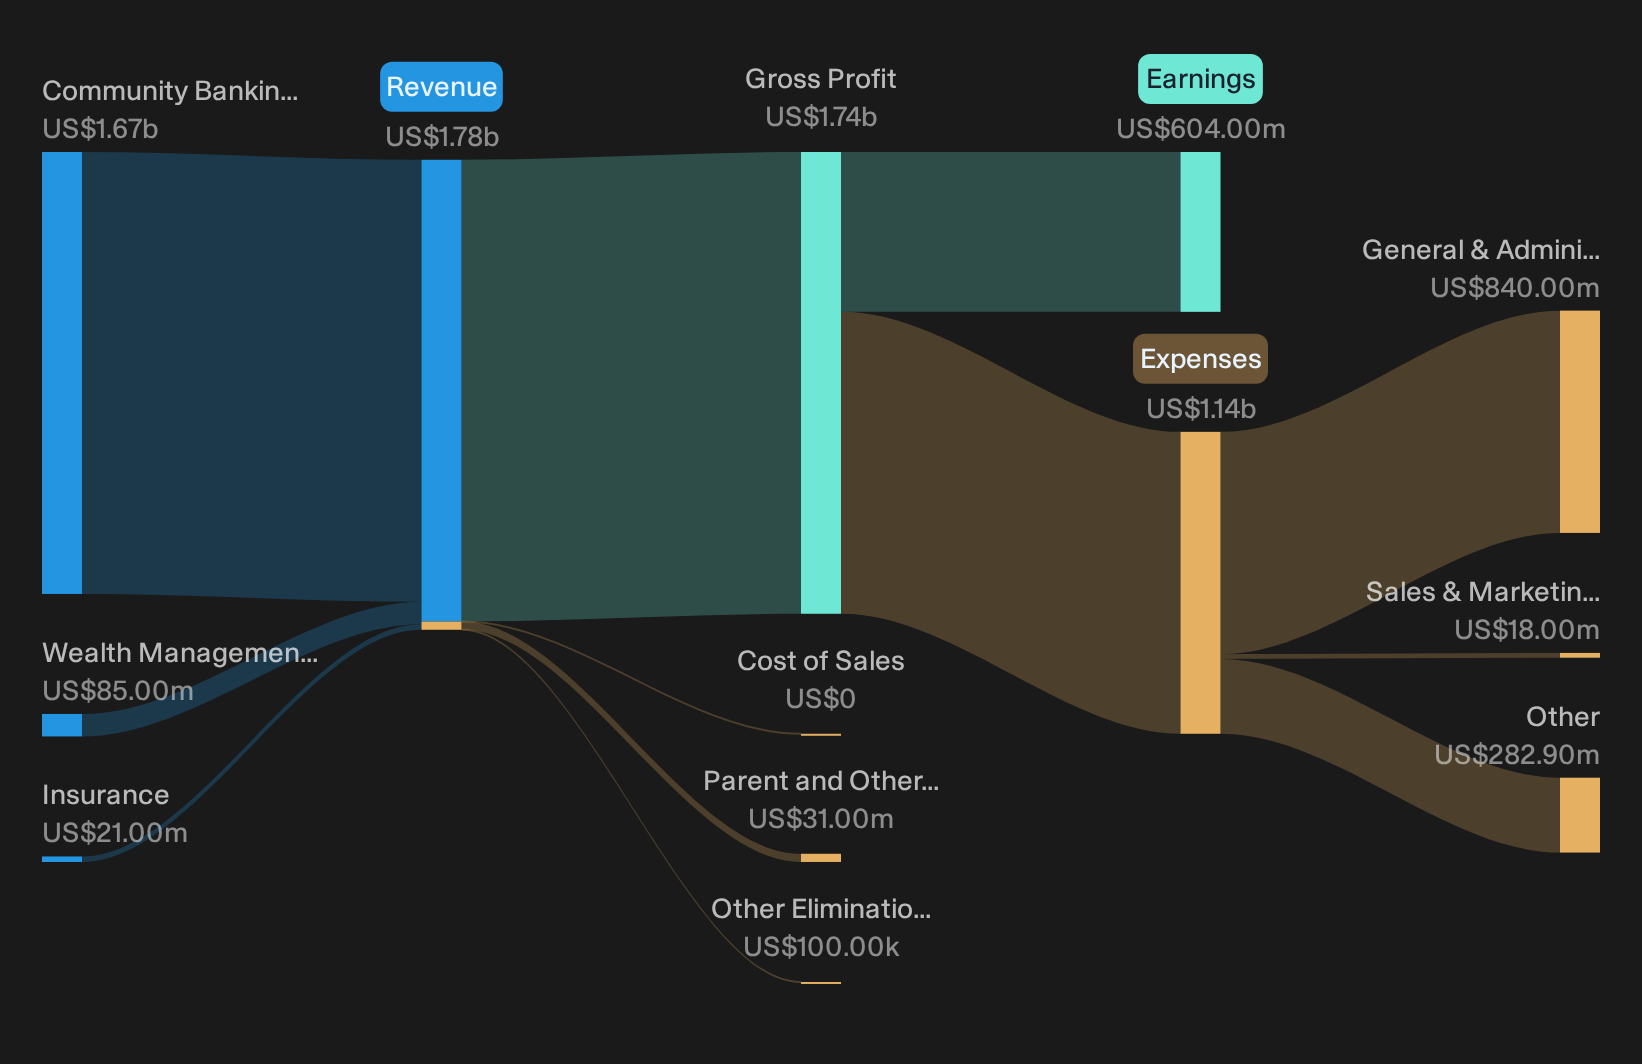
Operations: F.N.B generates about $1.67b from Community Banking, $85 million from Wealth Management, and $21 million from Insurance, almost entirely in the United States.
Market Cap: US$6.08b
F.N.B matters here because its lending engine, from mortgages to small business credit, turns deposit relationships into cash streams that a discounted cash flow model can scrutinize in detail.
"F.N.B's ongoing investment in digital and AI tools, including the Insight 360 platform and call-center automation expected to be live by the end of 2026, is intended to deepen customer insights and streamline servicing, which could support higher revenue per customer and better net margins."
The real tension for F.N.B is how one less visible shift in its funding mix could ultimately shape where those margins settle.
That funding shift is exactly where the story gets interesting, and the full narrative for F.N.B maps how funding costs, deposit loyalty and fee income could be quietly accelerating beneath the surface.
Wintrust Financial (WTFC)
Overview: Wintrust Financial runs a community-focused banking franchise that leans on loan and deposit relationships to generate recurring interest and fee income.
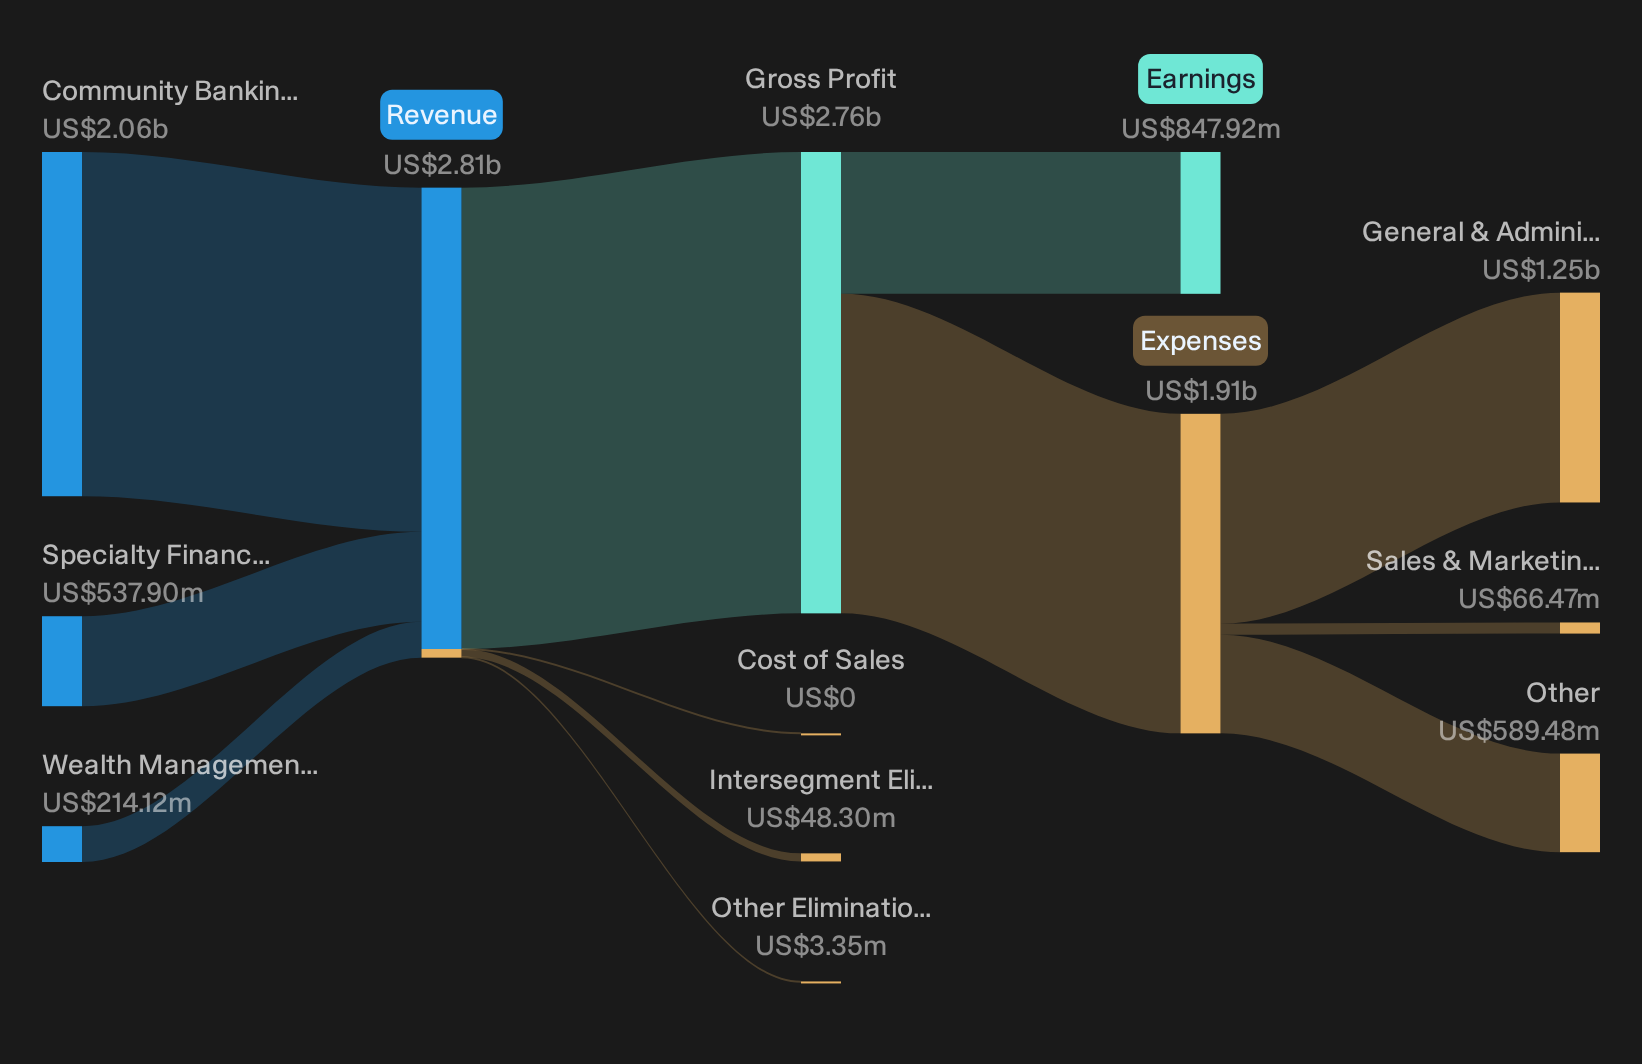
Operations: Wintrust Financial generates about $2.06b from Community Banking, $538 million from Specialty Finance and $214 million from Wealth Management.
Market Cap: US$9.59b
Wintrust Financial fits this cash flow screen because its Community Banking lending books turn everyday borrowing into steady interest streams. A discounted cash flow model can weigh these streams against a market price that still looks sceptical.
"Organic loan and deposit growth across commercial, premium finance, mortgage and specialty lending segments is building a larger base of earning assets, which directly supports revenue and earnings."
The key question now is how one quiet shift in funding costs and loan mix will feed through to future margins and cash returns.
As that shift plays out, the full narrative for Wintrust Financial connects the funding story to where Wintrust Financial’s cash engine could be accelerating or quietly stalling next.
Curious About Fresh Alternatives?
Fresh ideas often move first. By the time momentum is strong, early entries may be gone and odds can shift quickly. Review these under the radar lists while it may still matter.
- Review companies in the 32 resilient stocks with low risk scores to explore resilient compounding and keep risk scores in check while many portfolios are focused on the next hot trade.
- Explore potential income ideas through the 8 dividend fortresses that focus on higher yielding payouts while prices are still moving in and out of favor under the radar.
- Review the 43 power grid technology and infrastructure stocks to consider infrastructure-related opportunities connected to long term grid upgrades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com