
Casella Waste Systems (CWST) Earnings Beat Keeps Undervalued Narrative In Play
Casella Waste Systems (CWST) is in focus after reporting quarterly results that topped analyst forecasts for both revenue and earnings, while also lifting full-year revenue guidance and posting industry-leading top-line growth.
Despite the upbeat quarter, Casella Waste Systems’ share price has drifted, with the stock down 12.28% on a year-to-date share price basis and 4.42% over 90 days, even as the 3-year total shareholder return of 14.02% points to steadier, longer-run momentum.
Track how Casella Waste Systems stacks up against other potential breakouts by scanning our handpicked list of 20 high quality undiscovered gems in similar corners of the market.
Casella Waste Systems now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after a strong quarter. Is that a pricing error, or a fair reflection of the risks investors see?
Most Popular Narrative: 22% Undervalued
Casella Waste Systems last closed at $86.54, while the most followed narrative frames fair value at $111. This creates a wide gap that puts the focus squarely on whether future execution can justify that spread.
Infrastructure investments in automation and technology, including the deployment of 40 automated trucks expected to deliver more than US$5 million of savings in 2026, AI enabled in cab safety systems and new billing platforms, are intended to reduce operating and G&A costs over the next several years. These initiatives can support EBITDA margin recovery and improved net income.
See why 3 investors see Casella Waste Systems as 22% undervalued.
Result: Fair Value of $111 (UNDERVALUED)
Still, Casella Waste Systems carries clear pressure points, including compressed operating margins over five years and ongoing acquisition integration work. These factors could keep earnings under strain.
Find out about the key risks to this Casella Waste Systems narrative.
Another View: Casella Waste Systems Looks Expensive On Sales
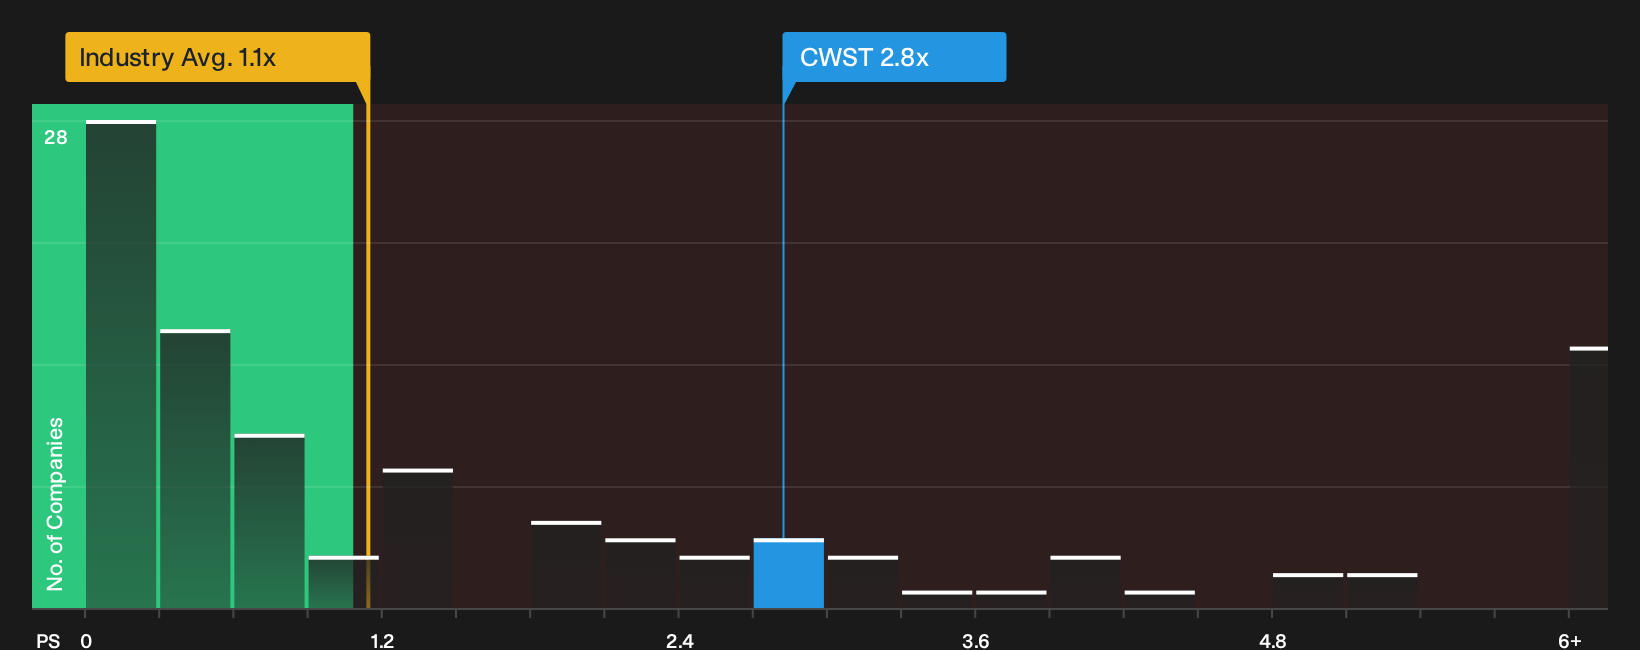
On the flip side of that fair value narrative, Casella Waste Systems screens as expensive on its P/S ratio. The stock trades around 2.8x sales, compared with a fair ratio estimate of 1.5x and a US Commercial Services sector average of 1.1x. That gap points to real de-rating risk if expectations slip.
For anyone weighing that trade off between upside and valuation stretch, our detailed breakdown of the numbers can help put the current pricing into context: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity: either way, it is worth checking the underlying numbers and weighing both sides of the story for yourself. To see the full balance of potential upside and the issues investors worry about, review the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Casella Waste Systems?
If Casella Waste Systems has caught your attention, do not stop there. Broaden your opportunity set and pressure test your thesis across a wider field of potential contenders.
- Target stronger balance sheets and steadier fundamentals by reviewing our list of solid balance sheet and fundamentals (25 results), which highlights businesses with robust financial footing and cleaner capital structures.
- Hunt for better value by scanning the 35 high quality undervalued stocks, which filters for companies combining quality metrics with prices that sit below intrinsic estimates.
- Aim for hidden potential by working through the 20 high quality undiscovered gems, which surfaces lesser known stocks with fundamentals that may not yet be widely appreciated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com