
Can Delta Air Lines (DAL) Justify Its Price On Strong Q4 Guidance?
Delta Air Lines (DAL) just paired a softer third quarter profit with assertive guidance, flagging about 20% year on year revenue growth and a 7% to 9% operating margin target in the fourth quarter.
Recent trading has been choppy for Delta Air Lines, with the share price down 6.8% over the past week and 11.8% over 90 days. However, the 1-year total shareholder return of 22.2% and roughly 141% over three years point to longer term momentum that contrasts with the current pullback around the latest earnings and guidance headlines.
Compare Delta Air Lines' setup against a hand picked group of travel and transport players by running the same lens across our 35 high quality undervalued stocks.
Delta Air Lines has slumped after its latest profit update, yet the market price still sits well below both analyst targets and intrinsic value estimates. How far does that gap run, and what does it really imply?
Most Popular Narrative: 18% Overvalued
Against the last close at $74.63, the leading narrative on Delta Air Lines pegs fair value at $63.21, framing the current quote as rich versus that anchor.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That's why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop, and Delta would have to increase its current profit margins considerably to justify these multiples, which is a well nigh impossible order. If you seek exposure to the airline industry, Delta is a mandatory buy without doubt, but not at these levels. Once the froth is out of the price, however, I'm certain to increase my holding.
See why 23 investors see Delta Air Lines as 18% overvalued.
According to PittTheYounger, that assessment leaves Delta Air Lines on the expensive side of their fair value line, with the stock trading about 18% above the $63.21 narrative estimate despite a sector that already runs on thin margins.
Result: Fair Value of $63.21 (OVERVALUED)
Still, that overvaluation story can unravel quickly if Delta Air Lines faces a sharp demand shock or if already thin industry margins compress further.
Find out about the key risks to this Delta Air Lines narrative.
Another View: SWS DCF Points the Other Way
The user narrative tags Delta Air Lines as rich at $74.63 against a $63.21 fair value, yet our DCF model lands in a very different place. On that framework, the future cash flow value sits at $245.32, which frames the current quote as heavily undervalued. Which story do you trust more when cash flow does the talking?
Look into how the SWS DCF model arrives at its fair value.
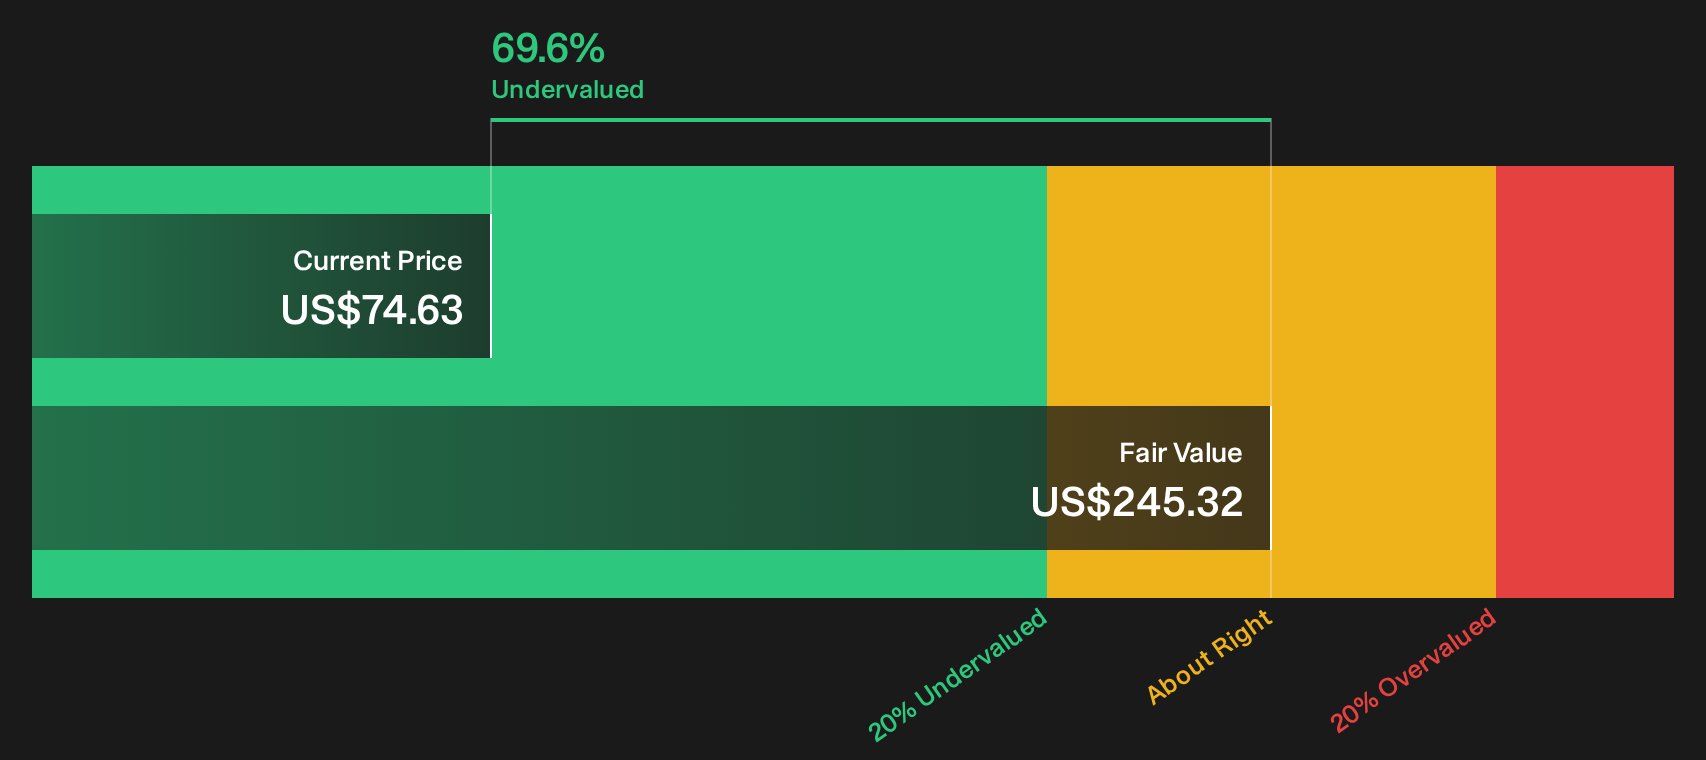
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Delta Air Lines valuation and risk can leave you torn, so move quickly to review the data and build your own stance. To see both the potential upsides and the key concerns in one place, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Delta Air Lines?
If Delta Air Lines has sharpened your focus on pricing and risk, do not stop here. Run fresh screens, compare setups quickly, and keep your watchlist evolving.
- Target resilient balance sheets and steady fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that filters out fragile businesses before they hit your portfolio.
- Hunt for mispriced opportunities by scanning a focused 35 high quality undervalued stocks that blends quality metrics with valuation checks to surface potential outliers.
- Lock in income ideas by reviewing a 8 dividend fortresses designed for investors who want higher yields backed by robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com