
Is LiveRamp Holdings (RAMP) Fully Valued As Publicis Wins FTC Approval?
Regulatory approval clears key hurdle for LiveRamp Holdings
LiveRamp Holdings (RAMP) moved back into focus after the Federal Trade Commission approved Publicis Groupe’s planned $2.2 billion acquisition, attaching conditions related to competition, product access, and protection of customer data.
At a share price of US$38.21, LiveRamp Holdings has enjoyed a 39.35% year to date share price return and a 36.42% total shareholder return over the past year, while the 5 year total shareholder return is down 27.08%. This points to strong recent momentum following a weaker longer run.
Scan other data collaboration and software stocks showing similar M&A momentum and pricing setups through our hand picked 20 high quality undiscovered gems as you assess what this deal means for LiveRamp Holdings.
LiveRamp Holdings now trades within cents of the announced deal price, while sitting at a sizeable discount to one intrinsic value estimate. Where does fair value truly land across that spread, and what are you really paying for today?
Most Popular Narrative: 1% Undervalued
The most followed narrative pegs LiveRamp Holdings’ fair value at $38.70, only slightly above the last close at $38.21. This puts the conversation squarely on what is driving that tight gap rather than a big pricing mismatch.
The agreed all cash acquisition by Publicis at roughly 12.3x forward adjusted 2026 EBITDA, together with Publicis’ plan for at least US$50 million of run rate cost savings and an operating margin profile aligned with its own from the first year of consolidation, points to scope for further operating margin and earnings contribution from LiveRamp’s platform inside a larger group.
See why 17 investors see LiveRamp Holdings as 1% undervalued.
Result: Fair Value of $38.70 (ABOUT RIGHT)
Still, the LiveRamp Holdings story leans heavily on U.S. marketing budgets and assumes profit margins hold near current levels, so any domestic slowdown or cost pressure could quickly challenge this fair value view.
Find out about the key risks to this LiveRamp Holdings narrative.
Another view on LiveRamp Holdings’ valuation
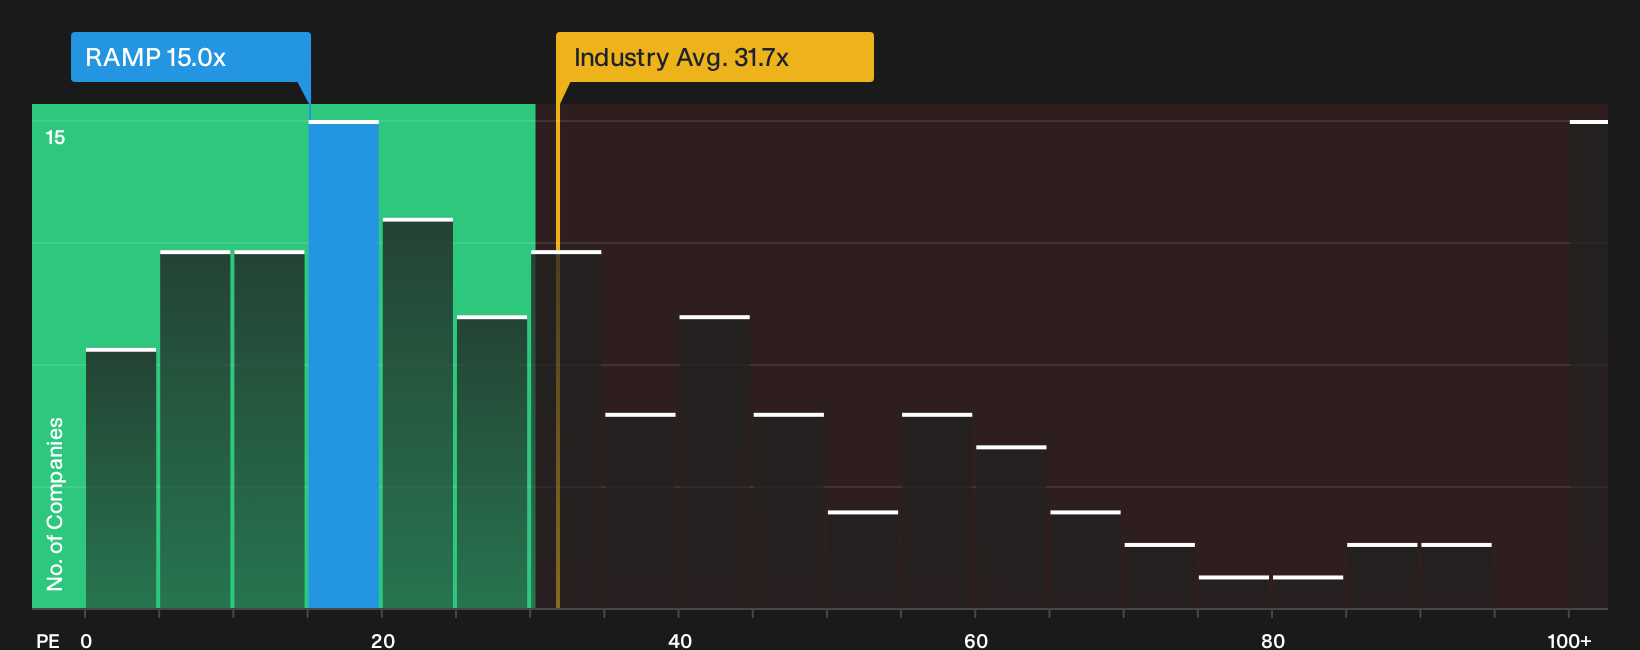
On earnings multiples, LiveRamp Holdings looks different to the 1% undervalued fair value story. The stock trades on a P/E of 15x, while the estimated fair ratio sits at 18.4x and the wider US Software group averages 30.8x, with peers around 38.1x. That gap points to a cheaper tag but also raises the question of whether the market is baking in extra risk or leaving room for rerating.
To see how that pricing gap lines up with the earnings profile, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LiveRamp Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around LiveRamp Holdings is finely balanced, so do not wait for others to tell you what it means. Test the numbers, stress test the assumptions, then weigh up the 3 key rewards.
Looking for more LiveRamp Holdings investment ideas?
Do not stop at one stock. Use the Simply Wall Street Screener to spot fresh opportunities that match your risk, return, and income targets before others do.
- Target potential mispricing across the market by scanning a curated set of 35 high quality undervalued stocks that pair solid fundamentals with more modest expectations.
- Prioritise resilience in tougher conditions by focusing on a list of solid balance sheet and fundamentals (25 results) that can better handle funding costs and operational surprises.
- Lock in potential income ideas by reviewing a hand picked group of 8 dividend fortresses that offer higher yields supported by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com