
Why ConocoPhillips (COP) Is Getting Attention Today
ConocoPhillips (COP) just posted Q2 2026 results that paired high net income with strong operating cash flow, funding ongoing capital spending, share repurchases, and regular dividends that keep shareholder return firmly in focus.
ConocoPhillips shares have eased 0.87% over the last day to US$145.24. The 7 day and 30 day share price returns of 5.58% and 10.17% suggest buyers are leaning in after Q2, while the 50.20% year to date share price gain and 72.09% 1 year total shareholder return indicate momentum that extends beyond the latest quarter.
See how ConocoPhillips fits into the broader energy opportunity set by checking our hand picked list of solid balance sheet and fundamentals (25 results) that prioritize resilience and cash generation.
That kind of rally can either echo real progress in ConocoPhillips' cash engine or lean more on sentiment chasing recent headlines. Which picture does the current valuation paint?
Most Popular Narrative: 2.5% Undervalued
ConocoPhillips last closed at $145.24, while the most followed valuation framework points to a fair value of $149.04 that sits slightly higher.
Global LNG market tightness, combined with ConocoPhillips securing 12 MTPA of LNG offtake and expecting first LNG from projects such as Port Arthur from 2027, points to a growing contribution from LNG marketing that could support higher revenue and cash flow than currently reflected in the stock.
See why 106 investors see ConocoPhillips as 3% undervalued.
Result: Fair Value of $149.04 (UNDERVALUED)
Still, the story can break if large projects like Willow or Port Arthur are delayed or if higher capital spending erodes the free cash flow uplift investors expect.
Find out about the key risks to this ConocoPhillips narrative.
Another View: ConocoPhillips Through The P/E Lens
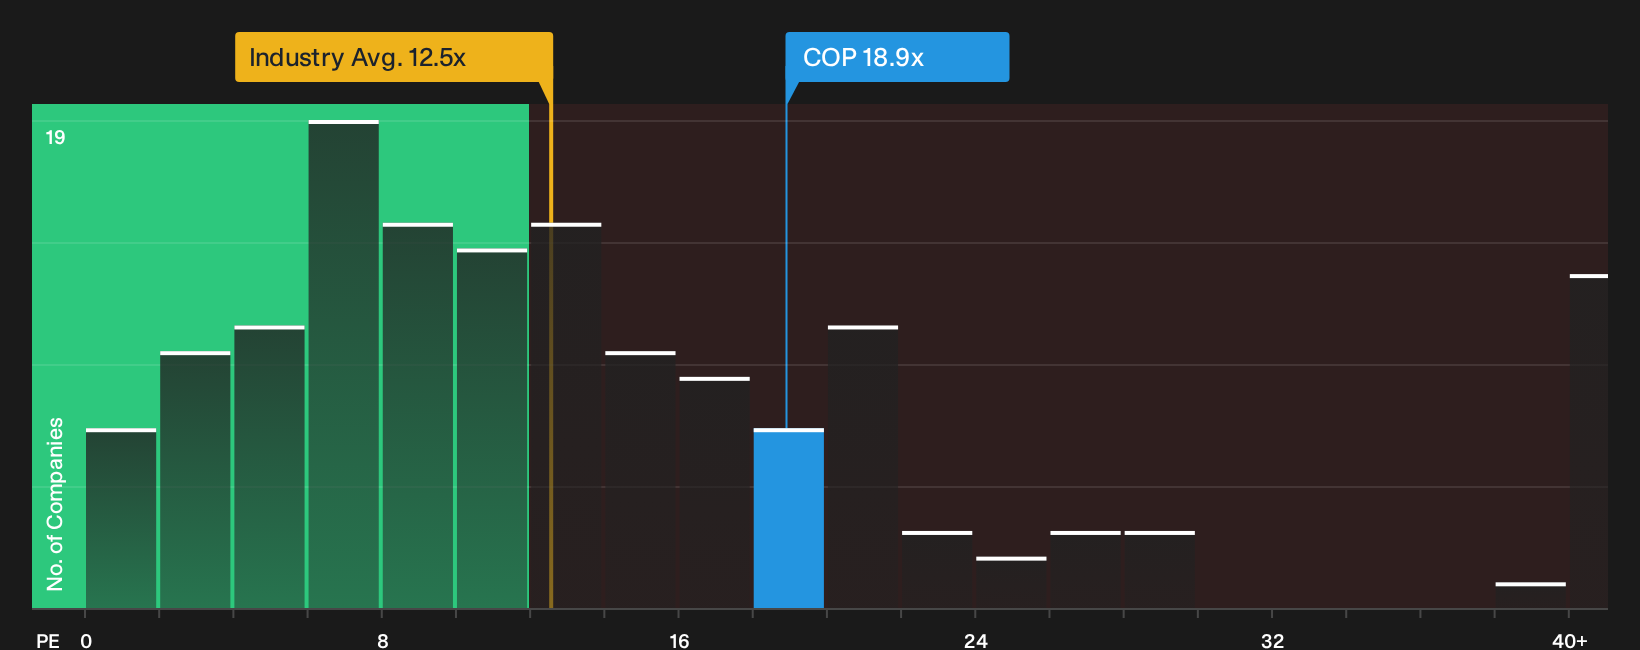
Look past that 2.5% “undervalued” fair value call and the picture shifts. On a P/E of 18.9x, ConocoPhillips trades well above the US Oil and Gas industry on 12.5x, yet only slightly below its peer average on 19.6x and the 19.8x fair ratio that the market could move towards. That mix of premium to the sector but near fair ratio raises a practical question for you. Is this price giving enough room for execution hiccups, or does it already bake in most of the LNG and project upside you care about?
Before leaning too heavily on any single P/E snapshot, it helps to see how all those inputs stack together in a fuller valuation breakdown, including where ConocoPhillips screens rich or reasonable versus peers and the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and project execution risk can pull investors in opposite directions, so move fast and review the underlying data yourself. To consider both sides of the ConocoPhillips story in one place, take a closer look at 1 key reward and 2 important warning signs
Looking for more investment ideas beyond ConocoPhillips?
If ConocoPhillips already sits on your radar, do not stop there. Use this momentum to widen your watchlist and review your next moves with fresh ideas.
- Target potential opportunities in quality businesses that trade below their estimated worth by scanning through our 35 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that pair higher yields with staying power using the 8 dividend fortresses.
- Prioritise resilience by filtering for companies with robust finances and durable fundamentals through our 32 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com