
Camil Alimentos Climbed While Profit Fell From A Year Earlier
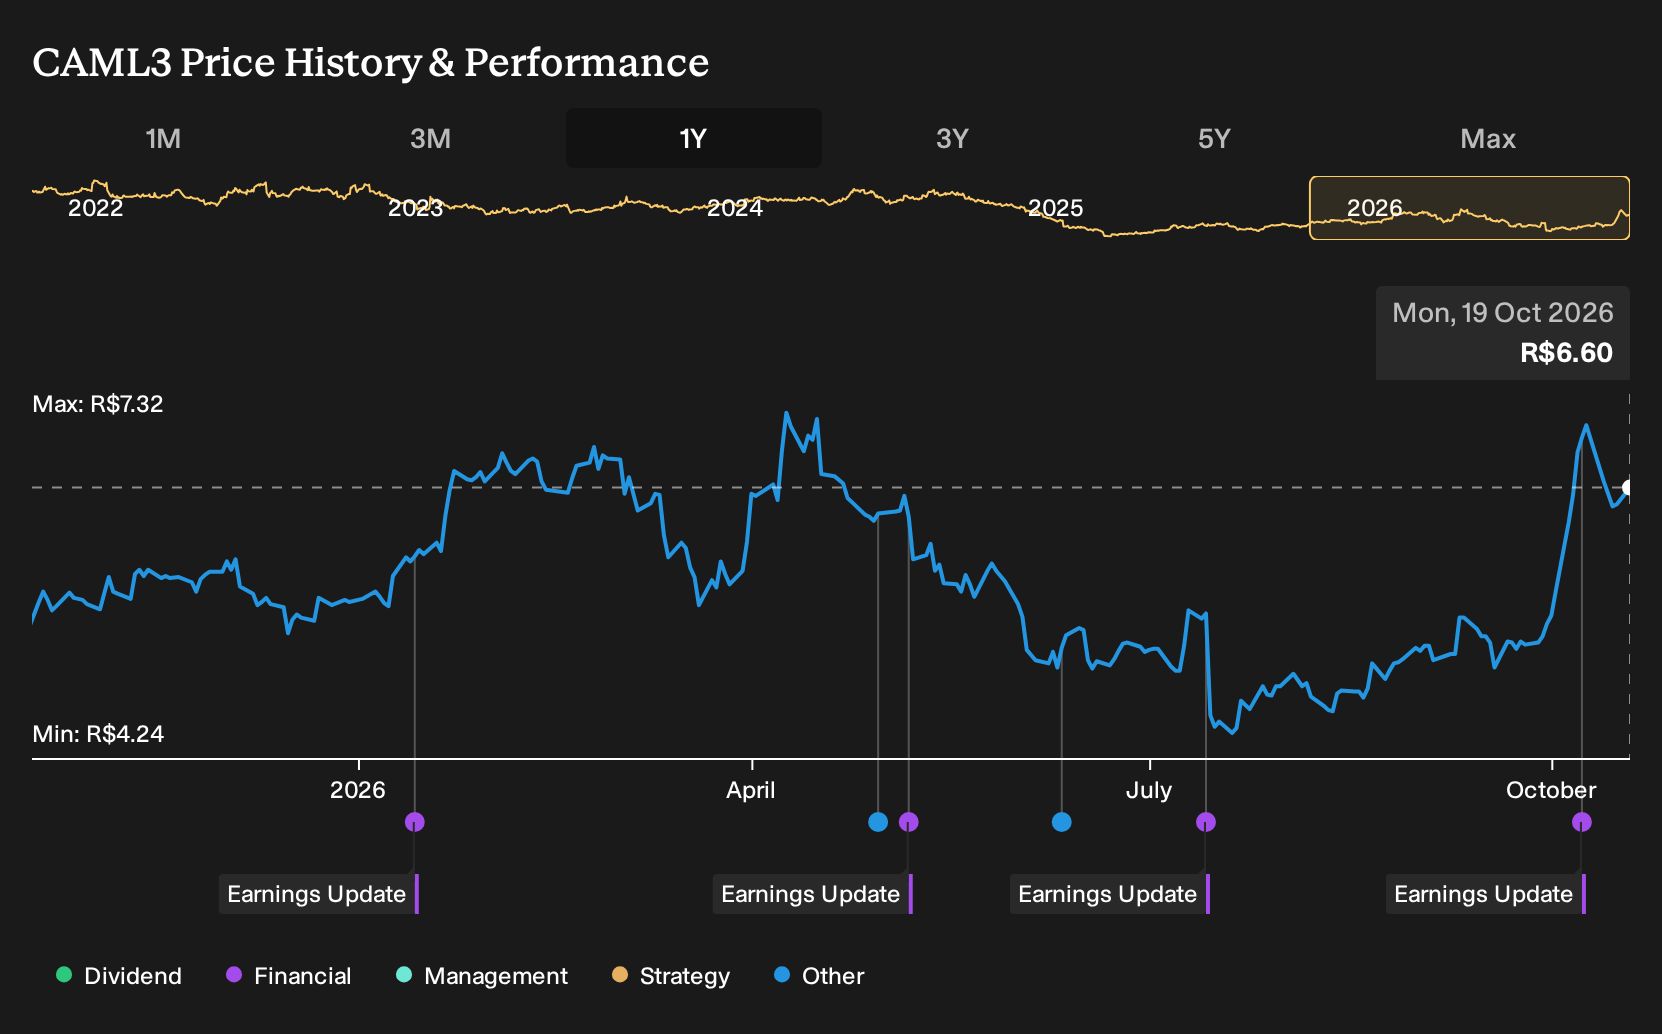
If Camil Alimentos was on your watchlist rather than in your portfolio, the outcome may feel like a missed shot. Holding Camil Alimentos over the past year would have returned 26.2%, including dividends. That move came even as analysts argued over whether underused plants and a rising Latin American middle class could really turn commodity staples into better margins. Looking back to October 2025, how could you have judged that utilization bet before the payoff showed up in the price?
The easy part of this move is behind Camil Alimentos. Zero in on 198 high quality undervalued stocks for companies trading below our estimates.
The Two Camil Alimentos Stories Investors Had To Weigh
The shares cost R$5.17 at the start of the period, and Camil Alimentos sat between two very different but believable stories about its future.
The bullish narrative argued that a rising Latin American middle class and fuller use of plants could justify a Fair Value of R$9, a price implied by assumptions of stronger volumes, better margins, and wider geographic reach across markets like Paraguay, Uruguay, Chile, Peru, and Ecuador.
The bearish script pointed to climate risk, weak brand differentiation, and heavier regulation, backing a Fair Value of R$4 that rested on concerns about commodity price swings, supply chain disruption, and slower progress in higher value products.
What The Results Changed In The Camil Alimentos Debate
The most concrete development was the Q2 2027 report. Camil Alimentos posted revenue of R$2,764.792 million and net income of R$41.095 million, with net margin at 1.5% versus 2.6% a year earlier. That profitability shift challenged the bullish story that fuller plants and a richer product mix would quickly support stronger margins. The evidence cut both ways.
The big lesson is where to look next time. When a thesis leans on margin expansion, track net margin and absolute profit in each result. Then test whether they are moving toward the narrative or drifting away from it.
What Today's Camil Alimentos Price Already Assumes
Camil Alimentos now trades at R$6.6 after a 26.2% gain over the past year. The selected Narrative’s Fair Value sits below that level, suggesting that the market already prices in effective execution on higher margin categories and international operations.
The key assumption you would be underwriting is that mix upgrades and overseas growth can outweigh weak Brazilian demand and rice pricing. The question is how the Narrative’s concerns around softer consumption, rice prices and overhead affect that emphasis on efficiency and product mix.
"The current valuation suggests that the market is already factoring in successful execution on higher growth categories, international expansion and deleveraging, which may leave limited flexibility if weak consumption, low rice prices or higher working capital needs persist."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 33% below our estimate - runs a high cost gold portfolio with long life reserves and active conversion drilling.
- Company 2 - 31% below our estimate - expands multichannel electronics retail using heavier digital investment and faster New Zealand store rollout.
- Company 3 - 49% below our estimate - wins long dated public infrastructure and defense projects using modular, digitally managed construction methods.
Those are three of them. See every one of the 202 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com