
How Investors Are Reacting To CNX Resources Stock Strong Cash Flow Story
- Recent coverage of CNX Resources highlighted the company’s attractive Appalachian gas asset base, robust gross margin profile, and sizeable free cash flow that supports both reinvestment in drilling programs and ongoing returns to shareholders.
- The focus on strong free cash generation relative to reported profitability positions CNX Resources as a business in which operational discipline and capital allocation choices play a central role in how investors interpret value.
- We will examine how CNX Resources' investment narrative is influenced by this focus on free cash flow strength and disciplined reinvestment.
Scan for other cash rich operators with disciplined reinvestment by comparing CNX Resources against our curated list of 35 high quality undervalued stocks.
CNX Resources Investment Narrative Recap
CNX Resources appeals to investors who think a cash rich Appalachian gas producer with hedged volumes and tax credit potential can keep turning an attractive asset base into steady free cash flow. The key short term swing factor is how efficiently CNX Resources keeps drilling and operating while holding its gross margin profile in a choppy gas price backdrop.
The biggest near term risk sits around external variables. Treasury guidance on 45Z tax credits and timing of new in basin power and data center demand remain outside the company’s control. The recent value focused attention on CNX Resources does not materially change those operational or policy catalysts.
Recent commentary tying CNX Resources to value ideas leans heavily on its current P/E discount and strong free cash generation. That discussion lines up with existing catalysts such as longer dated hedging and efficiency gains in Utica drilling, which are already aimed at smoothing cash flows and keeping unit costs in check.
There are no fresh company specific announcements directly tied to this news flow. The most relevant thread is management’s ongoing capital allocation playbook, including share repurchases, debt refinancings and the plan to monetize 45Z and other environmental attributes. All of these feed into the same question for you: can CNX Resources keep converting its asset base into durable, repeatable cash per share while carrying a meaningful debt load?
What The CNX Resources Forecasts Actually Assume
CNX Resources is being modeled as a business that keeps revenue broadly steady while profit compresses and earnings step down into the end of this decade. Analysts are not baking in rapid expansion. They are instead pairing flat top line expectations with a much slimmer margin profile.
In the current set of forecasts, revenue is expected to be roughly stable over the next three years while profit margins move from 44.4% today to 19.8% by 2029. That shift in profitability does most of the work in the earnings story and it matters more than any assumed volume growth in Appalachian gas output.
Earnings today are estimated at US$949.4 million. Consensus points to US$435.9 million of profit and earnings per share of US$4.13 by 2029, which implies earnings would fall by about US$513.5 million over the forecast window rather than compound higher from this base. Analysts also build in about 7% yearly growth in the share count over the next three years, so the per share impact of any future cash generation is already being diluted in the numbers you see.
CNX Resources' narrative projects US$2.2b revenue and US$435.9 million earnings by 2029. This rests on revenue staying fairly flat over the next three years and an earnings decrease of about US$513.5 million from earnings today of US$949.4 million.
Valuation work in the report then connects those operating assumptions to a higher future P/E multiple. For the 2029 consensus earnings of US$435.9 million to support the analyst targets, CNX Resources would need to trade on about 19.2x earnings compared with roughly 4.9x today and a current US Oil and Gas industry P/E of 12.3x. That gap between today’s multiple and the implied future one is a key swing factor in how you might judge the risk and reward on the stock.
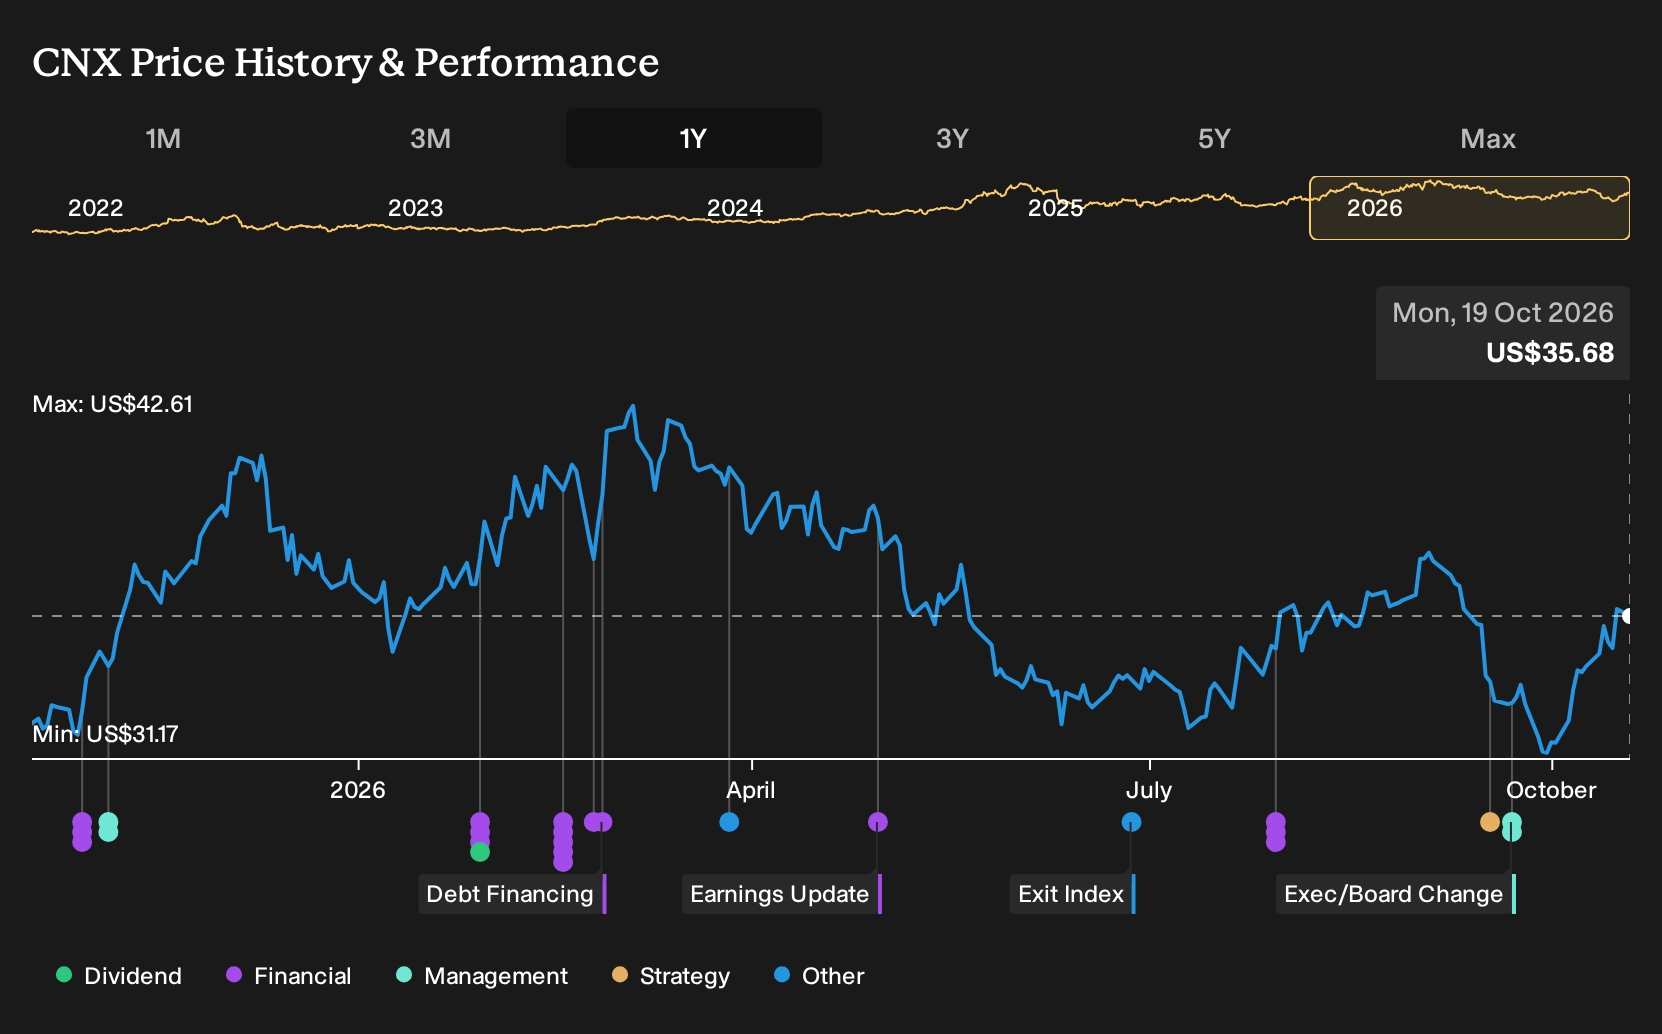
Price targets cluster around a consensus of US$37.55 per share, with the most optimistic analyst at US$48.0 and the most cautious at US$32.0. Against a recent share price of US$31.50, that central target sits about 16.1% higher, even though the same set of forecasts point to lower earnings, slimmer margins and a higher share count by 2029.
For anyone using this research as a starting point, the practical question is simple. Decide whether steady revenue, much lower profitability and a step down in earnings for CNX Resources still support a meaningfully higher valuation multiple than the one the market applies today.
Uncover why CNX Resources' fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One big swing factor the more optimistic analysts lean into is low carbon revenue. They were penciling in about US$2.6b of sales and US$893.8 million of earnings by 2029 for CNX Resources, versus bearish views closer to US$455.3 million. That gap shows how sharply opinions may reset once this latest news is absorbed.
Explore 2 other CNX Resources fair value estimates, including one that suggests as much as 155% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your CNX Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CNX Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNX Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond CNX Resources?
If the CNX Resources setup has sharpened your sense of what matters in free cash flow, balance sheet resilience and payout potential, it can be useful to line that framework up against a broader watchlist built from the Simply Wall St Screener.
- For investors who want income that does more of the heavy lifting, scan companies offering strong payout profiles with our 8 dividend fortresses and see which ones match your return goals.
- If capital preservation sits high on your list, filter for stocks that pair steadier fundamentals with lower risk scores using the 32 resilient stocks with low risk scores to round out your research list.
- When you prefer balance sheets that can handle rougher conditions, narrow in on companies with solid financial footing by reviewing the list of solid balance sheet and fundamentals (25 results) and comparing them with what you see at CNX Resources.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com