
TransUnion (TRU) Expands Credit Matching Tools, Is The Stock Fully Priced?
What the recent product news means for TransUnion stock
TransUnion (TRU) has moved deeper into personalized lending with a new credit offer matching platform built with Bankrate and Monevo, alongside fresh mortgage tools aimed at tighter underwriting and lower score acquisition costs.
The new consumer matching experience combines TransUnion credit data with Bankrate's marketplace reach and Monevo's decision engine so lenders can present more tailored credit options inside TransUnion Credit Essentials and partner channels.
Mortgage lenders received separate tools in early October through First Look Functionality for Mortgage and extended VantageScore 4.0 pricing. Together these offerings are designed to let underwriters stage score purchases more selectively across the loan funnel.
Recent product launches come against a mixed trading backdrop for TransUnion, with the share price at US$73.12 after a 10.67% gain over the past week, a year-to-date share price return that is down 12.25%, and a 1-year total shareholder return that is down 8.15%.
Compare TransUnion's push into personalized lending with other data driven lenders by scanning our hand picked list of 20 high quality undiscovered gems.
TransUnion just logged a sharp weekly gain while longer term returns remain weaker. Is this product push a real shift in the underlying business, or mainly a change in mood that the valuation section can test?
Most Popular Narrative: 6% Overvalued
TransUnion closed at $73.12 while the most followed narrative pegs fair value near $68.87, so the product news lands against a backdrop where the stock is framed as slightly ahead of that fair value estimate, not drastically mispriced.
The assumed bearish price target for TransUnion is $68.87, which represents up to two standard deviations below the consensus price target of $92.24. This valuation is based on what can be assumed as the expectations of TransUnion's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 1 investors see TransUnion as 6% overvalued.
Result: Fair Value of $68.87 (OVERVALUED)
Still, a few things could flip this story if they go right, including faster take up of TruIQ and OneTru, or stronger international traction in India and Mexico.
Find out about the key risks to this TransUnion narrative.
Another View on TransUnion's value
The first narrative points to TransUnion trading about 6% above a US$68.87 fair value, based on earnings and multiples work. Our DCF model points in the opposite direction. It tags the shares at US$73.12 as below an estimated future cash flow value of US$145.82, which implies a very different risk reward balance.
If that cash flow path proves closer to reality than the earnings based fair value, short term noise around product launches and analyst targets may matter less than how durable TransUnion's data and pricing power really are over the next decade.
Look into how the SWS DCF model arrives at its fair value.
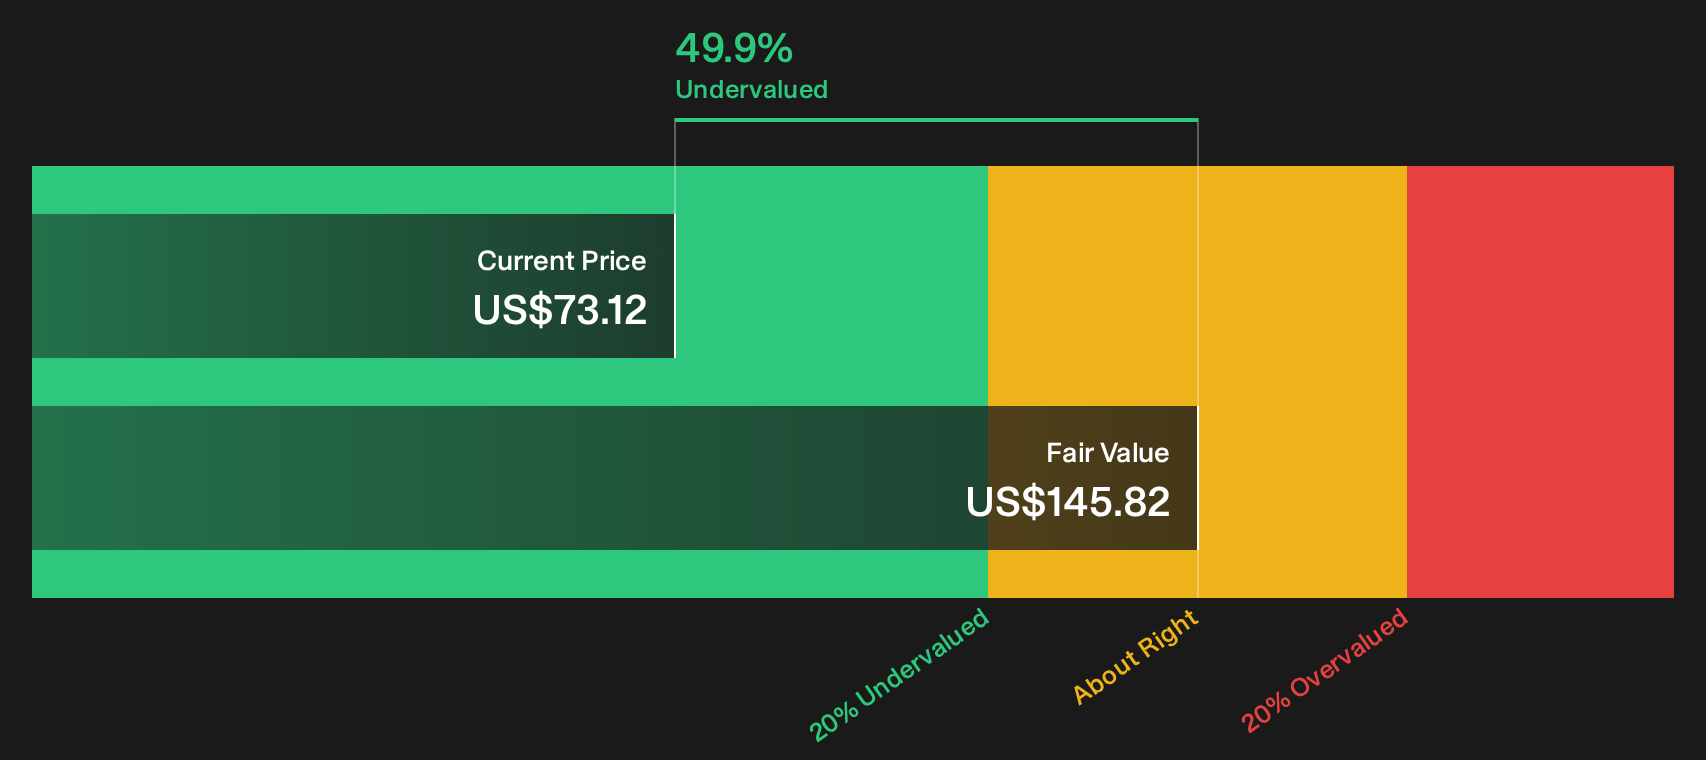
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TransUnion for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on value can either freeze you or prompt a closer look at the raw numbers and narratives around TransUnion. If you want to weigh both the concerns and the potential upside yourself, start by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond TransUnion?
If TransUnion has you thinking harder about where capital works best, do not stop at a single ticker. A broader watchlist can sharpen your judgement.
Widen your opportunity set by studying financially resilient businesses in our 32 resilient stocks with low risk scores that aim to balance return potential with steadier risk profiles.
- Target steadier compounding by reviewing companies that pair quality fundamentals with attractive pricing through the 35 high quality undervalued stocks.
- Secure more dependable cash flow potential by focusing on payout strength and consistency using the 8 dividend fortresses.
- Strengthen your downside protection by screening for balance sheets that carry lower leverage and solid liquidity in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com