
Caterpillar vs. Deere: The Better Heavy Equipment Stock for the Data Center Boom
Every major build-out, regardless of sector, requires one rather important thing: heavy equipment. These titanic machines play a major role in keeping businesses and economies moving, even if we only see them early on.
For investors, heavy machinery companies offer “picks-and-shovels” exposure to the current data center build-out. Of course, many want to look beyond the current boom, so it’s best to look at the company’s numbers and, more importantly, its ability to pay consistent dividends.
With those criteria, two familiar names easily come to mind: Caterpillar (CAT) and Deere (DE). Both are industry leaders with established dividend histories, but which one offers the better investment opportunity today?
Caterpillar Stock: More Than Heavy Machinery
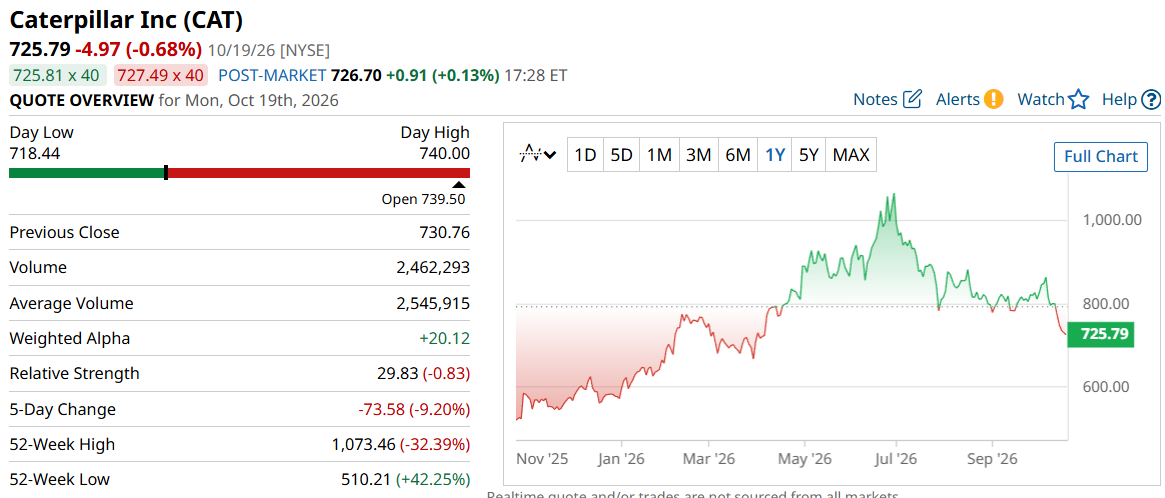
Caterpillar makes the iconic yellow bulldozers and excavators you see on big construction sites. But beyond heavy machinery, it is also serving in artificial intelligence, specifically in data centers. Caterpillar recently announced a $1 billion investment in North Carolina to increase production of smaller construction equipment.
That broad reach comes with a $335 billion market cap. CAT stock has also performed well this year, up around 27% year-to-date.
Deere Stock: Bringing Technology to the Farm and Beyond
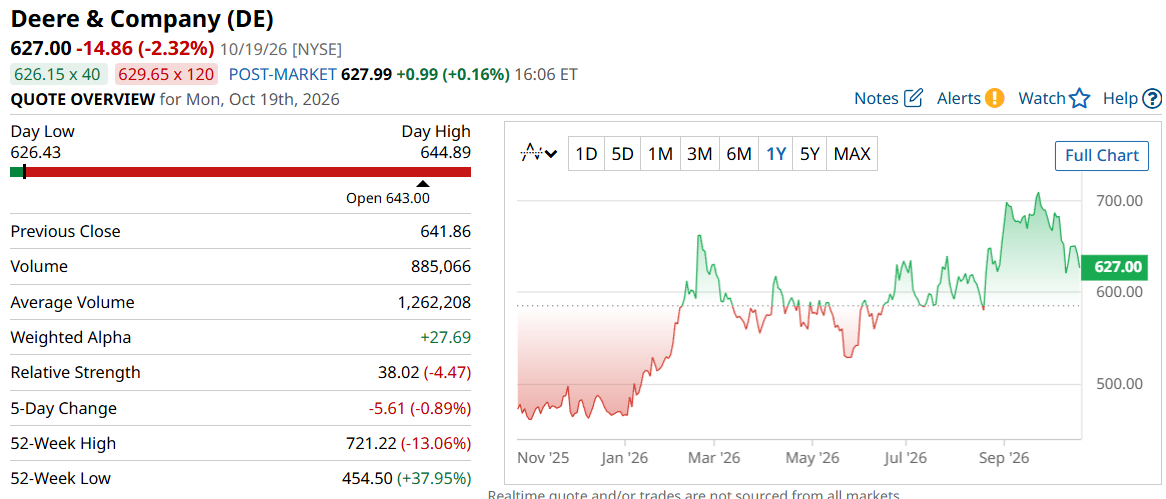
Deere is best known for its green tractors and harvesters that keep farms running. Though it also makes construction and forestry equipment, agriculture remains its bread and butter. That business is getting an upgrade with the introduction of JD, an AI assistant that uses a field's data to improve farming.
Deere is roughly half Caterpillar’s size, with a $169 billion market cap. Still, its stock has performed well this year, gaining about 35% year-to-date.
With both stocks performing well, do their recent financial results reflect a similar result?
CAT vs. DE: Financial Performance and Valuation
I used Barchart's Stock Comparison Tool to compare their financial performance and valuations.
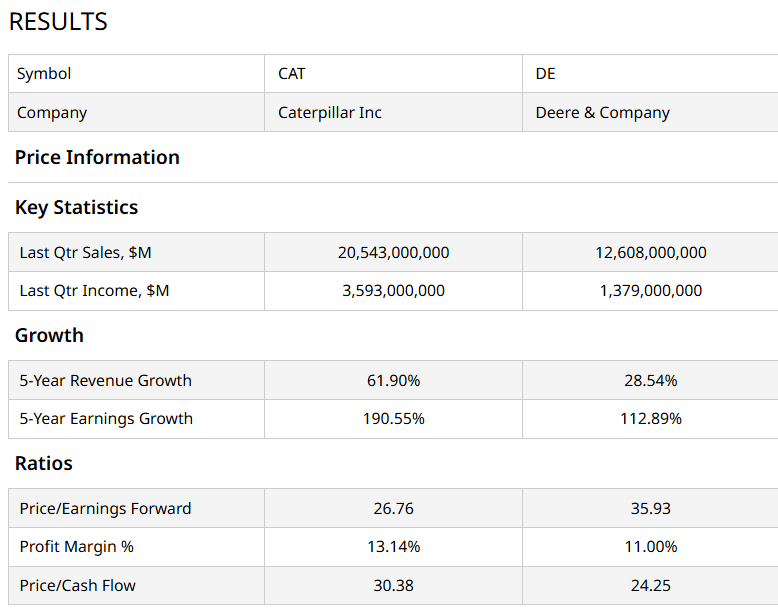
Let's start with the longer-term picture. Over the past five years, Caterpillar's earnings grew about 191%, compared with Deere's 113%, which is pretty reasonable given their size. The same story holds for revenue over the same period.
However, the gap becomes clearer in their latest quarterly results.
Caterpillar reported Q2 2026 sales of $20.5 billion, up 18% from the previous quarter. Meanwhile, Deere's Q3 2026 sales fell 5.7% QOQ to $12.61 billion.
The same trend shows in net income. Caterpillar's rose 41% to $3.59 billion, while Deere's dropped 22.2% to $1.38 billion. Overall, that may just be seasonal, but those figures are hard to ignore.
Caterpillar also has a slight profitability advantage, with a 13.14% profit margin compared with Deere’s 11%.
Despite its stronger financial performance, Caterpillar trades at a lower forward P/E of 27x, versus Deere’s 36x. But neither stock looks particularly cheap, with the industrial sector trading at around 27x forward earnings.
For now, Caterpillar looks like the better value, while Deere still needs to prove its turnaround justifies today's premium.
Who Has Better Yield: Caterpillar vs Deere
Caterpillar may have stronger financials, but Deere's dividend could turn the tables.
Caterpillar, the Dividend Aristocrat, pays $6.52 per share per year, for a yield of about 0.9%. Its dividend payout ratio is 25%, leaving most earnings available for reinvestment, other business needs, and shareholder value, including its dividend program.
Meanwhile, Deere pays $6.48 per share, translating to a yield of about 1%. Its dividend payout ratio is 36%, which is still relatively manageable, with about two-thirds of earnings available for other purposes.
Deere edges out a slightly higher yield, but the gap isn't wide, especially given both companies' payout ratios. With that, what does Wall Street have to say?
Caterpillar or Deere: Which Stock Does Wall Street Pick
All things considered, the race is still tight.
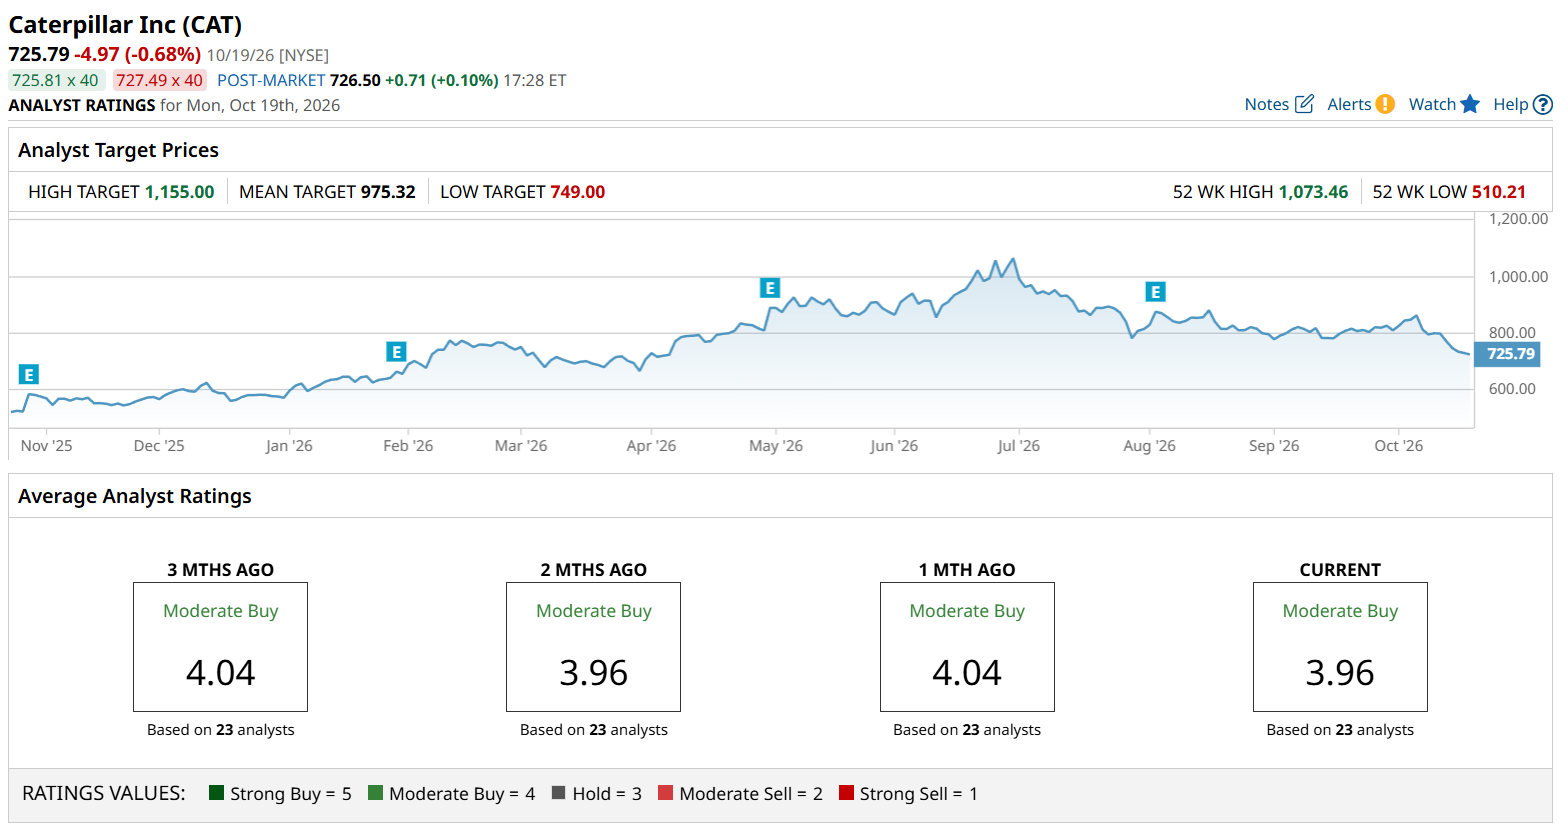
A consensus among 23 analysts rates CAT stock a “Moderate Buy”. Its high target price suggests about 59% upside if it's achieved.
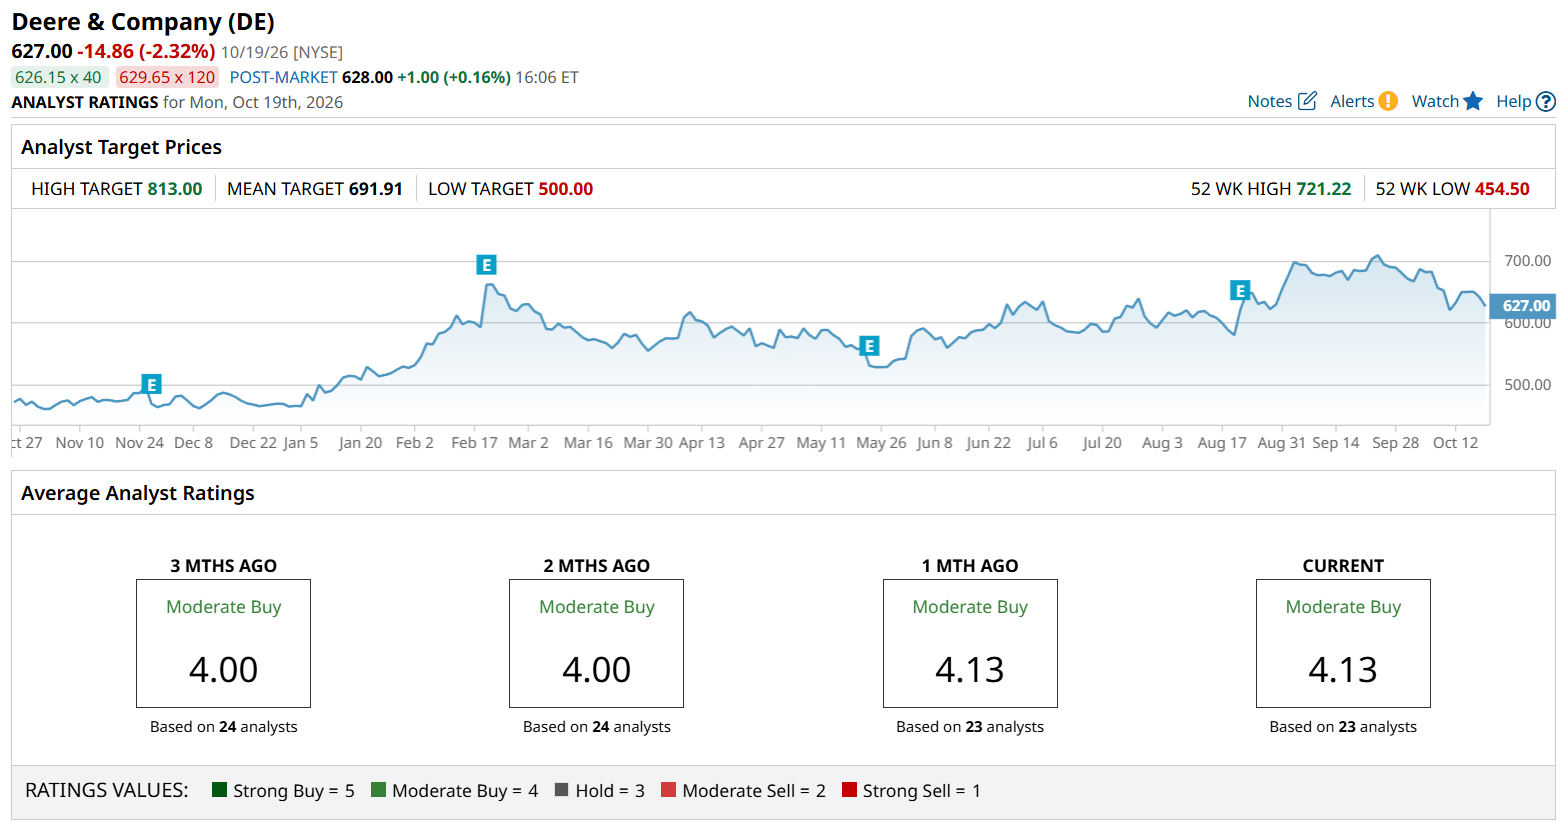
Deere gets a similar assessment, with 23 analysts also rating it a “Moderate Buy.” However, its upside potential is much lower at around 30% if its high target price is reached.
Verdict
Industrial companies aren't just about today's earnings, but about how well they can adapt and position themselves for the future. That's where I think Caterpillar has an edge. Its growing role in data centers gives investors something to look forward to. With already stronger financial results, a lower valuation, and room to increase its dividend, Caterpillar makes a more convincing case.
On the date of publication, Rick Orford did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.