
Construction Partners (ROAD) Acquisition In Florida Puts Its Valuation Story To The Test
Acquisition of S.E. Cline Puts Florida Growth in Focus
Construction Partners (ROAD) has agreed to acquire S.E. Cline Construction, a Florida based commercial site development and underground utility contractor, in a move centered on the Interstate 95 corridor.
The transaction folds roughly 60 employees and a rail served, permitted hot mix asphalt plant site in Bunnell into the existing C.W. Roberts Contracting platform. This gives Construction Partners a broader footprint for roadway and asphalt work in the region.
For investors watching Construction Partners, the share price has pulled back with a 30 day share price return of down 11.8% and a 90 day share price return of down 20.2%. Yet the 3 year total shareholder return above 100% signals longer term momentum that still shapes how this acquisition is being read for future growth potential and risk.
Scan for other construction and infrastructure stocks showing similar acquisition driven expansion using the curated list of solid balance sheet and fundamentals (25 results).
Bulls see Construction Partners using S.E. Cline to deepen a high growth corridor, while bears point to a sharply weaker share price. Which side does current valuation actually support as you weigh ROAD today?
Most Popular Narrative: 41.7% Undervalued
On the most followed view, Construction Partners carries a fair value of about $142.57 against a last close of $83.17, which frames the current pullback as a valuation gap rather than a broken story.
Active pursuit of acquisitions and greenfield moves, such as Ellsworth Construction in Oklahoma, Lone Star Paving in Texas, Four Star Paving in Nashville, GMJ Paving and Vulcan assets in Houston, P&S Paving and Roads, Inc. in Florida, and Asphalt Express, has added over US$400m of acquisitive revenue carryover into FY2027 and expanded Construction Partners' reach in fast-growing metros. This can compound revenue and adjusted EBITDA as these operations mature.
See why 9 investors see Construction Partners as 42% undervalued.
Result: Fair Value of $142.57 (UNDERVALUED)
Still, the narrative around Construction Partners breaks quickly if public infrastructure funding softens, or if recent acquisitions drag on margins rather than support them.
Find out about the key risks to this Construction Partners narrative.
Another Take on Construction Partners Valuation
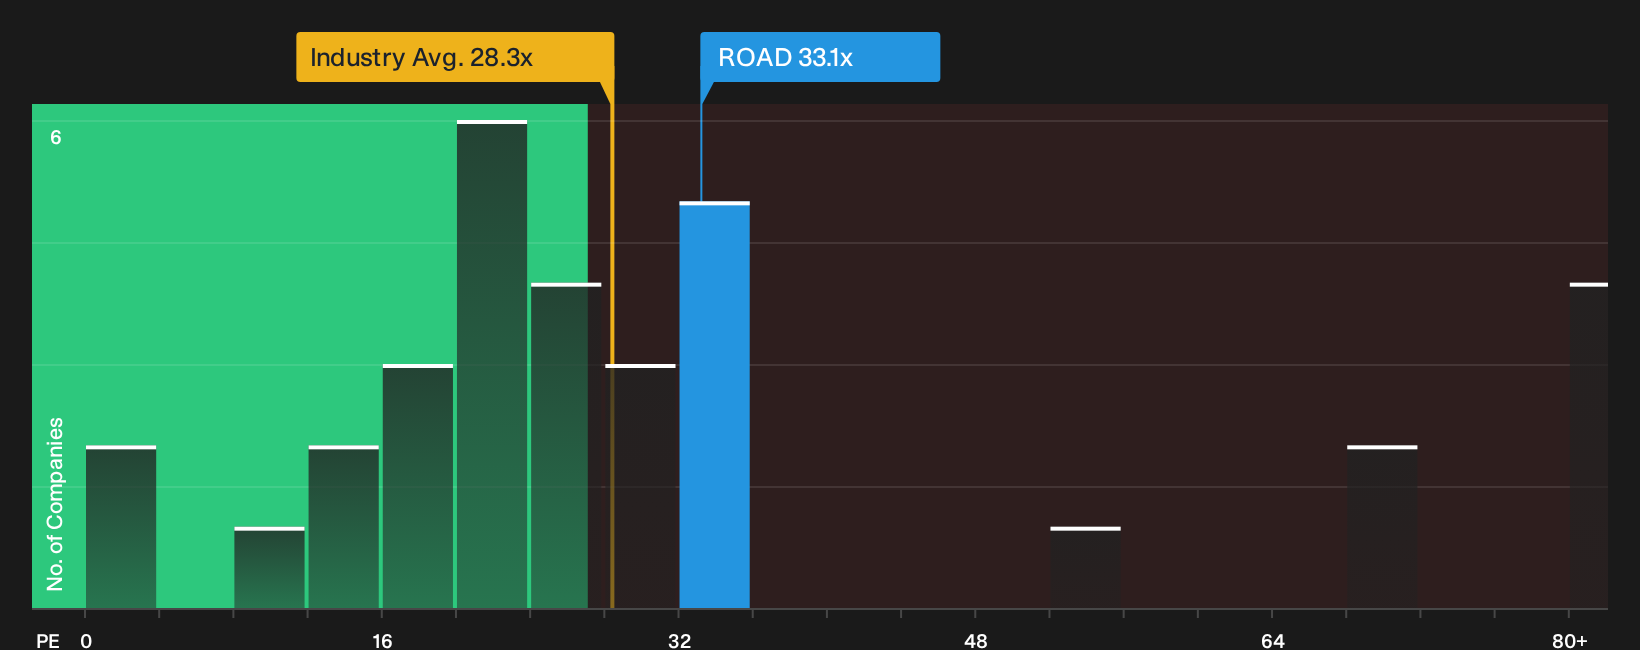
That 41.7% undervaluation story leans on analyst fair value and future earnings. A simple earnings multiple paints a tougher picture. Construction Partners trades on a P/E of 33.1x, while the US Construction group sits at 27.6x and peers average 29.1x, with a fair ratio estimate of 32.6x.
So the stock screens slightly expensive on this yardstick, even before you factor in the recent 1 year share price decline of 31.9%. Which lens do you trust more when you decide how much of the upside narrative to price in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Construction Partners valuation and sentiment only matter if you use them. Act while the data is fresh and weigh both sides through the 4 key rewards and 1 important warning sign
Looking for more Construction Partners sized ideas?
You have the story for Construction Partners. Now widen your watchlist with a few focused screens that surface different types of opportunities before they move.
- Target better value potential and filter for quality at a discount using the 35 high quality undervalued stocks, which narrows the field to financially stronger candidates.
- Prioritize resilience first and load up a 32 resilient stocks with low risk scores that tilts toward steadier balance sheets and more durable business profiles.
- Hunt for early stage opportunities and scan a 12 elite penny stocks with strong financials that highlights smaller companies with stronger financial underpinnings than the usual speculative picks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com