
Is Nucor (NUE) Reasonable on Cash Flow After Its $105 Million Expansion?
Nucor has ridden a powerful multi year upswing in its share price, and the key issue now is whether the current market tag lines up with the cash the business is expected to generate. With such a strong run behind the stock, investors are increasingly asking how its cash flows stack up against today's valuation.
- Nucor has returned 156.3% over the past 5 years, which puts real pressure on the current share price to be supported by the company’s underlying cash generation.
- The planned US$105 million expansion of the Nucor Towers & Structures facility in Indiana, along with 100 additional jobs and more automation, can influence both future cash inflows and the timing of returns on that extra invested capital.
- If you'd rather focus on earnings, this one's for you. See why Nucor's 20.6x P/E tells a different valuation story.
The stock's next move may depend on whether Nucor's projected cash flows are sufficient to justify where the shares trade today.
If you want to test the same cash flow question across a wider field than Nucor, run the numbers across the 35 high quality undervalued stocks.
Does Nucor Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses Nucor's own cash generation as the anchor, then projects how that could build over time. Over the latest twelve months the group produced roughly $1.16b of free cash flow, and the forecast path assumes that annual cash flows grow from that base rather than shrink. The projections step up into multi billion dollar territory by the early 2030s, which is closer to what you would expect from a mature industrial operation than a hyper growth story.
The DCF output suggests Nucor's estimated intrinsic value sits substantially above the current share price of $260.73. The planned $105 million expansion of the Nucor Towers & Structures facility in Indiana, with extra capacity and automation, fits with those higher long term cash flow assumptions. It points to more capital being put to work in areas tied to power infrastructure demand. That gap between the DCF estimate and the market price is where investors need to decide whether the cash flow path looks realistic or too optimistic for their comfort. Find out what Nucor could be worth using our Discounted Cash Flow (DCF) estimate.
The Nucor Narrative: What Would Justify Today's Price?
Nucor's valuation puzzle only really comes into focus once you spell out the story that would need to play out for the current price to look either conservative or stretched. That is what Simply Wall St Narratives on the Community page aim to do. Each narrative links its number to a clear view on where growth, margins and key risks could move next, giving you a reference point you can revisit as fresh information comes through.
Community views on Nucor split between a cash flow story tied to new projects and a worry that fresh capacity meets cooler demand.
Bull case: 8% undervalued
"Nucor's multi year capital program of roughly US$15b to US$20b, with several mills and downstream assets already EBITDA positive, is moving from the build phase toward cash generation…"
Discover why this Narrative puts Nucor at 8% undervalued.
Bear case: 9% overvalued
"As the West Virginia sheet mill moves through commissioning and into an early 2027 shipment ramp, a pessimistic outcome is that new capacity arrives into a flat domestic sheet market…"
Explore why this Narrative puts Nucor at 9% overvalued.
Nucor’s price is only one clue in the bigger decision
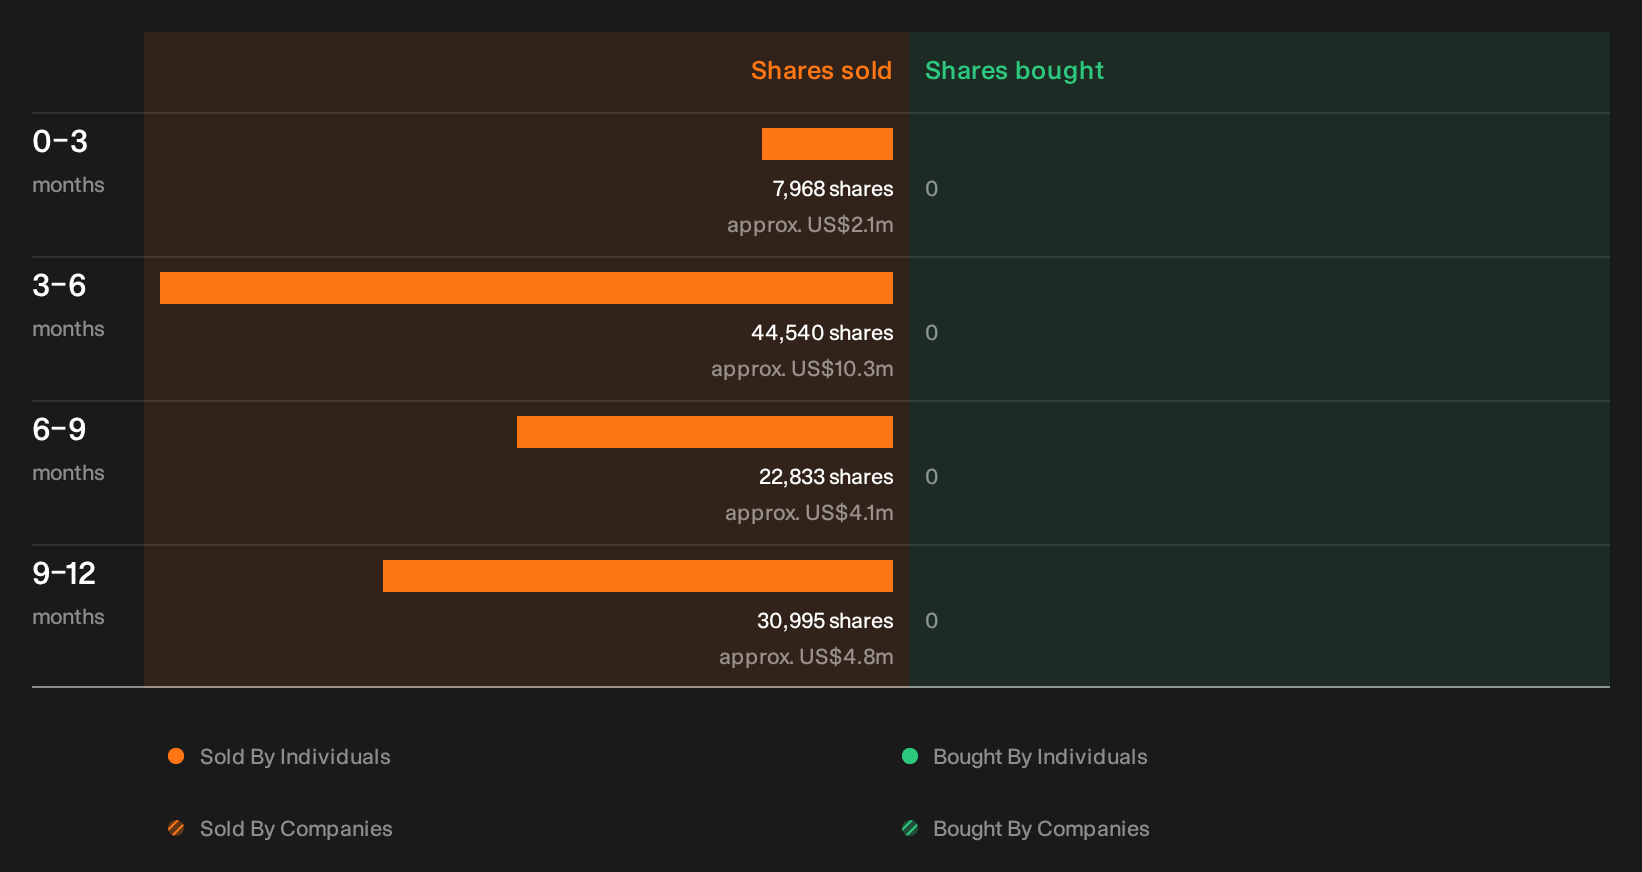
Valuation work gets you part of the story, but recent trades by Nucor insiders, who they are, what they sold and what that might signal, are the extra layer you need to inspect. See the recent insider selling flagged for Nucor.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com