
Sandvik (OM:SAND) Looks Undervalued, Can Mining Momentum Justify More Upside?
Sandvik (OM:SAND) has drawn investor attention after its latest share price of SEK 356.70. This has prompted a closer look at how the engineering group’s recent returns line up with its earnings profile.
Recent trading has been choppy, with the 7 day share price return down 2.43% and the 30 day share price return down 3.57%. However, Sandvik still shows an 18.19% year to date share price return and a 29.65% 1 year total shareholder return, suggesting momentum has cooled in the short run while the longer record remains strong.
Compare Sandvik’s recent run with peers by scanning a hand picked set of industrial and capital goods stocks in the list of solid balance sheet and fundamentals (202 results).
Given Sandvik’s strong multi year shareholder record but softer recent swing, the real issue now is whether today’s price still offers an attractive risk reward for new buyers.
Most Popular Narrative: 9% Undervalued
On the most followed view of Sandvik, a fair value of SEK 390.90 sits above the latest SEK 356.70 close. This puts the current share price at a clear discount and makes the future earnings path the key focus.
Sandvik is benefiting from strong market momentum in its Mining segment, with order intake for the business reaching over SEK 20b in Q2 2026 and mining aftermarket orders growing double digit for several quarters, which could support future revenue and earnings as high production rates and aging fleets keep driving equipment and service demand.
See why 21 investors see Sandvik as 9% undervalued.
Result: Fair Value of SEK390.90 (UNDERVALUED)
Still, the Sandvik story can unravel if weakness in general engineering and automotive drags on Cutting Tools, or if Rock Processing margins stay stuck below management ambitions.
Find out about the key risks to this Sandvik narrative.
Another View on Sandvik’s Valuation
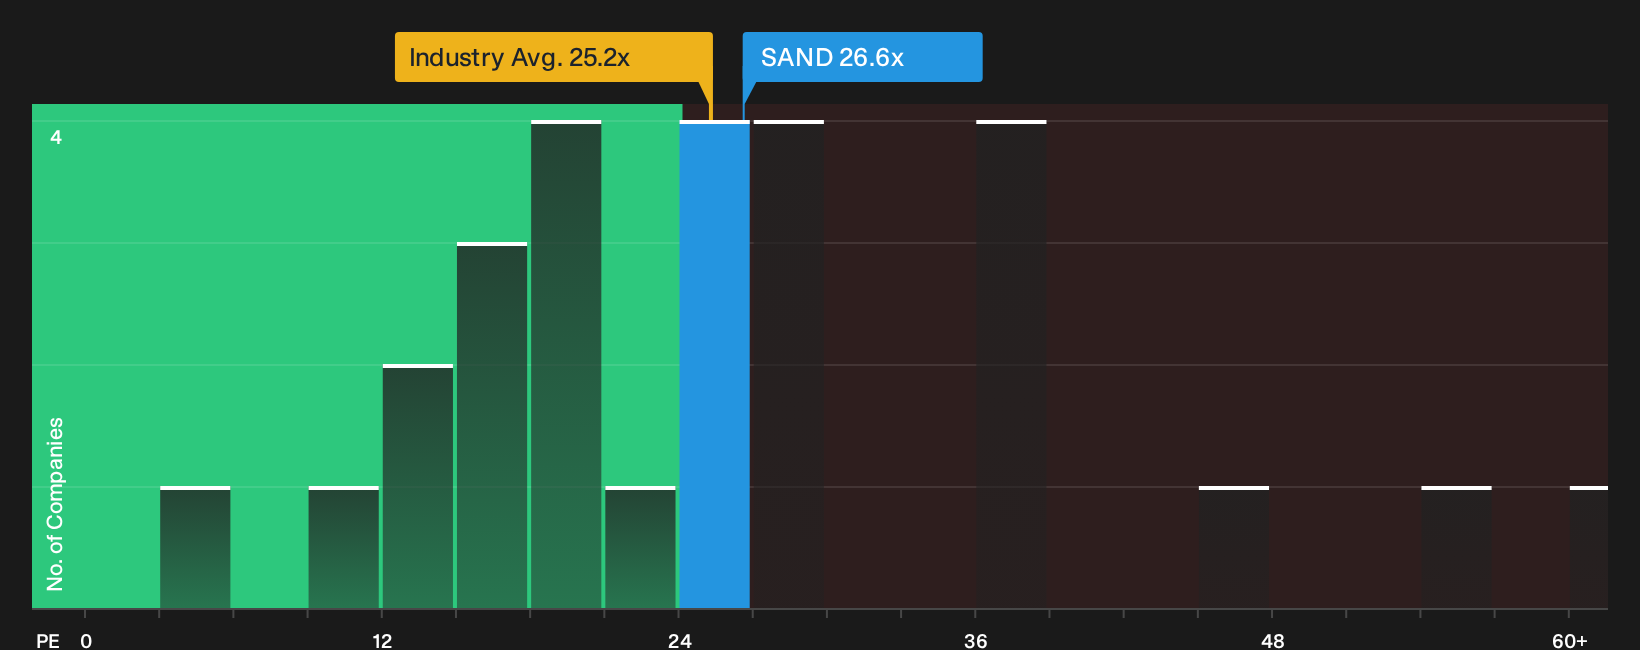
The first take leans on fair value estimates and analyst targets that point to Sandvik trading below intrinsic value. A different picture appears when using the P/E ratio. The stock trades on 26.6x earnings, higher than the Swedish Machinery industry on 25.3x, yet below a fair ratio of 32.3x indicated by regression analysis. That mix of rich pricing versus the sector but a discount to the fair ratio raises a simple question. Is this a premium you are comfortable paying for Sandvik, or a gap you expect the market to close?
For a closer look at how that earnings multiple stacks up against peers and where the fair ratio could move, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sandvik so far, right. If you want to move past headlines and sentiment, you can evaluate the potential yourself by starting with the 3 key rewards.
Looking for more investment ideas beyond Sandvik?
If you stop at Sandvik, you risk missing other opportunities. Put a shortlist together now so you are not reacting after the next big move.
- Target potential bargains by scanning for companies that combine quality fundamentals with prices below intrinsic estimates using the 198 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer higher yields and consistent payouts through the 221 dividend fortresses.
- Protect your downside by focusing on resilient businesses with sturdier financial profiles in the 230 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com