
Is Kansai Electric Power Company (TSE:9503) Fairly Valued Following Mihama Unit 3 Restart Plans?
Kansai Electric Power Company (TSE:9503) moved back into focus after confirming repairs and restart preparations for Mihama Nuclear Power Station Unit 3, following a September water leak traced to a past maintenance installation error.
The Mihama update lands after a mixed stretch for Kansai Electric Power Company, with the share price at ¥2,719.5 and a 90-day share price return of 15.65%, but a 30-day share price return that declined 6.40% as investors reassessed reactor downtime and fresh bond issuance against a 23.61% 1-year total shareholder return and 197.28% 5-year total shareholder return. This suggests momentum that has cooled in the near term while remaining strong over longer periods.
Compare Kansai Electric Power Company with other grid and generation plays by scanning a curated group of 43 power grid technology and infrastructure stocks that are also reacting to major operational updates and capital plans.
Kansai Electric Power Company trades at an 8.8% discount to analyst targets yet carries an implied 8.5% premium to some intrinsic estimates. After the Mihama incident and fresh bond issuance, is that caution misplaced or overdue?
Most Popular Narrative: 8% Undervalued
Kansai Electric Power Company is trading at ¥2,719.5 against a widely followed fair value estimate of ¥2,958, which frames today’s price as a discount that still embeds meaningful execution risk.
The plan to invest a cumulative ¥15t across maintenance and growth areas by 2040, with ¥2.5t earmarked over the next 3 years, positions the group to support rising power demand and could lift group revenue and operating earnings as new assets come onstream.
See why 1 investors see Kansai Electric Power Company as 8% undervalued.
The prevailing narrative leans on that long term ¥15t program, a 3.1% assumed annual revenue lift and a 7.6% forecast profit margin, all discounted at 5.5%, to arrive at a ¥2,958 fair value. That sits above the current ¥2,719.5 share price, while still building in a decline in earnings to ¥345.8b by around 2029 and a higher implied P/E multiple than the wider JP Electric Utilities group.
Result: Fair Value of ¥2,958 (UNDERVALUED)
Still, the narrative can crack if nuclear outages linger longer than expected, or if planned asset sales and recycling fail to deliver the ¥380b plus in cash.
Find out about the key risks to this Kansai Electric Power Company narrative.
Another View On Kansai Electric Power Company’s Valuation
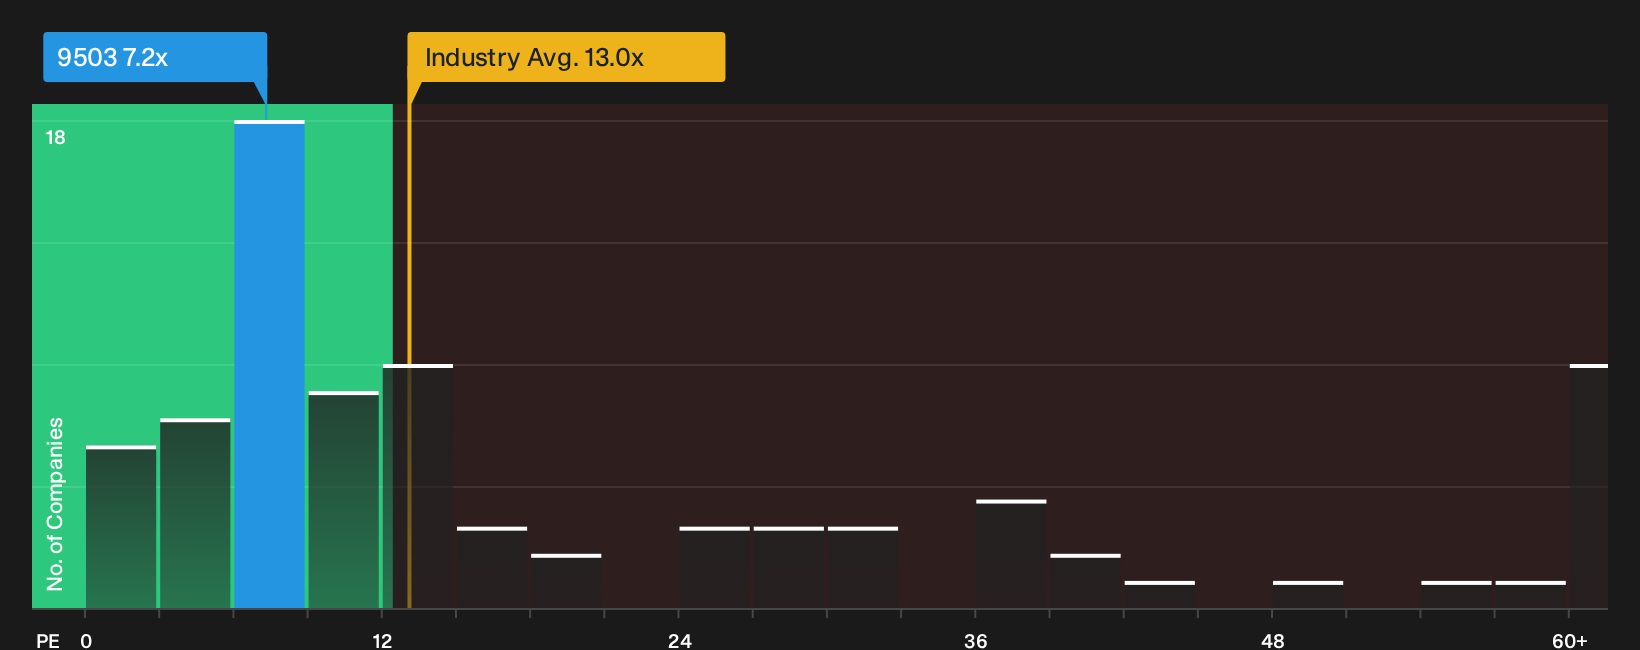
The fair value story looks different once price multiples are used instead of the narrative model. Kansai Electric Power Company trades on a P/E of 7.2x, above the 6.6x peer average, yet below the Asian Electric Utilities group on 13x and a fair ratio of 10.9x. That mix highlights both valuation risk against peers and a possible re rating path toward the fair ratio if sentiment shifts, so which side matters more for you right now is a key question.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through the mixed sentiment around Kansai Electric Power Company, you can see both concern and optimism pulling in opposite directions. Act while the data and debate are fresh in your mind and review the 2 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Kansai Electric Power Company?
If Kansai Electric Power Company has your attention, do not stop there. Broaden your watchlist now so you do not miss the next opportunity setting up.
- Target undervalued potential by scanning the 13 high quality undervalued stocks that may offer a margin of safety alongside solid business fundamentals.
- Stack potential income streams and review the 30 dividend fortresses that focus on higher yields supported by underlying cash generation.
- Prioritise resilience and capital protection by assessing the 20 resilient stocks with low risk scores built around companies with sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com