
Pro Medicus (ASX:PME) Lands Billings Clinic Contract, Is The Stock Fully Priced?
Pro Medicus (ASX:PME) has signed a new 7 year A$24 million imaging software contract with Billings Clinic, putting long-term revenue visibility in sharper focus and prompting investors to reassess what they are willing to pay for the stock.
Recent trading shows that this new Billings Clinic deal lands in the middle of a mixed run for Pro Medicus. A 7 day share price return of 8.59% and a 30 day gain of 6.11% contrast with a year to date share price decline of 19.18% and a 1 year total shareholder return that has fallen 37.22%, while the 3 and 5 year total shareholder returns of 133.60% and 236.19% keep the long term story firmly positive.
Scan how Pro Medicus compares to other healthcare and AI imaging players by reviewing our hand picked 5 healthcare AI stocks that are reacting to similar long-term contract momentum.
Pro Medicus looks like a high quality healthcare software franchise, but the recent contract win and share price rebound raise a sharper question. Are you paying a fair price for that strength today?
Most Popular Narrative: 11% Undervalued
The prevailing narrative pegs Pro Medicus at a fair value of A$202.47, compared with the last close of A$179.93. This puts the focus squarely on whether investors accept the growth assumptions behind that gap.
The continued shift of U.S. health care systems toward large integrated delivery networks and Tier 1 academics, where Pro Medicus is already deeply embedded, supports ongoing contract wins and renewals. This expands high visibility, annuity style transaction revenue and drives sustained earnings growth.
See why 24 investors see Pro Medicus as 11% undervalued.
Result: Fair Value of A$202.47 (UNDERVALUED)
Still, the Pro Medicus story can crack if U.S. hospital budgets tighten or a rival undercuts its high pricing on major long term contracts.
Find out about the key risks to this Pro Medicus narrative.
Another View: Pro Medicus On Earnings Multiples
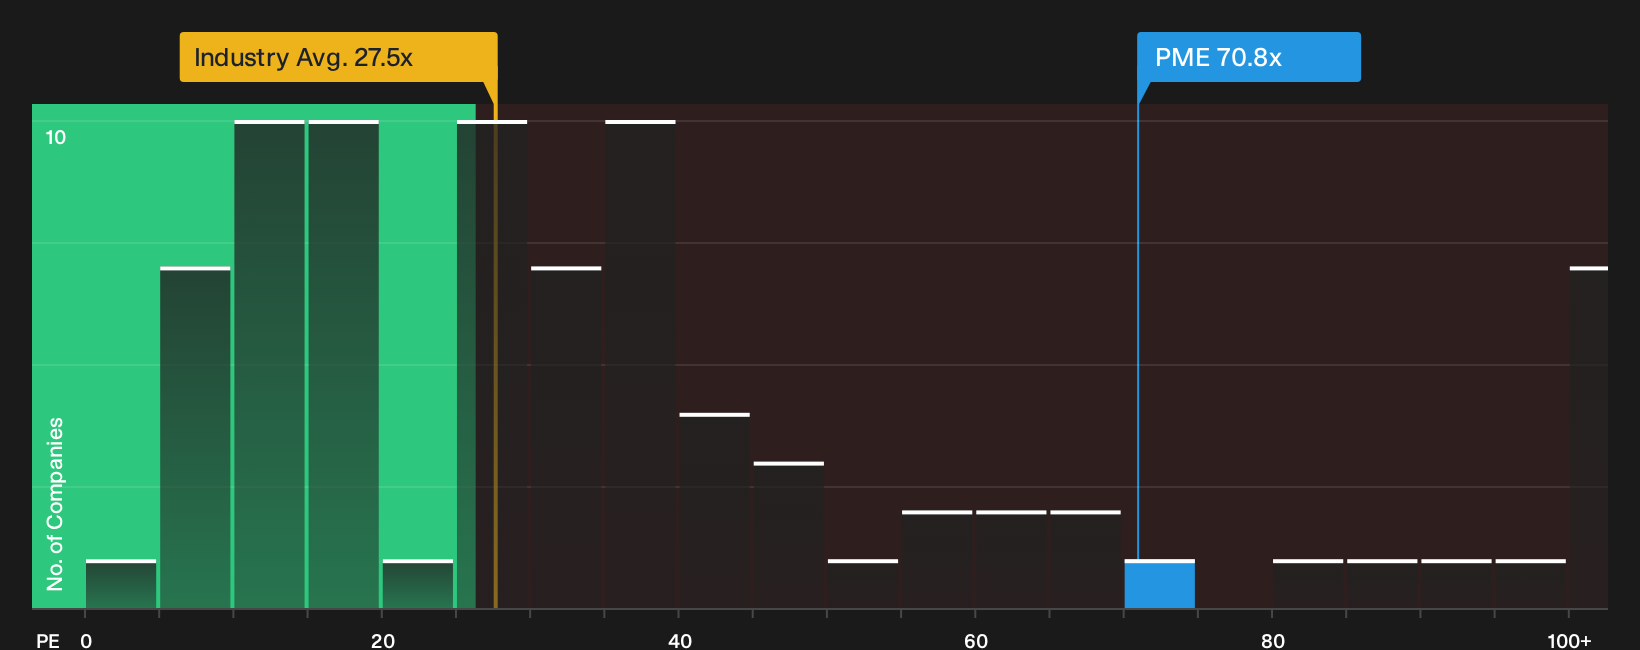
The story shifts when you look at Pro Medicus through its P/E. The shares trade at 70.8x earnings, while the fair ratio is 35.8x, the peer average is 44.4x and the broader Global Healthcare Services group is at 27.5x. That is a rich premium. Is that multiple really the risk profile you want to own?
For a closer look at how those earnings multiples compare with what the fair ratio suggests the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Pro Medicus can make the story feel pulled in two directions, so consider the situation while sentiment is split and test the data yourself with 2 key rewards and 1 important warning sign.
Looking for more Pro Medicus style investment ideas?
You have seen how Pro Medicus stacks up. Now put that context to work by testing fresh ideas that might better fit your risk and return preferences.
- Target resilient cash generators by running a pass on companies in the 3 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable.
- Prioritize staying power and sleep at night potential with the 6 resilient stocks with low risk scores and focus on businesses screened for lower overall risk scores.
- Hunt for tomorrow's quiet overachievers by using the 15 high quality undiscovered gems to surface lesser known stocks with strong underlying financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com