
Ryman Hospitality Properties (RHP) Dividend Story Keeps Fair Value In Focus
Recent attention on Ryman Hospitality Properties (RHP) has centered on its higher annualized dividend of US$1.20 per share, a 3.2% increase from last year, and a 3.81% yield that income-focused investors are watching closely.
Recent trading has been strong for Ryman Hospitality Properties, with the latest share price at US$126.90 and a 7 day share price return of 3.63%. The year to date share price return of 32.91% and 1 year total shareholder return of 50.34% point to momentum that has built over time rather than faded.
Capture this momentum story around Ryman Hospitality Properties, then broaden your income ideas with a curated 8 dividend fortresses that targets yield while also considering financial strength.After a sharp move to US$126.90, Ryman Hospitality Properties now trades between a roughly 10% discount to analyst targets and a much wider intrinsic value gap. Where does fair value realistically land in that spread?
Most Popular Narrative: 9% Undervalued
On the most followed view, Ryman Hospitality Properties is worth about $139.79 per share, which sits above the last close at $126.90 and frames the recent price strength as still short of that reference point.
Recent acquisitions and ongoing capital investments, now including the approximately US$1.38b Grande Lakes Orlando transaction alongside projects such as meeting space upgrades at Gaylord properties and resort enhancements, extend the earlier thesis that Ryman Hospitality Properties can benefit from renewed appetite for large scale experiential travel and gatherings by adding more room, meeting and amenity capacity that can support revenue growth and future cash flow.
See why 7 investors see Ryman Hospitality Properties as 9% undervalued.
Result: Fair Value of $139.79 (UNDERVALUED)
Still, the Ryman Hospitality Properties story can change quickly if the US$1.38b Grande Lakes Orlando deal underdelivers, or if heavy 2026 capex tightens future dividend flexibility.
Find out about the key risks to this Ryman Hospitality Properties narrative.
Another View on Ryman Hospitality Properties Valuation
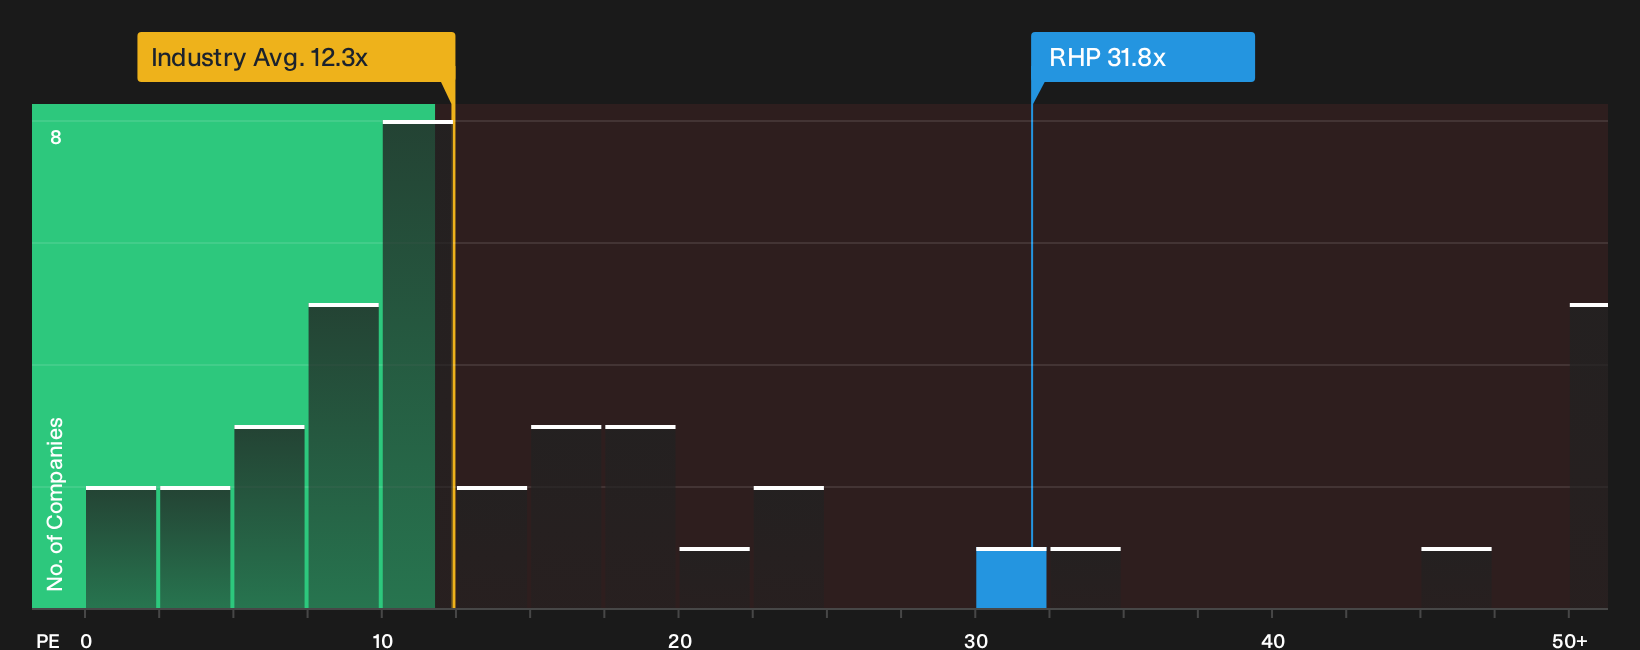
On simple earnings multiples, Ryman Hospitality Properties does not look cheap. The shares trade on a 31.8x P/E, above both the US peer average of 27.8x and the Global Hotel and Resort REITs group at 12.5x, although below its own fair ratio estimate of 41x. This may reflect either a quality premium or potential valuation risk.
To see how this earnings multiple compares with the scenario work already discussed, and how it could affect your margin of safety over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Ryman Hospitality Properties so far. If you want to move before sentiment shifts again, weigh the potential benefits against the weak spots through the 3 key rewards and 2 important warning signs
Looking for more income ideas beyond Ryman Hospitality Properties?
Ryman Hospitality Properties might fit part of your plan, but a broader watchlist can give you more choices when conditions or expectations change.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength before yield or headlines grab attention.
- Hunt for potential mispriced opportunities by running through a 35 high quality undervalued stocks that highlights businesses where fundamentals and current pricing may be out of sync.
- Spot companies that the crowd may be overlooking by reviewing a 20 high quality undiscovered gems focused on quality metrics rather than hype.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com