
Walmart (WMT) Stock Looks Above Fair Value On Current Earnings
Walmart has delivered strong returns in recent years, and the stock now trades with fresh momentum after a run of positive headlines. With that backdrop, the live question for investors is whether the current share price is adequately supported by the retailer's earnings power.
- Over the past 5 years, Walmart has returned 152.6%, which raises the question of whether today’s valuation still lines up with what the business earns.
- Recent moves to raise more than US$6b in bond funding and invest in automation, e-commerce and international platforms like Flipkart can affect future profit margins and the timing of cash flows that matter for earnings-based valuation work.
- The analysts covering Walmart have run their own numbers. See what analysts think Walmart's shares could be worth.
The issue now is whether Walmart's current share price, after that multi year run and recent developments, is justified by its earnings profile.
If you want a wider watchlist anchored on the same earnings questions that surround Walmart right now, a focused stock screen built around 35 high quality undervalued stocks is a clean next step.
Does Walmart Look Pricey on Earnings?
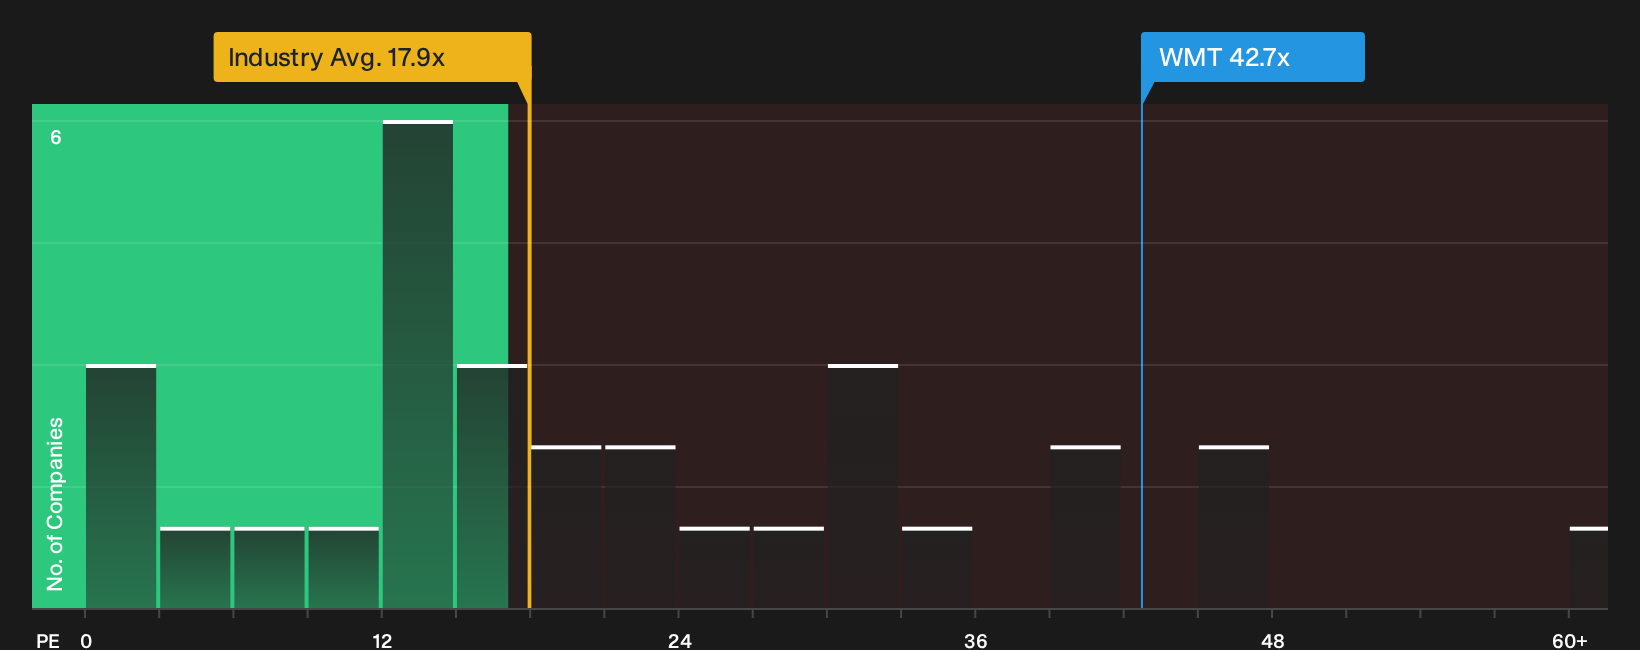
P/E suits Walmart because earnings are still the primary yardstick most investors watch for a mature retailer. On that metric, the stock trades on a P/E of 42.7x, compared with a Consumer Retailing industry average of 17.9x and a peer group around 23.8x. That is a clear premium to both sector norms and closer large cap peers, so buyers are paying a higher price for each dollar of current profit.
Because the recent bond funded automation and e commerce push has sharpened expectations, the market is valuing Walmart above the multiple implied by a more tailored fair ratio that blends its size, margins, sector and risk profile. On this framework, the shares screen as overvalued. Despite the renewed enthusiasm around Flipkart, automation and higher margin services, the current P/E still bakes in a richer earnings tag than those benchmarks suggest. Explore the numbers behind Walmart's P/E valuation.
The Walmart Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Walmart's valuation puzzle leaves off and spell out which paths for growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today. Each scenario links its number to a specific view on how Walmart's expansion, margins and risk profile might evolve. This gives you something concrete to revisit as new information comes through.
One of the top community narratives on Walmart: 6% undervalued
"The main factor that has to go right is the continued growth and profitability of higher margin alternative profit pools such as advertising…"
Discover why this Narrative puts Walmart at 6% undervalued.
Before acting on Walmart's valuation, there is one more question to ask
Price tags on earnings only tell part of the story, because the people setting Walmart's priorities and how they are rewarded can pull results in very different directions. See who runs Walmart and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com