
KKR (KKR) Stock Looks Overvalued After Its Recent Deal Moves
KKR has pulled back sharply over the past year, yet over a 3 year window the stock still shows a strong positive return. This puts fresh focus on whether the current US$87 share price lines up with the earnings that underpin it. With investors digesting new deals, portfolio moves and policy shifts, the key issue now is how much of that activity is already reflected in what the market is willing to pay for KKR's profits.
- Over the last 3 years KKR has delivered a gain of 60.7%, which puts long term performance on the line as you weigh what the present earnings justify.
- The decision to expand its U.S. renewables joint venture with TotalEnergies and to sell Infinity Transportation for about US$2.9b can reshape the mix and timing of fee income and investment gains that ultimately feed into KKR's earnings power.
- Your read on KKR is one view; the desks covering it have another. See what analysts think KKR's shares could be worth.
The issue now is whether KKR's current valuation is adequately supported by its earnings given that recent share price retreat and the stream of new deals and disposals.
KKR's mix of data centers, renewables and infrastructure raises fair questions about whether the US$87 share price is earning its keep. A focused stock screen can give you a second reference point through 55 AI infrastructure stocks
Has KKR Run Too Far on Earnings?
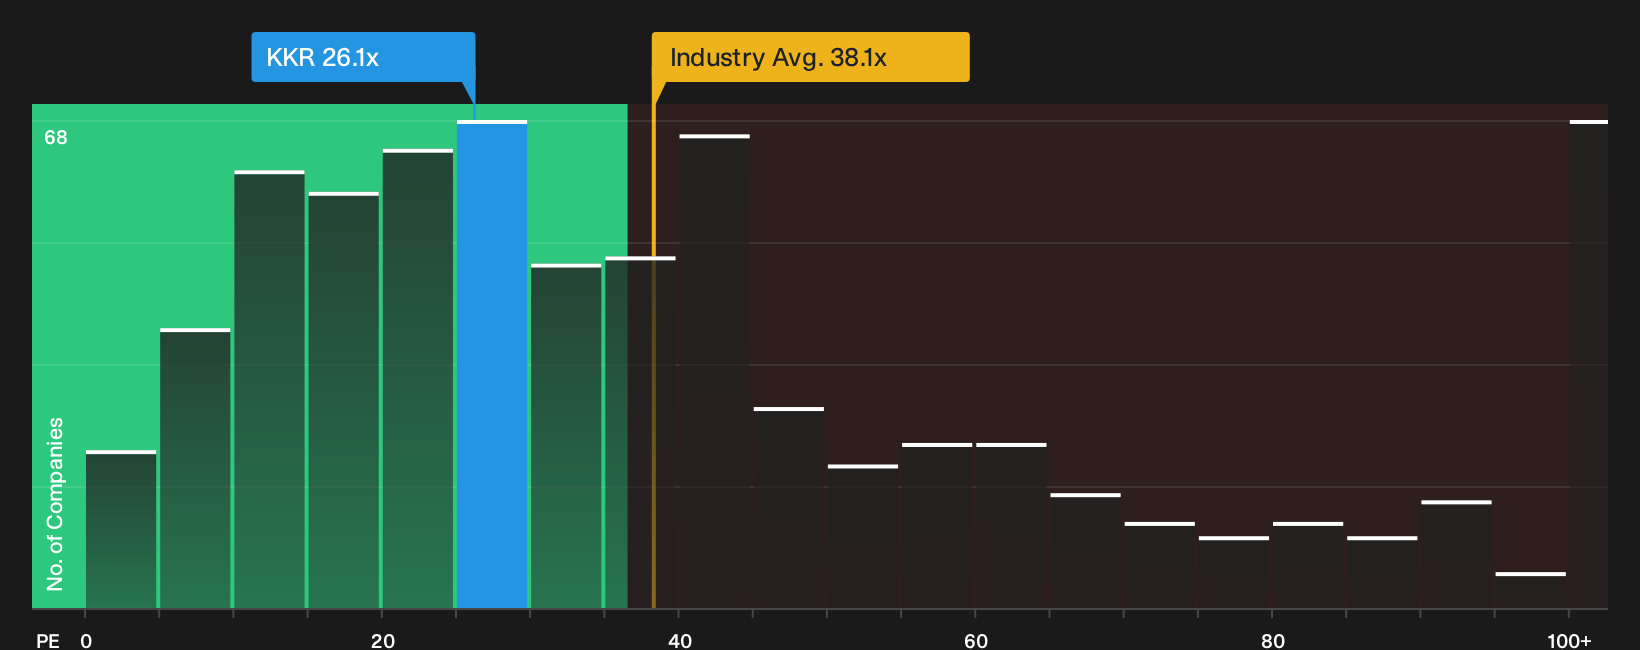
The P/E ratio is a reasonable way to frame KKR because earnings from management fees and investment income are central to how holders get paid over time. On this measure, KKR trades on about 26.1x earnings, which is above both the Capital Markets industry average of roughly 38.1x and a peer band closer to 15.9x. That puts the stock in a zone where you are paying a clear premium to similar alternative asset managers, but not to the broader industry composite that includes very different business models.
The fair P/E level implied by the valuation model, which blends KKR specific factors like profitability, risk and size, sits below where the shares change hands today, so the stock screens as overvalued on this yardstick. Because the P/E already embeds expectations around deals such as the expanded U.S. renewables joint venture with TotalEnergies, you would need to judge whether those projects and other infrastructure pushes justify paying up relative to both peers and the model’s estimate. Explore the numbers behind KKR's P/E valuation.
The KKR Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the KKR valuation puzzle leaves off and explain which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price, all housed on the Community page. Each Narrative treats KKR's fair value as a specific, testable viewpoint on the business that you can track over time rather than a one off snapshot.
Community views on KKR are split between those who see more upside in the data center and private markets engine and those who think recent gains already reflect that story.
Bull case: 31% undervalued
"Large embedded unrealized carried interest ($17B+ in gains, a record high) and a highly marked-up portfolio mean KKR is well-placed for significant future monetization activities..."
Discover why this Narrative puts KKR at 31% undervalued.
Bear case: roughly fairly valued
"KKR no solo gestiona activos; empieza a comportarse parcialmente como conglomerado inversor..."
Explore why this Narrative puts KKR at roughly fairly valued.
For KKR, the price tag is only half the story
Before you treat KKR as just a set of earnings multiples and deal headlines, it is worth asking who is steering the ship and how their pay packets line up with your interests. See who runs KKR and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com