
Is Automatic Data Processing (ADP) Fully Valued Following Its Latest Dividend Increase?
Automatic Data Processing (ADP) recently increased its dividend by roughly 10%, a move that puts fresh attention on the stock’s income profile, payout coverage, and sensitivity to interest rate shifts.
Recent trading has been favorable for Automatic Data Processing, with the share price delivering a 16.57% 3‑month share price return and a 5.83% 1‑month share price return. The 5‑year total shareholder return of 47.16% indicates that momentum has built gradually over a longer horizon.
Spot income momentum like Automatic Data Processing’s dividend move, then widen your watchlist with a curated set of resilient payers in the 8 dividend fortresses.After a fresh dividend lift and a strong recent run, Automatic Data Processing is not obviously cheap or stretched on the surface. Is this a moment to pay up for quality, or does patience win on entry price?
Most Popular Narrative: Fairly Valued
Automatic Data Processing closed at $287.03, almost exactly in line with the most followed narrative fair value of $287.60, so the story really hinges on how durable the underlying growth drivers prove to be.
Adoption of Next Gen products such as Lyric HCM and Workforce Now Next Gen, together with continued uptake of global payroll and WorkForce Suite, is now showing in Employer Services bookings of more than US$2.2b in fiscal 2026 and a 94% rise in live Lyric clients. This supports future revenue and earnings growth as these contracts are implemented and ramp into the income statement.
See why 115 investors see Automatic Data Processing as 0% undervalued.
Result: Fair Value of $287.60 (ABOUT RIGHT)
Still, the fair value story around Automatic Data Processing can break if PEO margins stay under strain or if new AI powered HR platforms pressure pricing and growth expectations.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: What Multiples Say About Automatic Data Processing
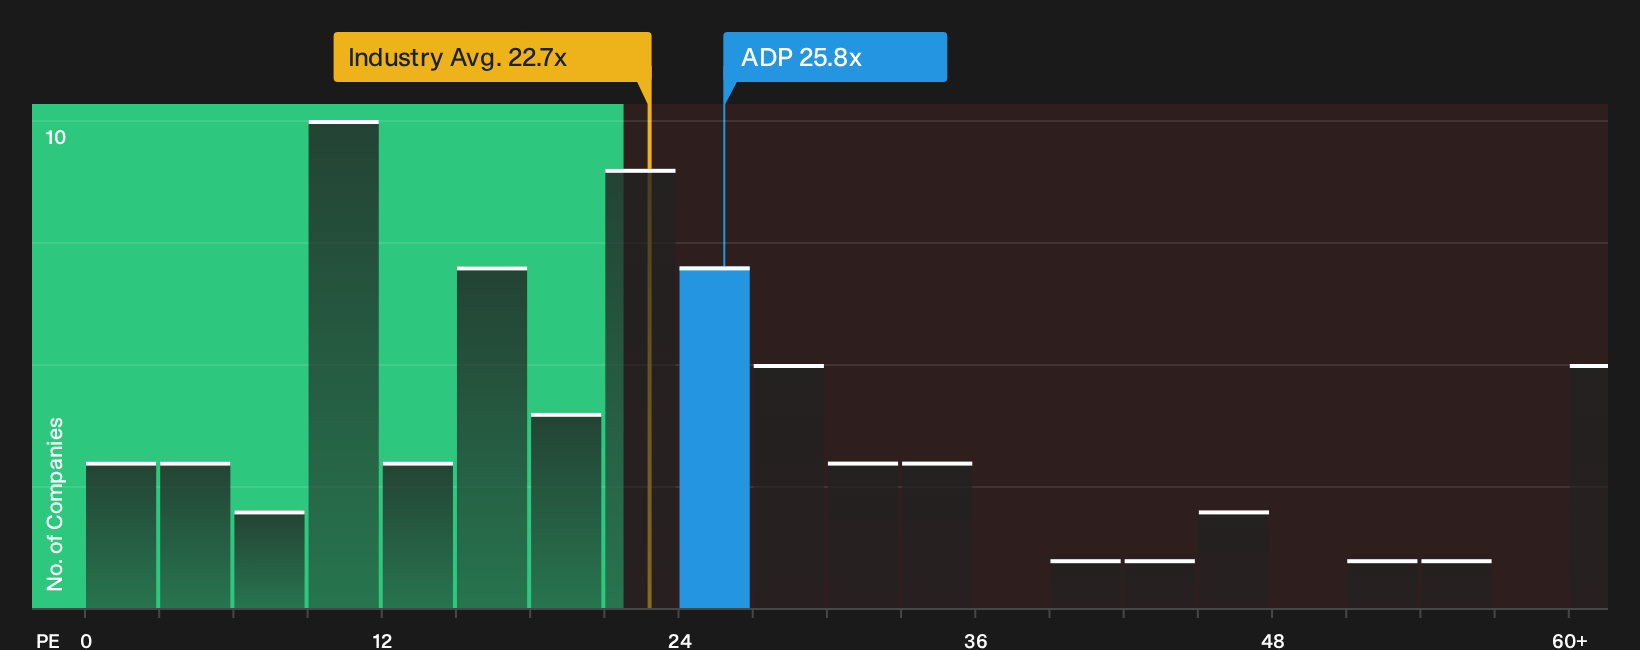
On a simple earnings yardstick, Automatic Data Processing screens as slightly expensive. The stock trades on a P/E of 25.8x, compared with a fair ratio estimate of 25.7x, a peer average of 22.1x and a US Professional Services industry level of 22.7x.
That gap is not extreme, yet it means you are paying a premium for quality, consistency and returns on equity that are already well known. The key consideration is whether you are comfortable paying above both peers and the fair ratio for a business where growth expectations are solid rather than rapid. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Automatic Data Processing so far leans balanced, with investors weighing quality against entry price. Act quickly, review the underlying metrics, and then decide if the upside case stacks up after checking the 3 key rewards
Looking for more investment ideas beyond Automatic Data Processing?
If Automatic Data Processing looks fairly priced to you today, broaden your opportunity set and let structured stock ideas guide your next move.
- Target steadier potential outcomes by focusing on resilient businesses with strong financial footing through the 32 resilient stocks with low risk scores.
- Hunt for mispriced quality by scanning companies that pair solid fundamentals with appealing valuations using the 20 high quality undiscovered gems.
- Stack potential income streams by zeroing in on reliable payers with robust yield characteristics in the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com