
Howmet Aerospace (HWM), What Is Behind The Fresh Attention?
Howmet Aerospace (HWM) just paired a fresh earnings upgrade with two concrete shareholder actions: a 14 cent dividend declaration and an upcoming 1 for 52 stock split, putting its recent performance firmly in focus.
Recent Q2 results that beat expectations and prompted higher full year revenue and EBITDA guidance have not stopped near term volatility, with the share price down 21.1% over the past 90 days but still posting a 14.5% total shareholder return over the last year and a very large five year total shareholder return that suggests long term momentum remains intact, even as some investors reassess near term risk and growth expectations around the current US$220.03 level.
Scan how Howmet Aerospace fits into the wider aerospace story by lining it up against a handpicked set of list of solid balance sheet and fundamentals (25 results) that have been screened for financial resilience and fundamentals.
Howmet Aerospace has rallied hard over five years, then slipped 21.1% in just three months. Are you now looking at fresh upside, or has most of the easy gain already played out at about US$220 a share?
Most Popular Narrative: 32% Undervalued
The most followed narrative on Howmet Aerospace pegs fair value at about $324.55, well above the recent $220.03 close. The current debate is really about whether the growth and margin story can support that kind of valuation over time.
The record high commercial aircraft backlog and accelerating global air travel, especially in Asia Pacific and Europe, are associated with increased production rates such as 737 MAX and A320. This continues to support higher revenue visibility and potential earnings growth for Howmet Aerospace as those build rates flow through its content per aircraft.
See why 87 investors see Howmet Aerospace as 32% undervalued.
Result: Fair Value of $324.55 (UNDERVALUED)
Still, this bullish fair value story for Howmet Aerospace leans heavily on analysts hitting ambitious growth and margin assumptions, as well as on competition in blades, vanes and fasteners not eroding pricing or share.
Find out about the key risks to this Howmet Aerospace narrative.
Another Angle On Howmet Aerospace’s Valuation
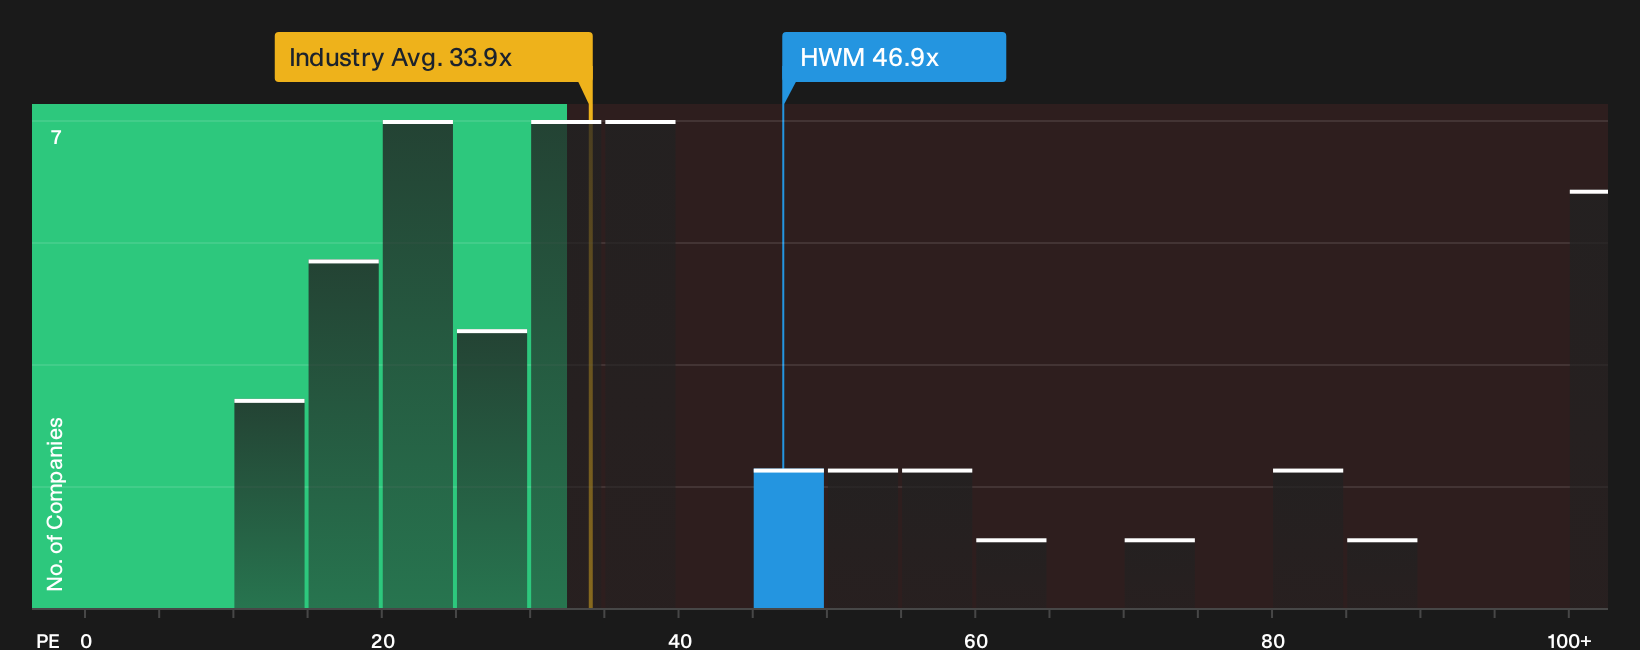
That 32% undervalued narrative leans heavily on future earnings, yet today Howmet Aerospace trades on a P/E of 46.9x. The US Aerospace & Defense group averages 33.9x, while the fair ratio is estimated at 32.5x. That is a rich premium. Is the quality story strong enough to keep it there?
For a closer look at what the numbers imply about this price, including how that high P/E compares across peers and the fair ratio the market could move toward, see the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far or leaning one way already? Move quickly, test your own thesis against both sides of the data, then weigh up the 4 key rewards and 1 important warning sign.
Looking for more Howmet Aerospace sized investment ideas?
If you only focus on Howmet Aerospace, you could miss other opportunities that fit your risk, income, or quality goals just as well.
- Target resilient balance sheets and fundamentals that can handle shocks by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality where the numbers and business strength line up through the 35 high quality undervalued stocks.
- Strengthen your portfolio’s income stream with the 8 dividend fortresses before the next round of payouts is priced in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com