
Is Chubb (CB) Fully Valued Ahead Of Earnings After Its Claims Leadership Shakeup?
Leadership moves and an earnings countdown put Chubb in focus
Chubb (CB) is heading into Tuesday afternoon’s earnings release just days after reshaping its Global Claims leadership. This timing puts operational execution and potential future profitability levers under a brighter investor spotlight.
Recent moves in Chubb’s Global Claims unit come amid firm share price momentum, with the stock at US$356.27 and a year-to-date share price return of 14.9%. The 1-year total shareholder return of 34.48% and 5-year total shareholder return of 103.70% indicate that investors are already rewarding the story as management adjustments and upcoming earnings shape views on both growth potential and risk.
Spot fresh ideas with similar insurance and balance sheet profiles by scanning our curated list of solid balance sheet and fundamentals (25 results) as you weigh what Chubb’s earnings and leadership reset might mean for your portfolio.Chubb’s run to US$356.27, combined with new claims leadership and an earnings print only hours away, leaves a fork in the road. Do you pay up now or wait for a cleaner entry after the valuation work?
Most Popular Narrative: 2.6% Undervalued
The most followed narrative on Chubb pegs fair value at $365.91, only modestly above Monday’s $356.27 close. This implies investors are already pricing in a lot of the good news around earnings power and capital returns.
The numbers imply that at the current share price, investors are paying for a company that already delivers 18.2% core operating EPS growth, a 17.1% rise in tangible book value per share, and ongoing buybacks under a US$7.5b repurchase program. Together, these factors support the view that Chubb stock is fairly valued yet still treated as bullish in this narrative.
See why 82 investors see Chubb as 3% undervalued.
Result: Fair Value of $365.91 (UNDERVALUED)
Still, this Chubb narrative can wobble if casualty loss cost inflation outpaces pricing, or if reduced large account and E&S property premiums shrink the underwriting base.
Find out about the key risks to this Chubb narrative.
Another View: Chubb looks expensive on earnings multiples
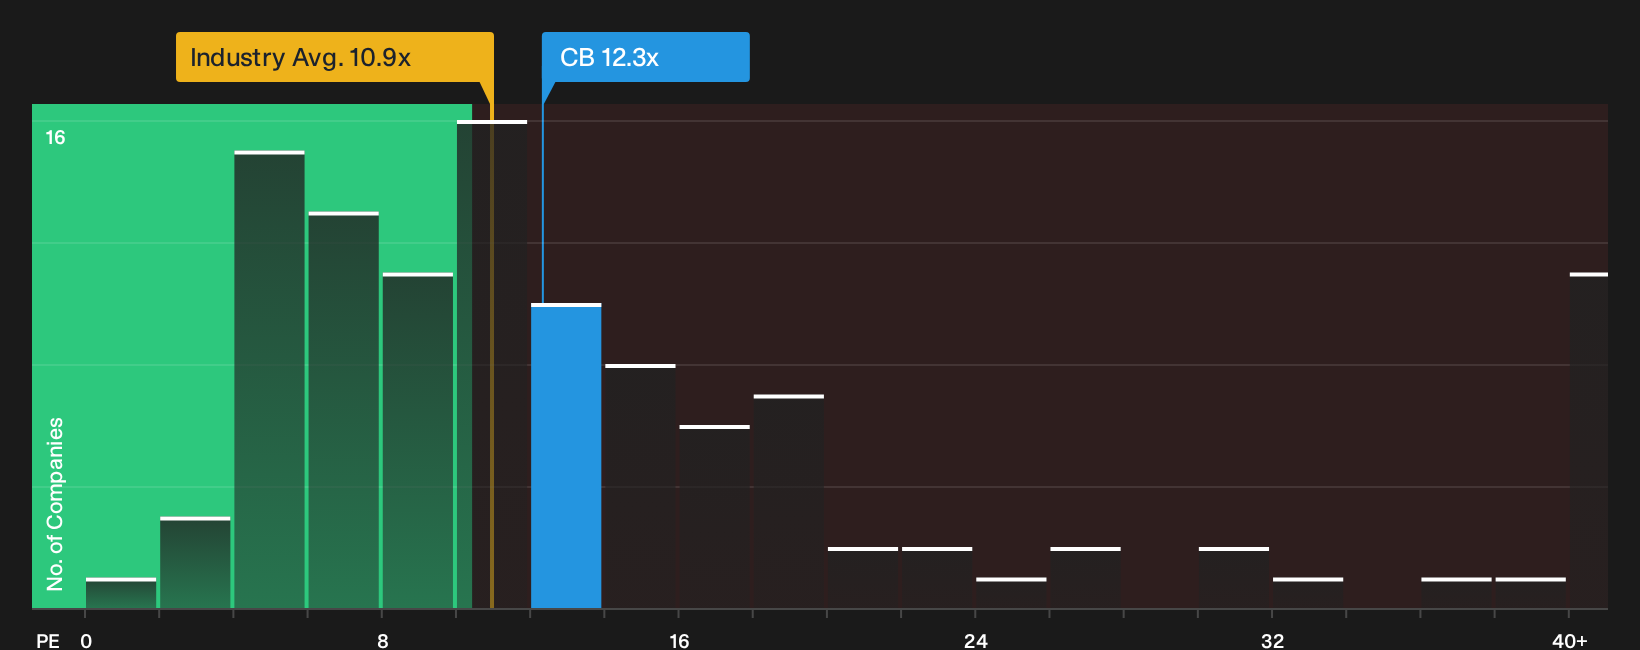
Chubb may screen as undervalued on a fair value estimate, yet the P/E picture tells a tougher story. The stock trades at 12.3x earnings compared with 10.9x for the wider US insurance group and a fair ratio of 10.6x. That richer tag raises questions about how much cushion is left if sentiment cools.
For a closer read on what the current earnings multiple implies for upside and downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Chubb story so far. Act quickly, run the numbers yourself, and weigh both sides of the ledger with 2 key rewards and 2 important warning signs
Looking for more Chubb-like investment ideas?
Do not stop with Chubb. Use fresh screeners to surface new opportunities that fit your style before the next move leaves you watching from the sidelines.
- Target firms with strong cash generation and pricing power by scanning our 35 high quality undervalued stocks, which blends quality fundamentals with potential mispricing.
- Consider potential income streams by reviewing the 8 dividend fortresses and focusing on businesses offering higher yields with an emphasis on stability.
- Evaluate your downside risk by filtering through the 32 resilient stocks with low risk scores, designed to highlight businesses with more resilient financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com