
Will Raised Guidance Change Host Hotels' (HST) Narrative
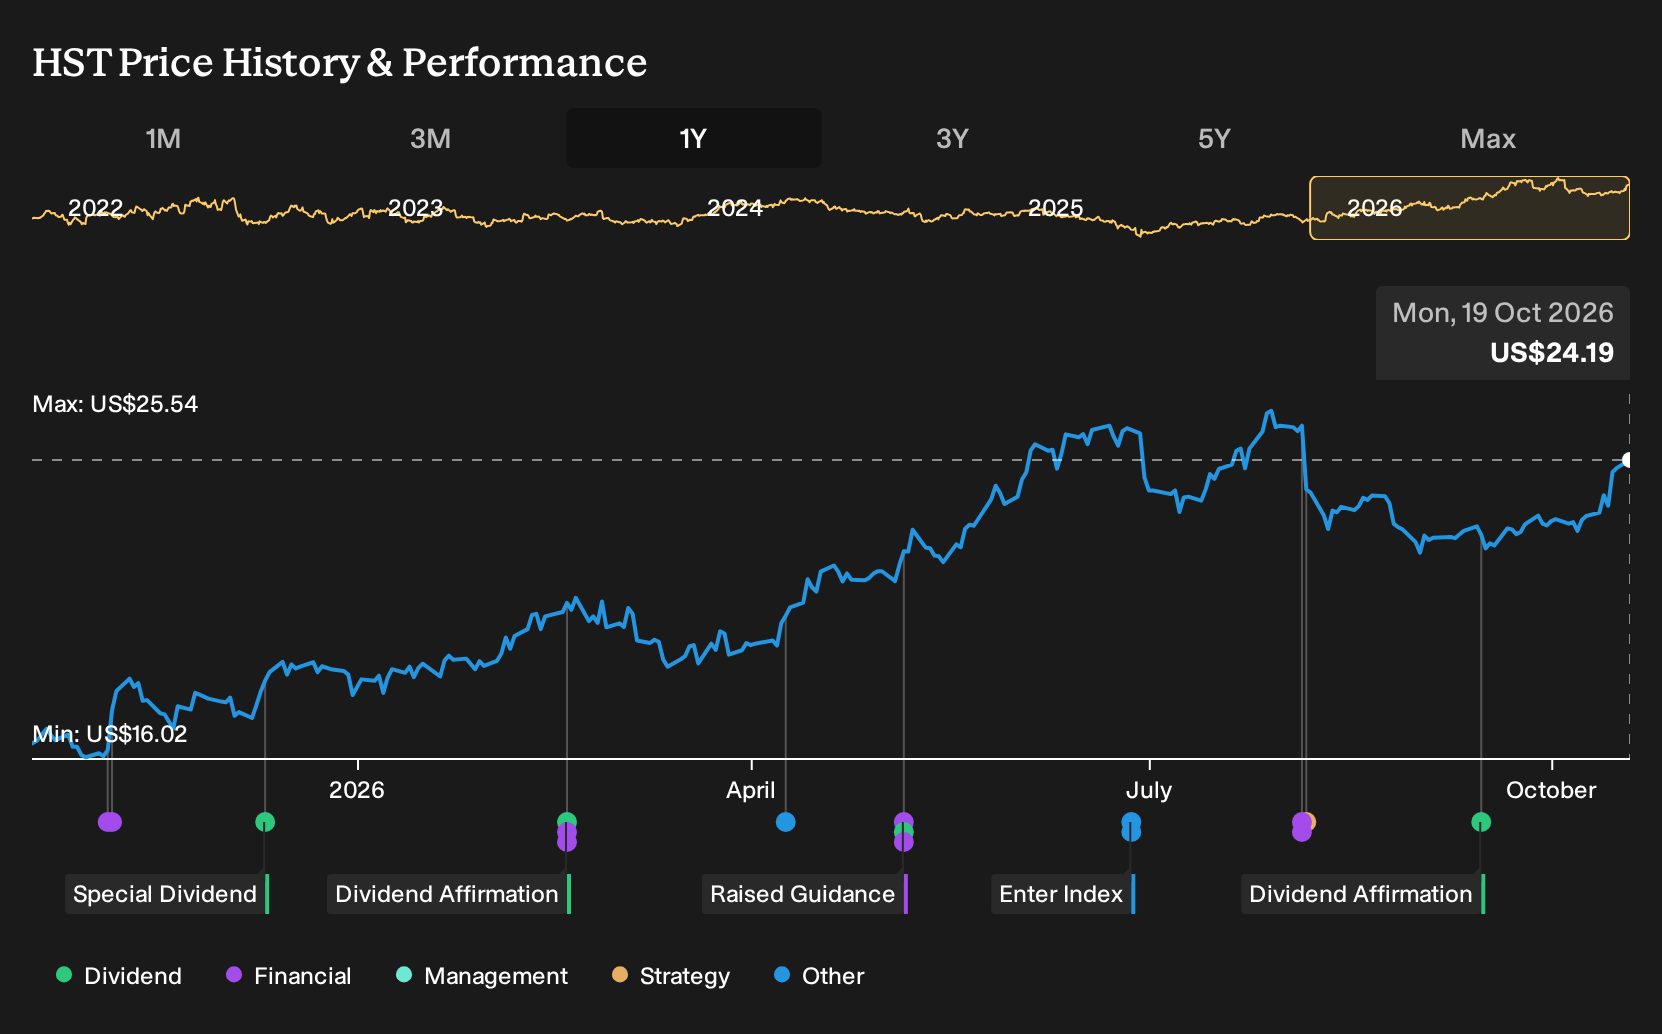
- Host Hotels & Resorts recently raised its 2026 operating guidance and highlighted higher adjusted FFO per share expectations, while progressing a roughly US$2.1b renovation and development program across 34 hotels.
- The scale of these projects, along with early RevPAR index share gains at already completed properties, places future cash generation and capital allocation decisions under sharper focus for investors.
- We will now look at how Host Hotels & Resorts raising guidance and renovation spending could reshape the broader investment narrative.
Extend your research beyond Host Hotels & Resorts by scanning a curated shortlist of potential value ideas in our 35 high quality undervalued stocks, which also pair earnings power with balance sheet strength.
Host Hotels & Resorts Investment Narrative Recap
For you to back Host Hotels & Resorts as a shareholder, you need to be comfortable with a simple idea. The business is leaning into high end leisure and resort demand while pouring about US$2.1b into upgrades that management expects to shape a large slice of 2026 hotel EBITDA. The raised 2026 operating guidance and higher adjusted FFO per share expectations keep that refurbishment heavy plan front and center rather than changing the story.
The key short term catalyst is execution on these renovations translating into RevPAR and EBITDA contribution as more properties stabilize. The biggest risk remains twofold: structural pressure on business travel could cap weekday occupancy, and heavy capital spending may squeeze free cash flow if returns from the 34 hotel projects do not meet expectations.
The most relevant development here is the refreshed 2026 outlook from Host Hotels & Resorts that pairs higher adjusted FFO per share expectations with progress on its renovation and development pipeline. That update aligns with earlier data that 21 already stabilized properties were showing close to a 9 point RevPAR index share gain, which ties the forecast more tightly to visible assets.
For catalysts, that raised guidance gives investors a clearer yardstick for how the remaining projects and resort driven demand could support room revenue, out of room spend and EBITDA over the next few years. On the risk side, analysts still model earnings declining about 9.4% per year over the next 3 years, so the burden is firmly on the business to keep converting this US$2.1b spend into durable cash generation rather than just a one off uplift.
Host Hotels & Resorts' current analyst narrative points to revenues of US$6.3b and earnings of US$822.9m by 2029, based on expectations of fairly flat revenue over the next 3 years. Profit margins are projected to move from 16.5% today to 13.0%, with earnings declining by about US$177m from US$1.0b today.
Uncover why Host Hotels & Resorts' fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on earnings pressure. The most bearish analysts were penciling in earnings of about US$632.2m on roughly US$6.2b of revenue by 2029 for Host Hotels & Resorts, with a higher future P/E assumption. That is far more cautious than consensus and could shift again as the new guidance and renovation progress filter through. Readers like you should compare both narratives and decide which feels more reasonable.
Explore another Host Hotels & Resorts fair value estimate, including one that suggests it could be worth just $25.29.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Host Hotels & Resorts research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Host Hotels & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Host Hotels & Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Host Hotels & Resorts?
Once you have a view on Host Hotels & Resorts, broaden your watchlist with other opportunities that fit different portfolio goals using the Simply Wall St Screener.
- For investors hunting for potential mispricing, scan a curated group of companies that screen as 35 high quality undervalued stocks based on both earnings power and balance sheet quality.
- If capital preservation sits high on your list, filter for businesses in our 32 resilient stocks with low risk scores that combine resilient fundamentals with lower risk scores.
- To round out your research with stronger financial footing, review a list of solid balance sheet and fundamentals (25 results) to spot companies where debt and liquidity metrics may better support long term plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com