
VAT Group (SWX:VACN) Raised Guidance, Is It Still 13% Below Fair Value?
Guidance reset puts VAT Group in focus
VAT Group (SWX:VACN) moved into the spotlight after management raised its 2027 sales guidance to a level significantly above the previous CHF 1.5b to 1.7b range and reaffirmed higher 2026 sales and net income expectations.
Recent trading has been choppy for VAT Group, with the share price falling 6.8% over the past week and 11.5% over the past three months. Yet the year to date share price return of 43.2% and 1 year total shareholder return of 85.5% still point to strong momentum as investors weigh the upgraded guidance against earlier volatility.
Scan how VAT Group’s reset guidance fits into a wider set of potential opportunities and risks by comparing it with the 613 high quality undiscovered gems on Simply Wall St.
Guidance now points higher while the share price has already run hard. The real issue for VAT Group is whether the current tag still compensates you for the risks that come with that optimism.
Most Popular Narrative: 13% Undervalued
VAT Group last closed at CHF619.60, while the most followed narrative anchors fair value at CHF716.17. The current guidance upgrade is being weighed against a valuation framework that still sees upside after a strong run.
The industry's transition to next-generation chip nodes (e.g., Gate-All-Around, 2nm), together with more than 100 new fabs under construction and increasing technological complexity in manufacturing, is expanding the addressable market for high-precision vacuum equipment, positioning VAT to outpace wafer fab equipment market growth and drive above-market revenue gains over the next several years.
See why 23 investors see VAT Group as 13% undervalued.
Result: Fair Value of CHF716.17 (UNDERVALUED)
Still, concentrated exposure to semiconductors and a larger tilt toward China, where policy or export changes can bite quickly, could unwind the current VAT Group optimism.
Find out about the key risks to this VAT Group narrative.
Another Take On VAT Group’s Valuation
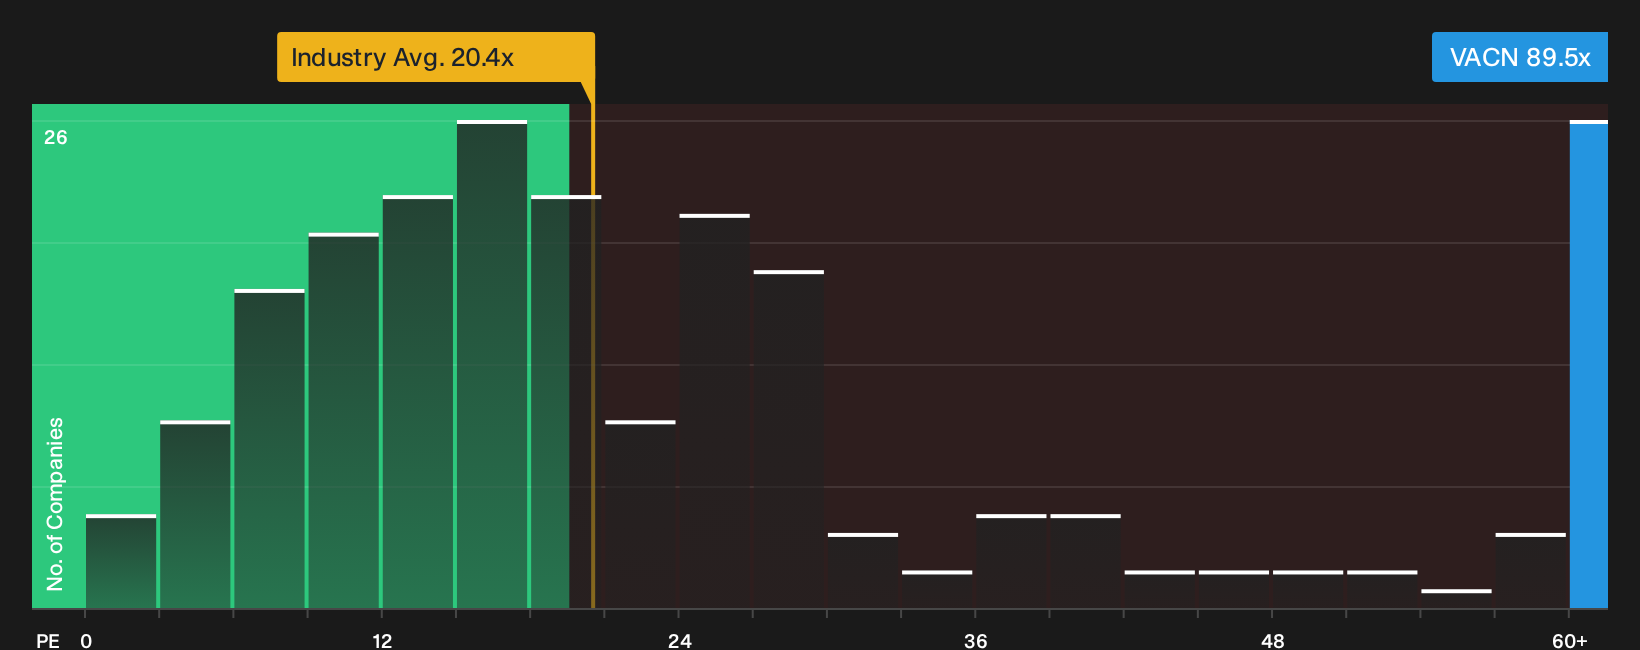
Analyst narratives frame VAT Group as 13% undervalued on future earnings, yet the current P/E of 89.5x is far above both the European Machinery average of 20.6x and peers at 23.9x. It also sits at almost double the 45.2x fair ratio that the market could move toward. This raises a simple question for you: How comfortable are you paying that kind of premium for this growth story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and risk around VAT Group feels finely balanced, consider acting promptly and reviewing the numbers yourself. A straightforward starting point is to weigh the 1 key reward and 1 important warning sign.
Looking for more VAT Group investment ideas?
Do not stop your research with VAT Group alone. Fresh ideas from different corners of the market can sharpen your decisions and help you spot opportunities earlier.
- Target potential mispricing by scanning a 200 high quality undervalued stocks list that filters for quality businesses where price and fundamentals appear out of sync.
- Prioritise resilience and sleep-better-at-night holdings by checking a 231 resilient stocks with low risk scores built around stronger balance sheets and steadier risk profiles.
- Hunt for under-the-radar potential by reviewing a 133 elite penny stocks with strong financials selection that focuses on smaller companies with more robust financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com