
US Foods Holding (USFD) Sets A New Labor Standard, Is The Stock Still Undervalued?
Labor deal sets new pay and benefit benchmarks
US Foods Holding (USFD) just saw more than 500 Southern California drivers, warehouse staff, and mechanics represented by the Teamsters approve a new contract featuring wage gains, pension improvements, and protections around automation.
The agreement covers workers who service restaurants, universities, and hospitals across the region, with wage increases reported between 66% and 70% over the contract term alongside continued employer funded health coverage.
Investors have seen momentum build in US Foods Holding this year, with the share price returning 34.5% year to date and the latest close at $100.38. The 3 year total shareholder return of about 171% and 5 year total shareholder return of about 179% point to a strong longer run, even as the stock slipped 1.6% on the day and traders weighed the new labor agreement alongside other recent corporate updates.
Capitalize on the pressure US Foods Holding faces from rising labor costs by comparing it with other distributors and consumer stocks screened for list of solid balance sheet and fundamentals (25 results).After a 34.5% year to date climb and a fresh labor deal that could squeeze margins, US Foods Holding sits at a crossroads. Is the bigger opportunity now behind the stock or still in front of it as valuation resets come through?
Most Popular Narrative: 13% Undervalued
On Simply Wall St's most followed narrative, US Foods Holding screens as undervalued, with a fair value of $116.00 against the latest $100.38 close. This frames the new labor deal as just one factor inside a larger earnings and cash flow story.
The ongoing shift toward greater away from home dining, especially among younger demographics, aligns with US Foods Holding continuing to report multi year share gains in independent restaurants, health care, and hospitality. This can keep supporting revenue growth and EBITDA contribution from these higher margin segments.
See why 8 investors see US Foods Holding as 13% undervalued.
Result: Fair Value of $116.00 (UNDERVALUED)
Still, higher labor agreements and ongoing fuel and weather related cost pressures could compress US Foods Holding margins and test confidence in the current, reportedly undervalued, narrative.
Find out about the key risks to this US Foods Holding narrative.
Another View: Valuing US Foods Holding On Its P/E
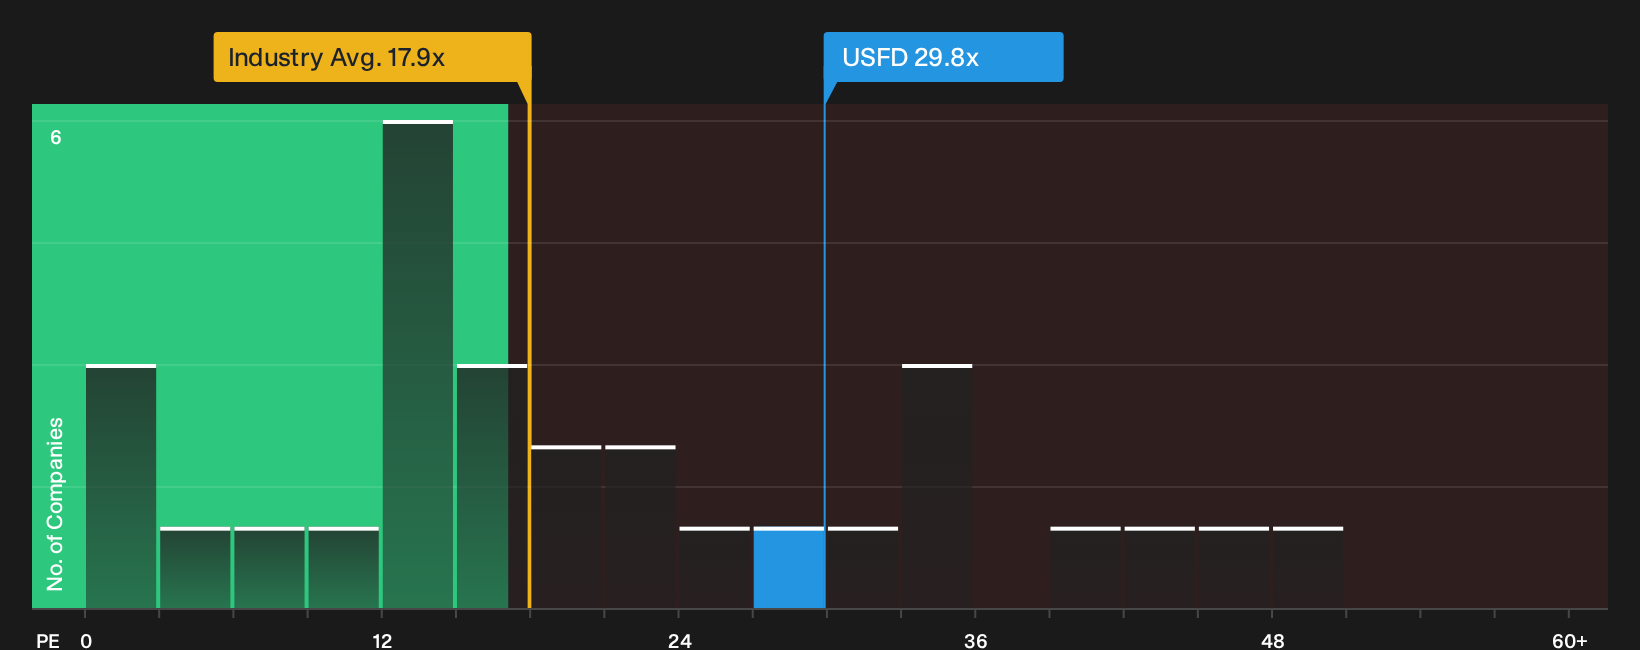
The discounted cash flow work points to upside for US Foods Holding, yet the P/E picture is less generous. The shares trade on 29.8x earnings, above the US Consumer Retailing industry at 18.1x and slightly above a 28.8x fair ratio. That premium narrows the margin for error if earnings disappoint.
For a closer look at how that P/E gap, the industry comparison and the fair ratio could evolve as new quarters roll through, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The story so far contains mixed messages, so you may want to test the data yourself before sentiment shifts again. Start by weighing the 3 key rewards and 2 important warning signs.
Looking for more US Foods Holding investment ideas?
If the US Foods Holding story feels finely balanced, broaden your watchlist now so you are not relying on a single outcome or sector.
- Target potential mispricings by scanning for quality companies that combine strong fundamentals with room for a re rating using 35 high quality undervalued stocks.
- Reduce stress around capital preservation by filtering for companies with resilient balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for under followed opportunities before the crowd arrives by reviewing 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com