
Learn Why The Bull Case For Applied Materials Stock Could Change Following EPIC Center Launch
- Applied Materials has opened its US$5b EPIC Center in Sunnyvale, a 600,000 square foot semiconductor R&D hub where chipmakers, systems companies and universities work alongside Applied teams in shared cleanroom space to speed commercialization of AI era process technology and manufacturing equipment.
- The EPIC Center’s co development model, bringing partners like Intel, TSMC, Samsung, Micron, SK hynix and UCLA directly into Applied Materials’ tools and cleanrooms, concentrates customer roadmaps and research programs inside the company’s own infrastructure, which can influence product mix, R&D efficiency and long term equipment and services demand.
- We will look at how Applied Materials’ investment narrative is shaped by the EPIC Center’s US$5b AI focused semiconductor R&D build.
Applied Materials Investment Narrative Recap
To own Applied Materials, you need to believe the AI driven wafer fab equipment cycle translates into sustained demand for higher value tools, advanced packaging and process control, not just a one time buildout. The EPIC Center reflects that view by concentrating customer roadmaps on Applied’s platform. The key near term swing factor remains how quickly this richer mix shows up in orders and revenue.
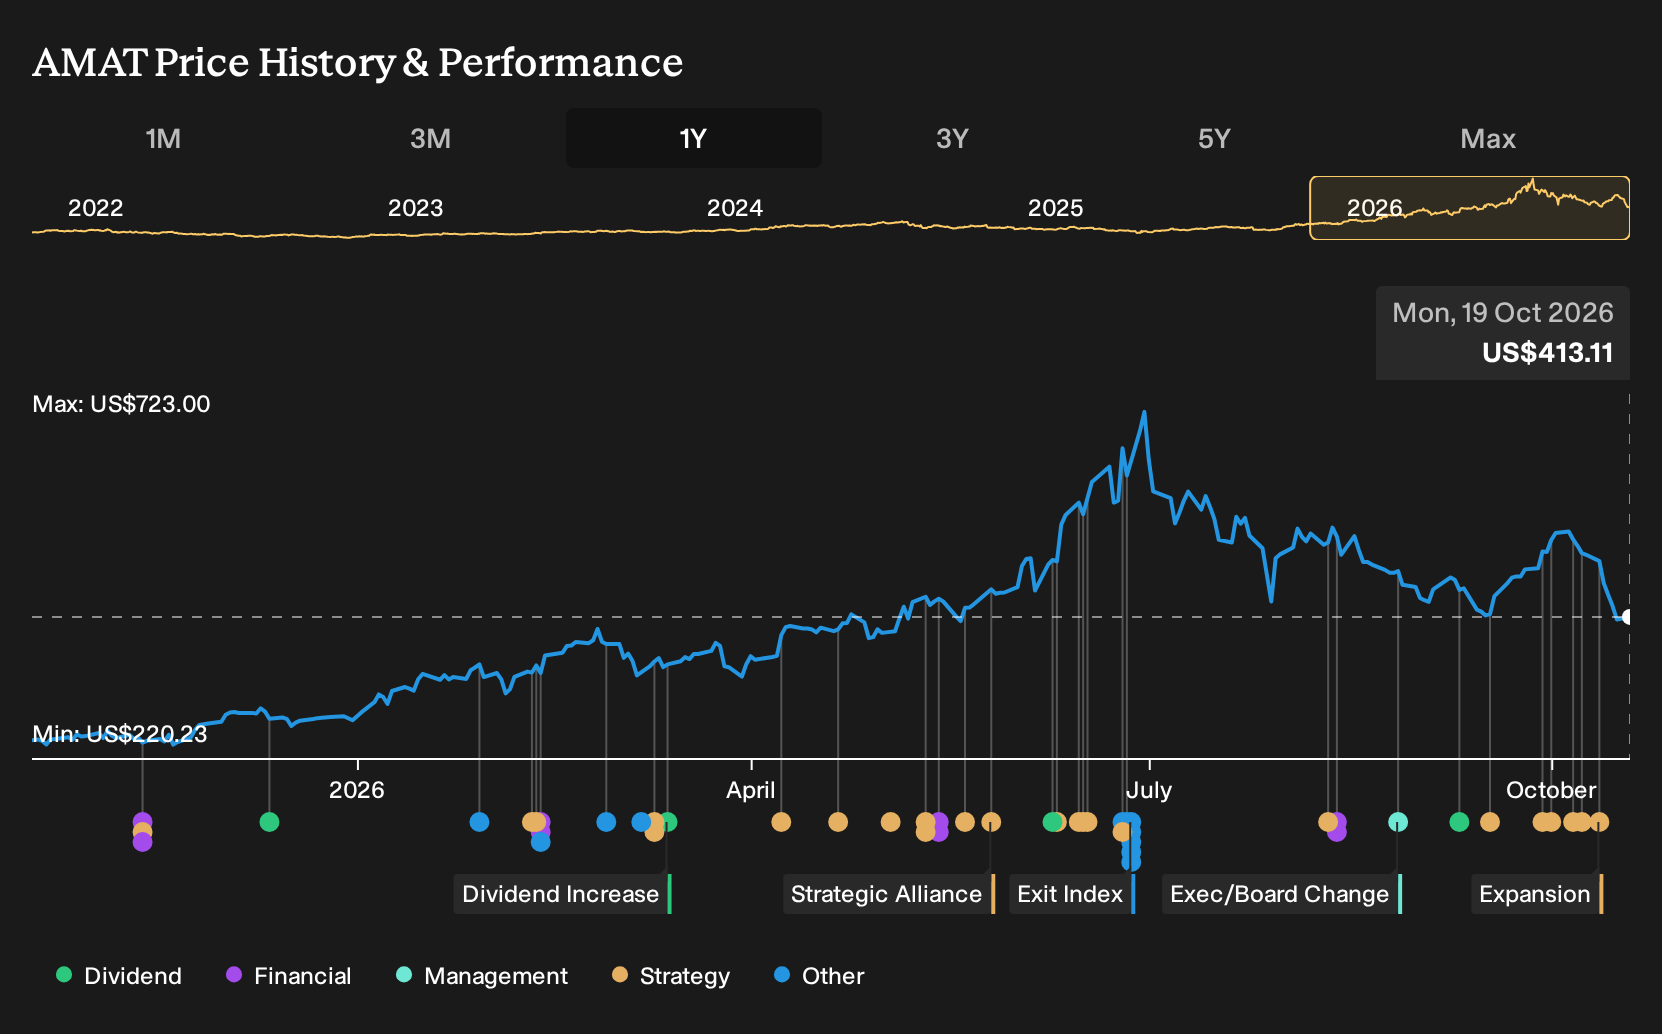
The biggest near term risk is that heavy EPIC and capacity spending, combined with flat gross margin guidance, keeps free cash flow tight even if sales stay healthy. Recent share price volatility and ETF outflows underline that any sign of slower mix improvement or weaker cash conversion can still affect sentiment significantly.
The most relevant recent development is Applied Materials expanding EPIC collaboration with Intel on next generation transistors, interconnects and advanced packaging. That work ties directly to the thesis that AI compute and 3D packaging will increase demand for Applied’s higher value process tools, diagnostics and services rather than just baseline capacity additions.
Operationally, this Intel collaboration gives Applied earlier visibility into logic and packaging roadmaps and a real world test bed for the EPIC model. Execution risk is clear. The company needs to manage ramp costs and complex joint programs while keeping gross margin and cash generation aligned with its guidance. If EPIC projects scale smoothly into high volume manufacturing, they could become an important validation of the AI and packaging catalyst thesis.
Applied Materials’ current analyst narrative points to revenues of US$58.5b and earnings of US$19.6b by 2029, based on revenue growth assumptions of 23.8% per year and a move from US$9.3b of earnings today to that 2029 consensus, which is roughly a 2.1x increase in profits.
Uncover why Applied Materials' fair value indicates a 55% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into EPIC as a catalyst. The most bullish analysts already pencilled in about US$78.7b of revenue and US$28.7b of earnings by 2029, far above consensus. You can see how this new Applied Materials build might push those optimistic voices to recalibrate again, in either direction.
Explore 9 other Applied Materials fair value estimates, including one that suggests there may be as much as 100% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Applied Materials research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Applied Materials. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Materials' overall financial health at a glance.
Looking for more investment ideas beyond Applied Materials?
If the EPIC story has sharpened your view on AI infrastructure, it can be useful to line that thesis up against other opportunities and see where the risk and reward trade off feels more comfortable for you.
- For investors who want potential mispricing paired with quality fundamentals, consider starting with a curated set of companies screened as 35 high quality undervalued stocks.
- If capital preservation and steadier price moves matter most to you, focus on businesses filtered for resilience through our 32 resilient stocks with low risk scores.
- When balance sheet strength is non negotiable, narrow your watchlist to companies flagged in the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com