
Hysan Development (SEHK:14) Could Be 22% Undervalued On Lee Gardens Expansion Debate
Fresh commentary on Hysan Development (SEHK:14) is focusing on its elevated P/E ratio, as investors evaluate whether the gains over the past three years and the Lee Gardens expansion still justify a premium.
Recent trading has been choppy, with a 1-day share price return of 1.34% at HK$15.92 but a 90-day share price decline of 10.11%. The 3-year total shareholder return of 37.06% signals that longer term enthusiasm for Hysan Development has still been rewarded, despite the weaker year to date share price return of 15.68%.
Compare Hysan Development's relatively high P/E ratio and its mixed recent returns with a curated 200 high quality undervalued stocks that currently trade at lower valuations relative to their fundamentals.
The share price has already delivered a solid three year run while the P/E has stretched to a premium, so how much of Hysan Development's story is still ahead of you rather than already in the rear view mirror?
Most Popular Narrative: 18% Undervalued
On the most followed view, Hysan Development screens as undervalued, with a fair value estimate of HK$19.38 against the latest close at HK$15.92. This puts the current premium P/E in the spotlight and raises the question of whether the Lee Gardens expansion and related projects still have enough earnings power left to narrow that gap.
The imminent completion of Lee Garden Eight, a major 1 million sq ft expansion featuring green/experiential design and the largest commercial floor plate on Hong Kong Island, will boost Hysan's retail and office leasable portfolio by around 30% in 2026. This is poised to drive a step change in recurring rental revenue and tenant sales, particularly as the integrated precinct and nearby pedestrian walkway increase daily footfall by an estimated 20%.
See why 4 investors see Hysan Development as 18% undervalued.
Result: Fair Value of HK$19.38 (UNDERVALUED)
Still, two pressure points hang over the Hysan Development story: persistent weakness in Hong Kong office rents and higher funding costs from recent 7.3% perpetuals.
Find out about the key risks to this Hysan Development narrative.
Another View: Hysan Development Looked At Through Earnings Multiples
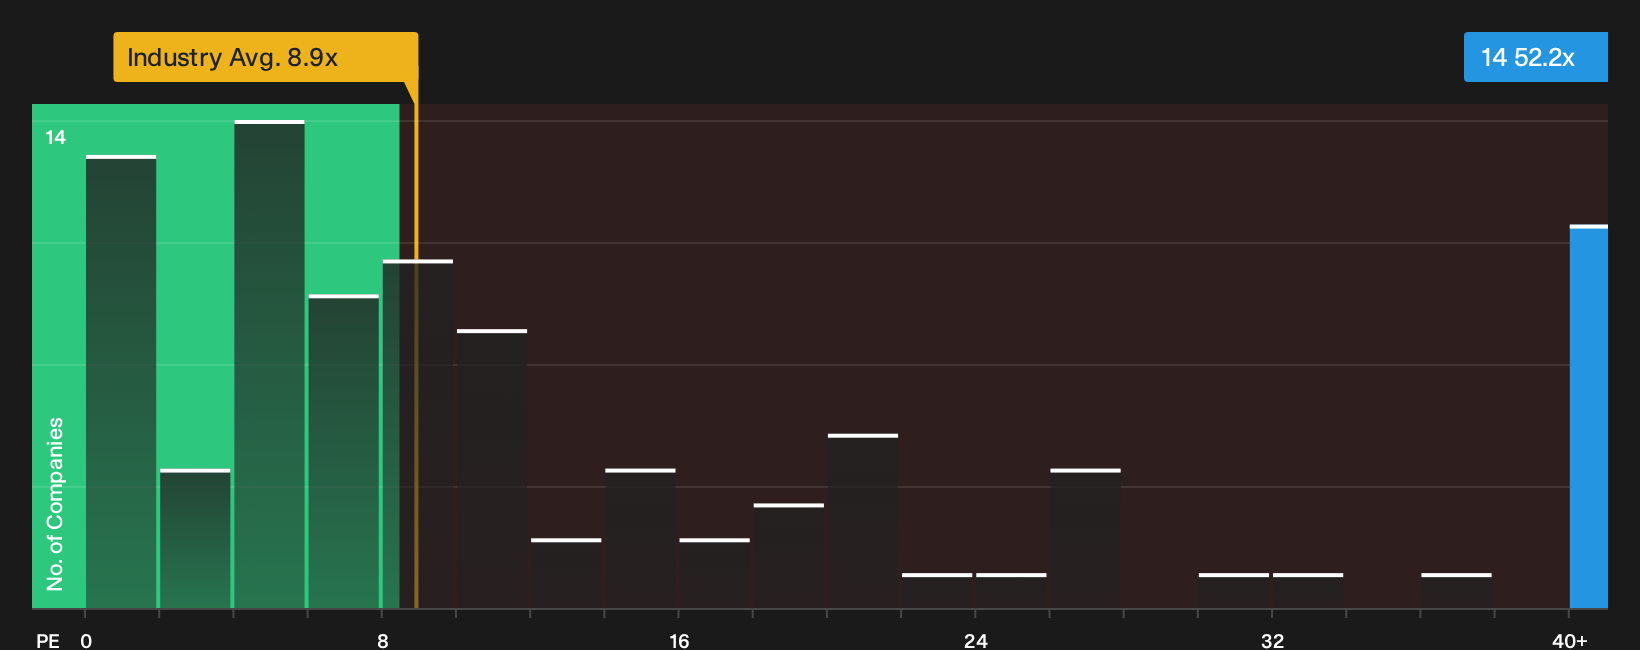
A second lens on Hysan Development comes from its P/E ratio. The stock trades on 52.2x earnings, compared with 14.1x for peers and 8.9x for the Hong Kong real estate industry, while the fair ratio is 18.9x. That gap points to real valuation risk if sentiment cools.
This kind of premium can unwind quickly if earnings or rental assumptions change, so the key question is whether you think Hysan Development has already earned that multiple or still has to grow into it.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Hysan Development feels familiar, move quickly from headline takes to your own judgment by weighing its 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Hysan Development?
Do not stop your research with Hysan Development. Broaden your watchlist now and give yourself more options before the next wave of opportunities starts moving.
- Target potential value plays early by scanning a curated 200 high quality undervalued stocks that pair appealing valuations with fundamentals that already support the current price.
- Protect the downside first and hunt through a 231 resilient stocks with low risk scores that screens for businesses with stronger stability metrics and fewer red flags.
- Spot future leaders before the crowd by working through a 613 high quality undiscovered gems that combines quality markers with relatively low current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com