
DAIHEN (TSE:6622) Pulls Back After Choppy Trading, Is It Fully Priced?
DAIHEN (TSE:6622) is back on radar after recent share price swings, with the stock closing at ¥2,650 on 20 October 2026. That move has investors rechecking performance metrics and valuation signals.
Recent trading has been choppy for DAIHEN, with the share price down 11.81% over the past week after a 4.17% gain across the last month. The year-to-date share price return of 24.30% and 1-year total shareholder return of 39.53% indicate that momentum has cooled in the short term but remains strong over a longer stretch.
Scan how DAIHEN stacks up against a curated field of peers by comparing it with our hand picked 42 power grid technology and infrastructure stocks while this price action is still front of mind.
The pullback has reset sentiment around DAIHEN just as longer term returns remain strong. The key question is whether the current valuation still leaves enough upside potential to justify the risk you are taking from here.
Preferred P/E of 21x: Is it justified?
Valuation now leans on earnings. DAIHEN trades on a P/E of 21x, which prices the recent ¥2,650 close at a richer level than many peers.
The P/E multiple compares the current share price with earnings per share, so it reflects how much investors are paying for each unit of profit. For a business like DAIHEN in electrical equipment and automation, this yardstick is a common way for the market to weigh current profitability against expected earnings progress.
At 21x earnings the market is assigning a premium to the stock relative to both the JP Electrical industry average P/E of 13.8x and the peer group average of 17x. That indicates investors are paying more for each unit of earnings compared with these benchmarks. At the same time, the ratio is close to an estimated fair P/E of 22.8x. This leaves limited room for a higher valuation multiple if results only meet existing expectations rather than exceed them.
Compared with the wider sector, the P/E of 21x is materially higher than the 13.8x industry level. This implies the market is valuing DAIHEN more aggressively than typical electrical equipment stocks. The fair P/E estimate of 22.8x sits slightly above where the shares trade today, a level the multiple could move toward if earnings and sentiment remain supportive.
Explore the SWS fair ratio for DAIHEN.
Result: Price-to-earnings of 21x (OVERVALUED)
Still, that premium around DAIHEN can unravel quickly if earnings growth stalls, or if demand weakens across transformers, welding equipment, and factory automation projects.
Find out about the key risks to this DAIHEN narrative.
Another view on DAIHEN’s worth
The SWS DCF model paints a very different picture for DAIHEN. In that lens, the current ¥2,650 price sits above an estimated future cash flow value of ¥1,195.92, which screens as overvalued. That gap raises a simple question for you: Which signal carries more weight, earnings multiples or cash flows?
Look into how the SWS DCF model arrives at its fair value.
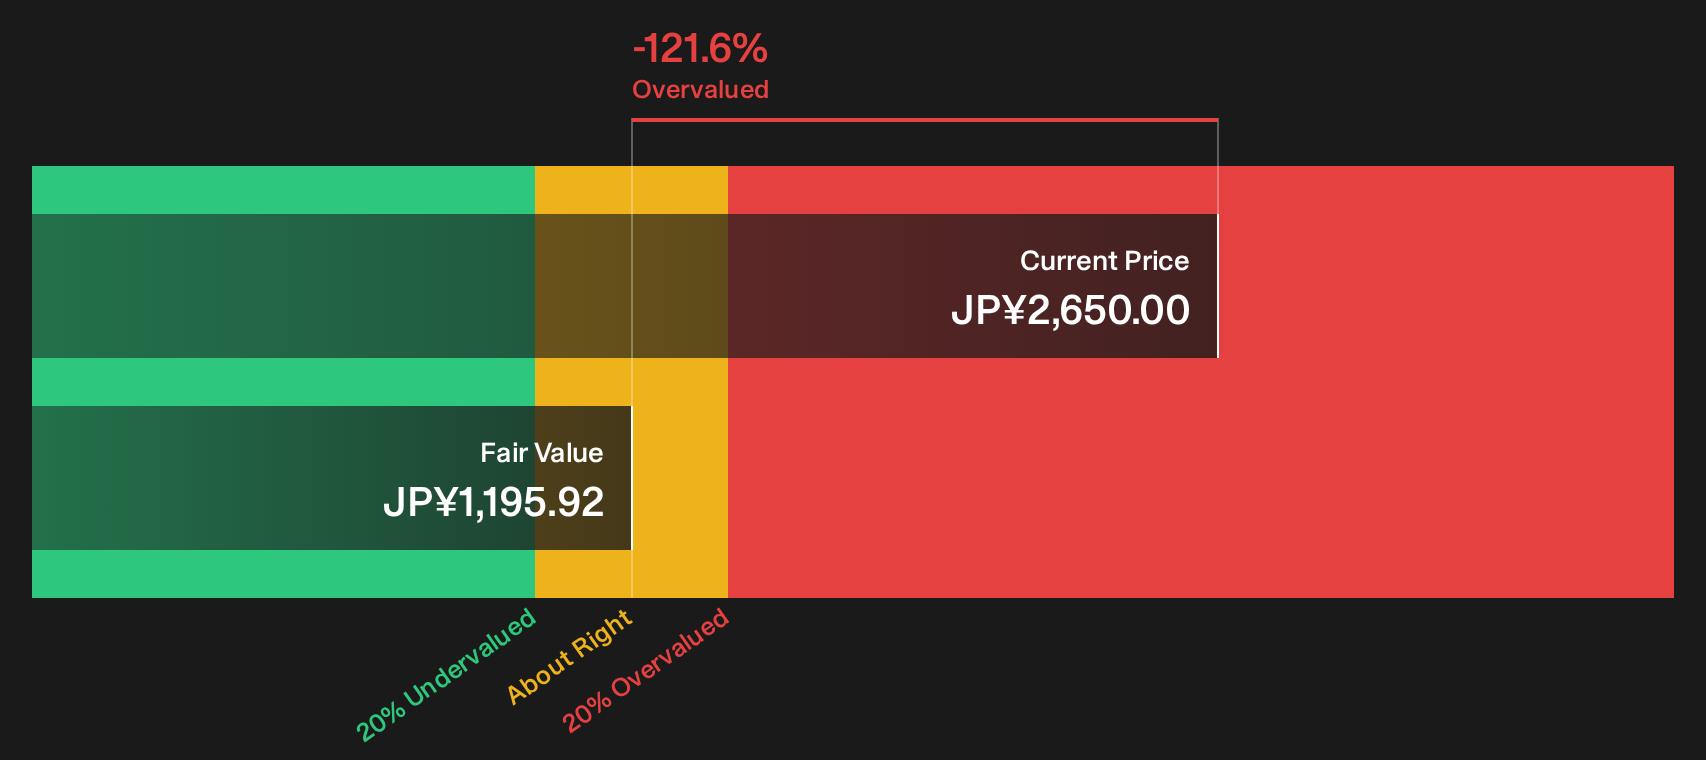
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DAIHEN for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on DAIHEN so far and a clear split between valuation tools should prompt you to check the data directly while sentiment is in flux. To see how the balance of concerns and positives lines up in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DAIHEN?
If DAIHEN has sharpened your focus on valuation and risk, do not stop here. Broader opportunity often appears where fresh ideas meet disciplined filters.
- Target value with quality by scanning a 13 high quality undervalued stocks that blends strong fundamentals with pricing that may not fully reflect them.
- Build a sturdier core for your portfolio by reviewing a list of solid balance sheet and fundamentals (22 results) that highlights companies with robust financial footing.
- Look for emerging opportunities by checking a 73 high quality undiscovered gems before attention and capital crowd the trade.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com