
Hewlett Packard Enterprise (HPE) Lands Mizuho Deal As AI Narrative Keeps Undervaluation In View
Mizuho Securities is turning to Hewlett Packard Enterprise (HPE) after selecting the HPE Cray XD2000 with direct liquid cooling to power financial simulations and support future private AI workloads in a new purpose built data center.
Hewlett Packard Enterprise’s recent AI and liquid cooling announcements arrive after a sharp share price run, with the stock up 19.6% over 90 days and posting a 131.2% year to date share price return, while the 5 year total shareholder return of 315.2% points to momentum that has been building over a longer stretch.
Scan Hewlett Packard Enterprise’s peers that are riding the same AI and high performance compute wave by zeroing in on our curated list of 55 AI infrastructure stocks.
After a 131.2% year to date surge and a 5 year total return above 300%, Hewlett Packard Enterprise now faces a harder question: Does the current price still leave enough upside to justify fresh risk?
Most Popular Narrative: 22% Undervalued
Against a last close of $55.87, the most followed narrative pegs Hewlett Packard Enterprise’s fair value at $72.03. This view sees current pricing at a clear discount and leans heavily on the AI networking story to justify that gap.
The rapid adoption of AI and machine learning across industries is driving a significant increase in demand for high performance compute and networking infrastructure. Juniper's leading position in data center and AI networking, now part of Hewlett Packard Enterprise, is expected to expand HPE's total addressable market and support multi year topline revenue growth and margin expansion in higher value segments, which can feed into earnings over time.
See why 89 investors see Hewlett Packard Enterprise as 22% undervalued.
Result: Fair Value of $72.03 (UNDERVALUED)
Still, this story can crack if HPE struggles to convert strong AI networking orders into revenue, or if Juniper integration synergies arrive slower than expected.
Find out about the key risks to this Hewlett Packard Enterprise narrative.
Another View: Hewlett Packard Enterprise Through The P/E Lens
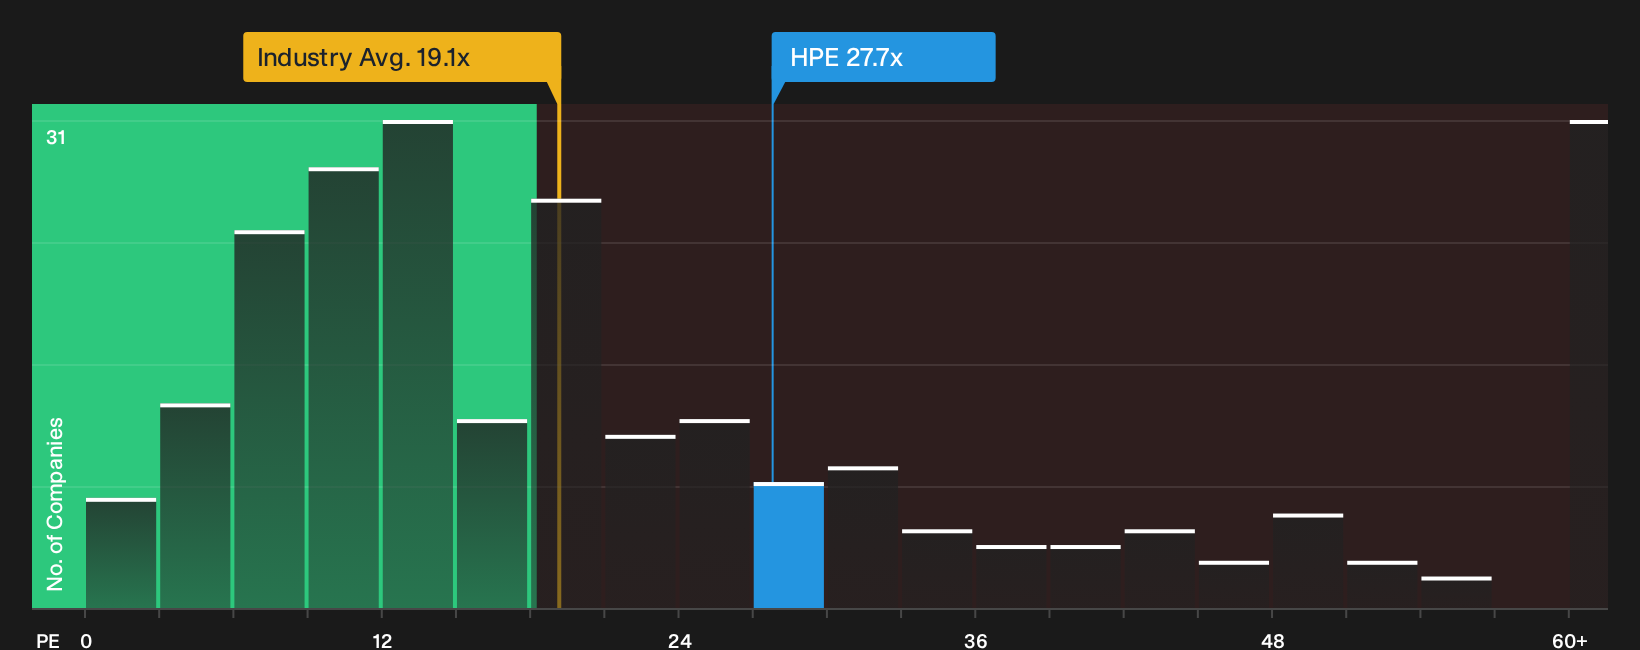
On the story driven side, Hewlett Packard Enterprise screens as undervalued against a $72.03 narrative fair value and analyst targets that sit well above the current $55.87 price. On simple P/E math though, the picture is less relaxed. HPE trades on 27.7x earnings versus a 19.1x Global Tech average and a 38.4x fair ratio estimate for the stock.
That mix of a premium to the wider sector but a discount to the 38.4x fair ratio leaves investors weighing two questions at once. Is HPE being priced richly against general tech peers, or conservatively against what the fair ratio suggests the market could move toward as the AI and networking thesis plays out?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals around Hewlett Packard Enterprise’s valuation story and AI upside, context matters more than ever. Move quickly, test the assumptions against the underlying data, and then pressure test both the upside case and the bear case by weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hewlett Packard Enterprise?
If Hewlett Packard Enterprise has sharpened your focus on AI and infrastructure, consider broadening your opportunity set by scanning other stocks that fit clear, data driven filters.
- Target resilience by reviewing companies that appear financially sturdy using our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential value by scanning the 35 high quality undervalued stocks that meet strict quality and pricing criteria.
- Prioritise stability with the 32 resilient stocks with low risk scores that screen well on fundamental risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com