
Wolters Kluwer (ENXTAM:WKL) Climbed, So What Is Behind The Move?
Wolters Kluwer (ENXTAM:WKL) is back on investor dashboards after its Tax & Accounting division rolled out new Expert AI tools inside Genya and TaxWise, tightening the focus on cloud based recurring software usage.
Recent trading has turned sharply positive, with a 1 day share price return of 3.16% and a 30 day share price return of 23.39% lifting Wolters Kluwer to €84.1, even though the year to date share price return is down 4.39% and the 1 year total shareholder return has declined 20.56%. This suggests the AI product roll out is being treated as a potential shift in growth and risk expectations rather than a completed turnaround.
Scan how Wolters Kluwer's AI push in tax software compares with other listed software platforms by reviewing our curated list of 38 profitable AI stocks that aren't just burning cash.
The recent rebound in Wolters Kluwer leaves a simple tension. Has the market already priced in the AI and cloud push, or is this just the opening leg of the rerating story that the valuation section unpacks next?
Most Popular Narrative: 18% Overvalued
The most followed Wolters Kluwer narrative points to a fair value of €71.44 against the current share price of €84.1. It frames the recent AI driven enthusiasm as potentially ahead of itself and sets up a clear valuation gap that investors are debating.
So the investment case is this, you are buying a high-quality company with durable characteristics at a time when sentiment is weak. If management proves that AI becomes an enhancement rather than a disruption, today’s valuation could look attractive in hindsight.
See why 12 investors see Wolters Kluwer as 18% overvalued.
Result: Fair Value of €71.44 (OVERVALUED)
Still, the Wolters Kluwer story could be tested if AI driven products fail to gain traction or if regulatory changes reduce demand in key segments.
Find out about the key risks to this Wolters Kluwer narrative.
Another View: What Multiples Say About Wolters Kluwer
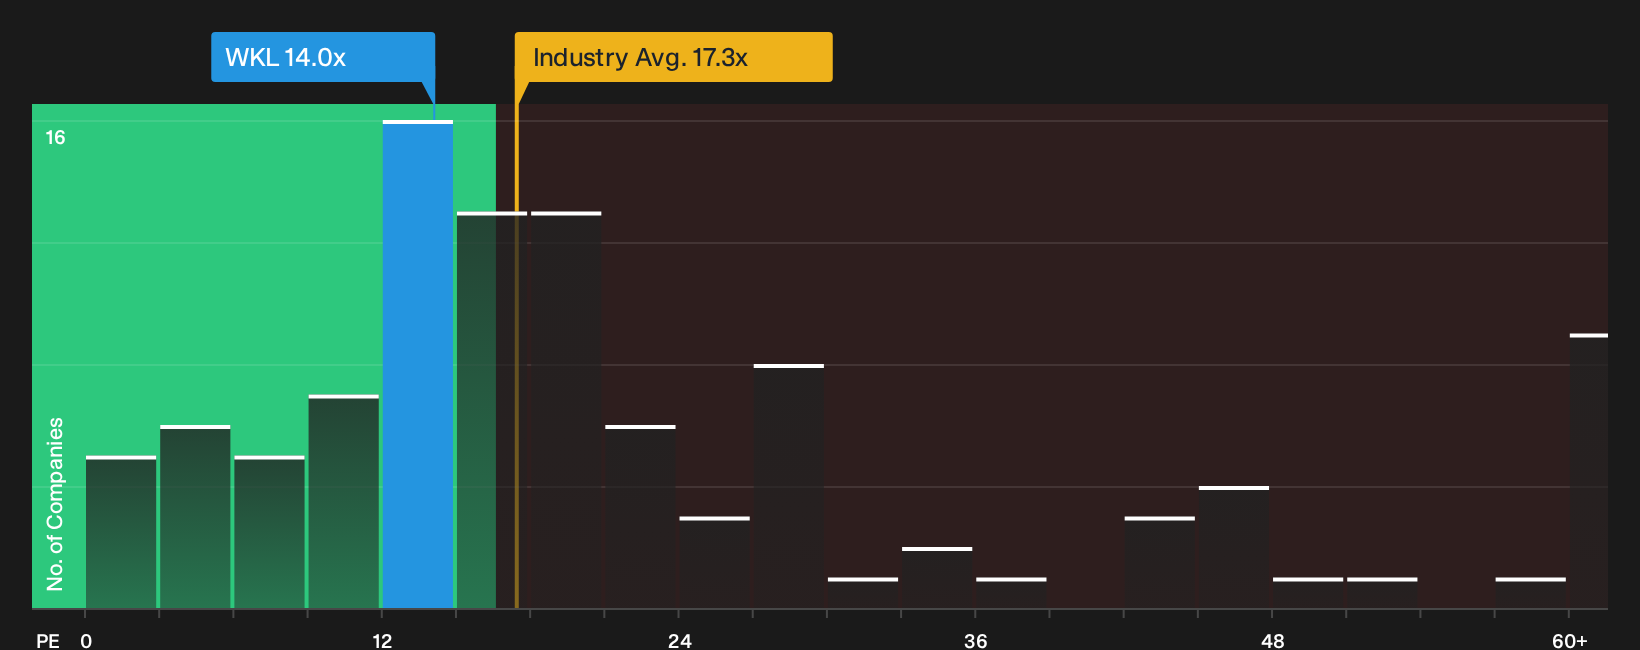
A very different picture emerges when you look at Wolters Kluwer through simple earnings multiples. The stock trades on a P/E of 14x, while direct peers average 23.2x and the wider European Professional Services group sits near 17.3x. The fair ratio for WKL is estimated at 16.8x, which points to a clear discount instead of the 18% premium implied by the most popular narrative. For investors, that kind of gap can either signal a margin of safety if the AI rollout holds up, or a value trap if growth expectations stay muted. Which camp do you think the market is quietly pricing in?
To stress test that question against the numbers rather than the headline AI story, it can help to see how earnings based valuation stacks up against other approaches in our full breakdown, including the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the sentiment around Wolters Kluwer skews too cautious or too optimistic right now? Move quickly, review both the concerns and the upside case, then weigh the 5 key rewards and 2 important warning signs.
Looking for more Wolters Kluwer style investment ideas?
You have seen how Wolters Kluwer is being weighed up. Now widen your watchlist with targeted ideas that match specific goals before the next wave of opportunities moves on.
- Target potential mispricing by scanning companies that combine quality with attractive valuations through the 200 high quality undervalued stocks.
- Lock in potential income ideas by filtering for proven payers using the 219 dividend fortresses.
- Dial down portfolio risk by focusing on resilient businesses with solid finances via the 231 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com