
European Growth Companies With High Insider Ownership And Up To 36% Earnings Growth
As the European markets navigate through a period marked by geopolitical tensions and fluctuating energy prices, the focus has shifted back to corporate fundamentals with the onset of earnings season. In this environment, growth companies with high insider ownership can offer unique insights into potential earnings expansion, as insiders' stakes often align their interests closely with those of shareholders.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| OSE Immunotherapeutics (ENXTPA:OSE) | 23% | 73.3% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.4% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 35.6% |
Here's a peek at a few of the choices from the screener.
NTG Nordic Transport Group (CPSE:NTG)
Simply Wall St Growth Rating: ★★★★☆☆
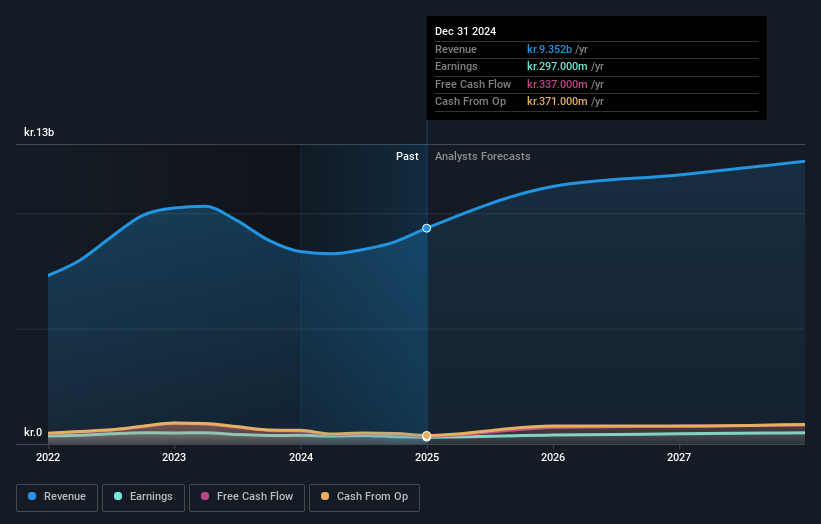
Overview: NTG Nordic Transport Group A/S, with a market cap of DKK6.78 billion, offers asset-light freight forwarding services across road, rail, air, and ocean in Denmark, Germany, the United States, Sweden, Finland and internationally.
Operations: NTG Nordic Transport Group's revenue is primarily derived from its Road & Logistics segment, which generated DKK9.70 billion, and its Air & Ocean segment, which contributed DKK2.49 billion.
Insider Ownership: 14.8%
Earnings Growth Forecast: 20.5% p.a.
NTG Nordic Transport Group has shown strong earnings growth, with recent quarterly net income rising from DKK 32 million to DKK 81 million. Despite its high debt level, the company is trading at a significant discount to its estimated fair value. Earnings are expected to grow significantly at 20.5% annually, outpacing the Danish market's average of 7.3%. However, revenue growth is projected to lag behind market expectations and insider trading data is unavailable for recent months.
- Take a closer look at NTG Nordic Transport Group's potential here in our earnings growth report.
- The valuation report we've compiled suggests that NTG Nordic Transport Group's current price could be quite moderate.
Morrow Bank (OM:MORROW)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Morrow Bank AB offers unsecured financing to consumers in Norway, Sweden, and Finland with a market cap of SEK4.73 billion.
Operations: The company's revenue is primarily derived from its banking segment, amounting to SEK788.91 million.
Insider Ownership: 21.4%
Earnings Growth Forecast: 36.3% p.a.
Morrow Bank AB demonstrates strong growth potential, with earnings projected to increase at 36.3% annually, surpassing the Swedish market average. Revenue is also expected to grow significantly by 33.3% per year. Despite trading at a 20.4% discount to its estimated fair value, the bank faces challenges with a high level of bad loans (15.3%) and a low allowance for these loans (59%). Recent earnings reported net income of SEK 78.3 million for Q2 2026.
- Navigate through the intricacies of Morrow Bank with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, Morrow Bank's share price might be too pessimistic.

New Wave Group (OM:NEWA B)
Simply Wall St Growth Rating: ★★★★☆☆
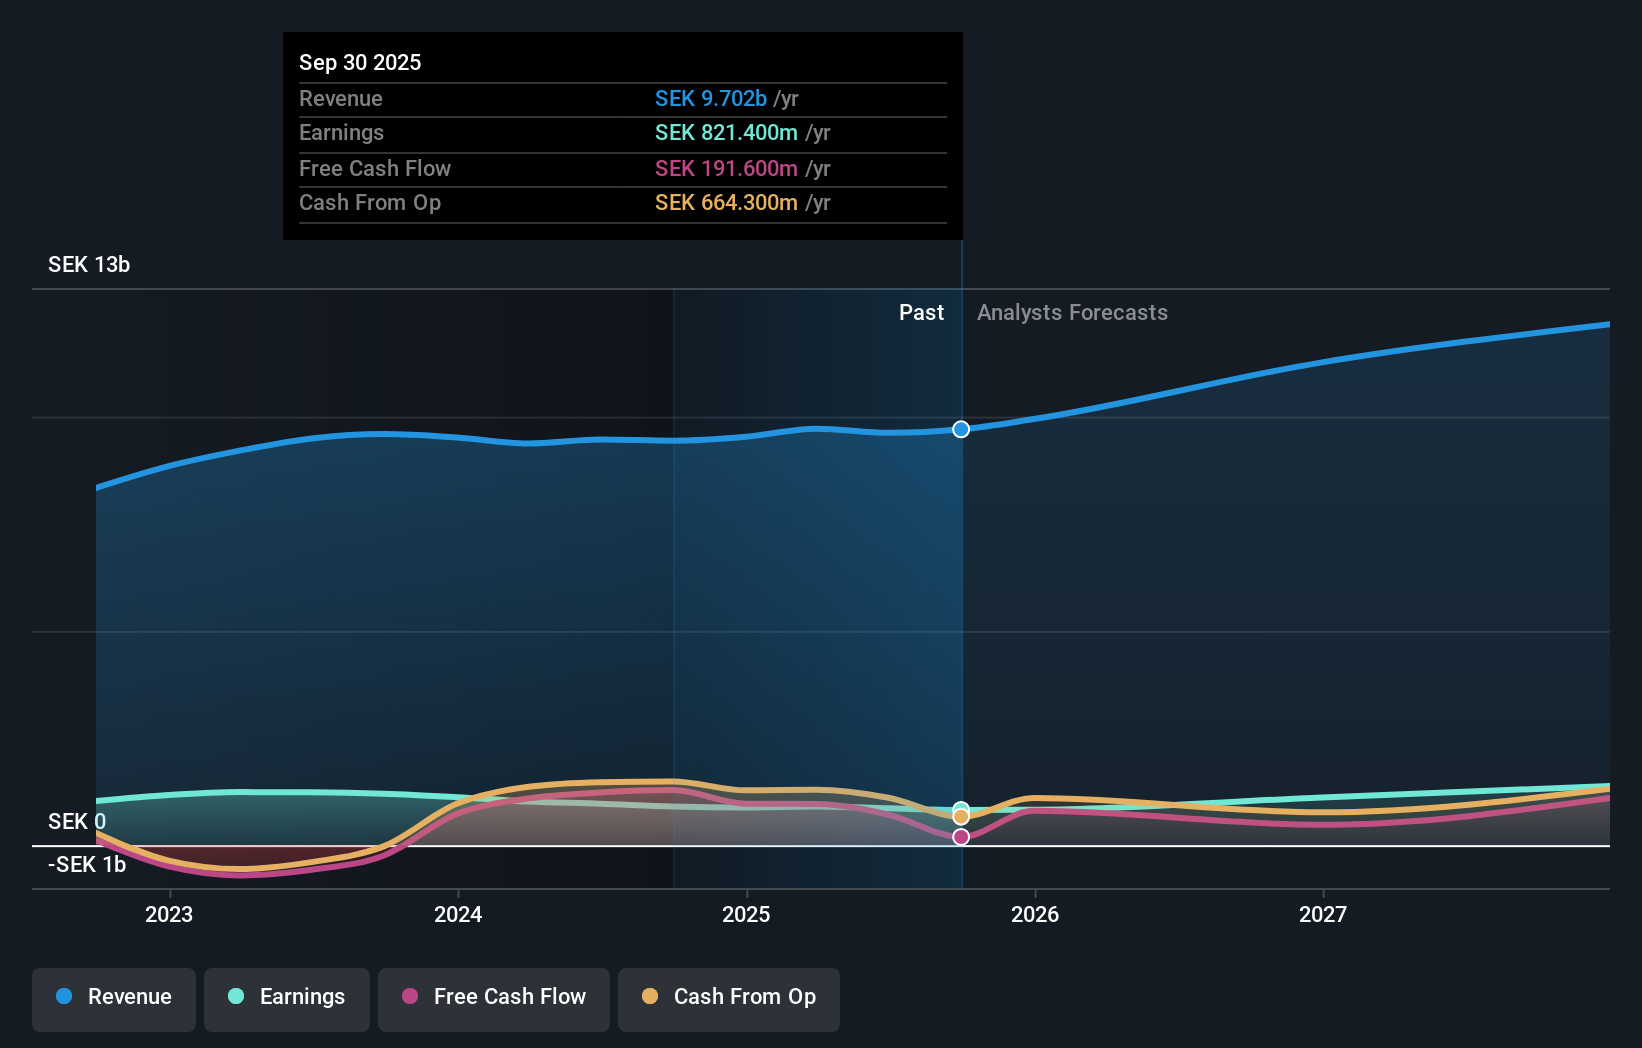
Overview: New Wave Group AB (publ) is involved in designing, acquiring, and developing brands and products across the corporate, sports, gifts, and home furnishings sectors globally, with a market cap of SEK13.23 billion.
Operations: The company's revenue is segmented into Corporate (SEK5.44 billion), Sports & Leisure (SEK4.18 billion), and Gifts & Home Furnishings (SEK862 million).
Insider Ownership: 35%
Earnings Growth Forecast: 22.9% p.a.
New Wave Group AB shows promising growth prospects with earnings expected to rise significantly at 22.9% annually, outpacing the Swedish market. Despite revenue growth being slower at 7.1%, it still surpasses the national average. The company trades at a substantial discount of 53.4% below its estimated fair value but faces challenges with debt coverage by operating cash flow and unsustainable dividends. Recent insider buying suggests confidence in strategic acquisitions, aligning with their successful acquisition history despite profitability hurdles initially faced by target companies.
- Get an in-depth perspective on New Wave Group's performance by reading our analyst estimates report here.
- The analysis detailed in our New Wave Group valuation report hints at an deflated share price compared to its estimated value.
Seize The Opportunity
- Explore the 205 names from our Fast Growing European Companies With High Insider Ownership screener here.
- Interested In Other Possibilities? Trump has pledged to "unleash" American oil and gas and these 22 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com